
When you're a sole trader in the UK, the buck stops with you. You're the captain of the ship, the head chef, and the chief bottle-washer all rolled into one. This means you're personally on the hook for your business's finances, which boils down to keeping good records of your income and expenses and filing a Self Assessment tax return every year.
The good news? It's simpler than running a limited company. There’s no legal wall between you and your business. But that also means good organisation is absolutely vital to stay on HMRC's good side and, just as importantly, keep your tax bill as low as legally possible.
Your Guide to Sole Trader Accounting
So, you’ve taken the plunge and become your own boss. Fantastic! While you're busy delivering great work for your clients, there’s the small matter of accounting for sole traders in the UK. Don't switch off just yet. This isn't about becoming a maths whizz overnight or getting lost in dusty ledgers. It’s about getting smart with your money so you can keep more of it.
Forget that classic shoebox overflowing with faded receipts (we’ve all seen one, usually under the passenger seat). A simple, organised system is your best friend in business. Think of this guide as your co-pilot, here to walk you through the essentials without the confusing jargon. We’ll cover tracking what comes in, what goes out, and—crucially—how to stay on the right side of HMRC.
Why Good Accounting Matters
Getting your books in order is so much more than a box-ticking exercise you rush through before the tax deadline. It's the engine room of your business. When you have a solid handle on your finances, you can:
- See Your True Profit: Know exactly how much money you're really making after all your costs have been taken out. No more finger-in-the-air guesstimates!
- Lower Your Tax Bill Legally: Spot every single allowable expense you can claim, which directly reduces the amount of tax you have to pay. Every little helps!
- Plan for the Future: Make smarter business decisions based on real numbers, not just a gut feeling.
- Avoid HMRC Headaches: Keep clear, accurate records that make filing your Self Assessment a breeze and ensure you’re prepared if the tax inspector ever comes knocking (unlikely, but best to be ready!).
Think of it this way: good accounting is like having a clear map for your business journey. Without it, you’re just driving in the fog, hoping you end up somewhere profitable.
To get started, let's break down your main duties. Don't worry, they're far more straightforward than they sound. This table gives you a quick glance at your core responsibilities, what they actually mean in plain English, and why they're so important for your success.
Your Core Accounting Responsibilities At a Glance
| Responsibility | What It Means in Plain English | Why It's Important |
|---|---|---|
| Record Keeping | Keeping track of all your sales invoices, purchase receipts, and bank statements. | This is your proof for HMRC. It helps you calculate your profit and claim every expense you're entitled to. |
| Self Assessment | Filing an annual tax return with HMRC to declare your income and pay the right amount of tax and National Insurance. | It's a legal requirement. Getting it wrong can lead to penalties and feeling a bit silly. |
| Paying Tax & NI | Making sure you pay your Income Tax and Class 2 & Class 4 National Insurance contributions on time. | Avoids late payment penalties and interest charges from HMRC. They're not known for their sense of humour on this. |
| VAT Registration (If applicable) | Registering for Value Added Tax if your annual turnover exceeds the £90,000 threshold (as of April 2024). | It's mandatory once you hit the threshold. Failing to register on time results in fines. |
Getting these basics right from day one will save you a world of stress down the line. Ready to dive a little deeper? Let's get into it.
Building Your Financial Foundation
Alright, let's get down to brass tacks. Building a solid financial foundation for your sole trader business isn't about wrestling with monstrous spreadsheets or becoming a numbers nerd overnight. It’s about creating simple, repeatable habits that will save you a world of pain later.
Think of it less as ‘doing the accounts’ and more as setting up a ridiculously simple filing system for your money. The goal is to know exactly what’s coming in and what’s going out, without having a meltdown every time you think about your tax bill.
With approximately 4.4 million self-employed people in the UK as of early 2025, you're in good company. Getting this part right is what separates the thriving from the just-surviving.
The Golden Rule: Separate Your Finances
Before you do anything else, commit this to memory: keep your business and personal finances separate. This is the single most important piece of advice for any new sole trader. While it’s not a legal requirement, mixing your business income with your weekly shop is a recipe for chaos.
Imagine trying to find a single red sock in a washing machine full of multi-coloured laundry—that’s what your accounts will look like. Opening a separate business bank account makes everything clearer. It creates a clean, undeniable record of your business transactions, making it a doddle to track your performance and prepare for your tax return.
Choosing Your Record-Keeping Weapon
How you track your finances is up to you, but your choices generally fall into two camps. There’s no right or wrong answer, only what works best for your brain and your business.
1. The Trusty Spreadsheet
For many sole traders just starting out, a well-organised spreadsheet is perfectly fine. It's cheap (often free!), and you're in complete control.
- Pros: No cost, highly customisable, and helps you understand the nuts and bolts of your finances.
- Cons: Prone to human error (typos happen!), can become clunky as your business grows, and offers zero automation.
2. User-Friendly Accounting Software
Modern accounting software is designed for people who aren't accountants. It can automate tasks, link to your bank account, and make life significantly easier.
- Pros: Saves a huge amount of time, reduces errors, provides real-time financial insights, and helps you stay compliant.
- Cons: Comes with a monthly subscription fee, and there can be a slight learning curve at the start.
Your record-keeping system is your financial dashboard. A basic spreadsheet is like the simple speedo in an old car, while accounting software is like a modern car's digital display, giving you fuel efficiency, trip distance, and a sat-nav all in one.
Exploring the benefits of cloud-based accounting can show you how these tools connect all your financial dots automatically, from invoicing to tax estimates.
Your Essential Tracking Checklist
Whatever method you choose, you need to capture the same core information. Think of this as your non-negotiable checklist for every transaction. Getting into the habit of logging these details now will feel like a superpower come tax time.
Your simple financial filing system should include:
- All Your Income: Every single penny you earn from your business activities.
- All Your Business Expenses: Anything you spend money on that is wholly and exclusively for your business.
- VAT Records: If you are VAT-registered, you must keep records of the VAT you charge and pay.
- Personal Drawings: Any money you take out of the business for personal use.
Beyond managing your business accounts, building a strong financial foundation also includes personal safety nets. It's wise to learn more about how to protect your income with income protection and redundancy cover, as sole traders don't have access to employee benefits like sick pay.
Taking these simple steps creates a rock-solid base, allowing you to focus on what you do best—running your business.
Decoding Your Allowable Expenses
Right, this is the part where all that careful record-keeping really starts to pay off. Think of this as a bit of a treasure hunt. Every legitimate business cost you can dig up is a golden nugget that helps lower your final tax bill.
It’s simple, really. HMRC has a long list of costs you can deduct from your income before they work out how much tax you owe. Your job is to become a savvy expense-spotter, claiming everything you're entitled to without straying into dodgy territory. Getting this right is fundamental to good accounting for sole traders in the UK.
Let’s be clear, this isn’t about pulling a fast one on the taxman. It’s about knowing the rules of the game. The golden rule is that an expense must be “wholly and exclusively” for your business. Let's break down what that actually means for some of the most common costs.
Your Home as Your Office
One of the big perks of working from home is being able to claim a portion of your household running costs. After all, your business is using your electricity, heating, and internet. HMRC gives you two main ways to approach this.
1. The Simplified Method (The "Easy Button")
This is a straightforward flat-rate allowance based on how many hours you work from home each month. It's wonderfully simple and saves you from doing any fiddly calculations.
- 25-50 hours a month: You can claim £10 per month.
- 51-100 hours a month: You can claim £18 per month.
- 101+ hours a month: You can claim £26 per month.
It might not seem like a life-changing amount, but it adds up over the year and saves you the headache of trying to split utility bills.
2. The Actual Costs Method (The "Detailed Approach")
If you think the flat rate doesn't quite cover it, you can calculate the actual business portion of your household bills. This means working out what percentage of your home is used for business (say, one room out of five) and how much of the time it’s used for work. You can then apply this percentage to costs like:
- Heating and electricity bills
- Council Tax
- Mortgage interest (just the interest part, not the capital repayment) or rent
- Home insurance
This route takes a bit more effort, but it can lead to a much larger claim if you have a dedicated office space you use regularly.
Common Expenses You Shouldn't Miss
Beyond the home office, there’s a whole world of other allowable expenses out there. Keeping receipts for these is absolutely vital. Here are some of the main categories to keep an eye on.
- Office Supplies: This covers everything from printer paper and pens to software subscriptions like Microsoft 365 or Adobe Creative Cloud.
- Travel Costs: You can claim for fuel, train tickets, bus fares, and parking when you're travelling for business. Just remember, your daily commute from home to a regular workplace doesn’t count.
- Marketing and Advertising: The cost of running your website, getting business cards printed, or paying for online ads on Google or social media are all fair game.
- Legal and Financial Costs: Fees you pay to an accountant (like us!), a solicitor for business matters, or for your professional indemnity insurance are all fully deductible.
- Stock and Materials: If you make or sell physical products, the cost of the raw materials or the items themselves is a core business expense.
Claiming expenses isn’t about cheating the system; it’s about playing by the rules. HMRC fully expects you to claim what you’re owed. Think of it as a game where the prize is keeping more of your own hard-earned money.
What You Absolutely Cannot Claim
Now for the danger zone. HMRC is very strict about certain costs that are never allowable, no matter how much you feel they relate to your work. A few common no-gos include:
- Entertaining Clients: Taking a client out for lunch to seal a deal? Great for building relationships, but unfortunately, the cost is not tax-deductible.
- Everyday Clothing: While a branded uniform might be deductible, that smart suit you bought for client meetings is considered everyday wear, so you can't claim for it.
- Travel Between Home and Work: The daily commute is always seen as a personal expense.
- Fines and Penalties: Got a parking ticket on a business trip? Frustrating, but you can't claim that back.
Feeling a bit more confident about spotting those expenses? The key is simple: if you bought it purely for your business, keep the receipt and log it. If you need a hand untangling your expenses to make sure you’re claiming everything you possibly can, get in touch with us at Artema. We can help turn your expense-spotting into a fine art.
Navigating Self Assessment and Tax Payments
Let's be honest, the words "Self Assessment" don't exactly spark joy. For many sole traders, it’s a dreaded annual ritual involving a frantic hunt for receipts and a lingering sense of panic. But what if we reframed it? Instead of a nightmare, think of it as a simple financial check-up for your business.
This is your straightforward plan for getting through the Self Assessment process without the usual stress. We'll demystify the key dates, the forms, and the payments so you can file on time and feel completely in control. Good accounting for sole traders in the UK is all about turning this process from a source of fear into a simple formality.
Your Most Important Deadlines
First things first, get these dates into your calendar. Missing HMRC deadlines is a surefire way to land an instant £100 penalty, and nobody wants that.
- 5th October: This is your deadline to register for Self Assessment if you're filing as a sole trader for the very first time.
- 31st January: This is the big one. It's the final deadline to file your online tax return and pay any tax you owe from the previous tax year.
- 31st July: This date is for your second 'Payment on Account' (we'll unravel this mystery in just a moment).
A crucial first step for any new sole trader is to understand how to register for Self Assessment tax properly. Getting this done and dusted early on removes a huge amount of pressure down the line.
The chart below gives you a simplified look at the key expense areas you'll need to have recorded before you even think about starting your tax return.
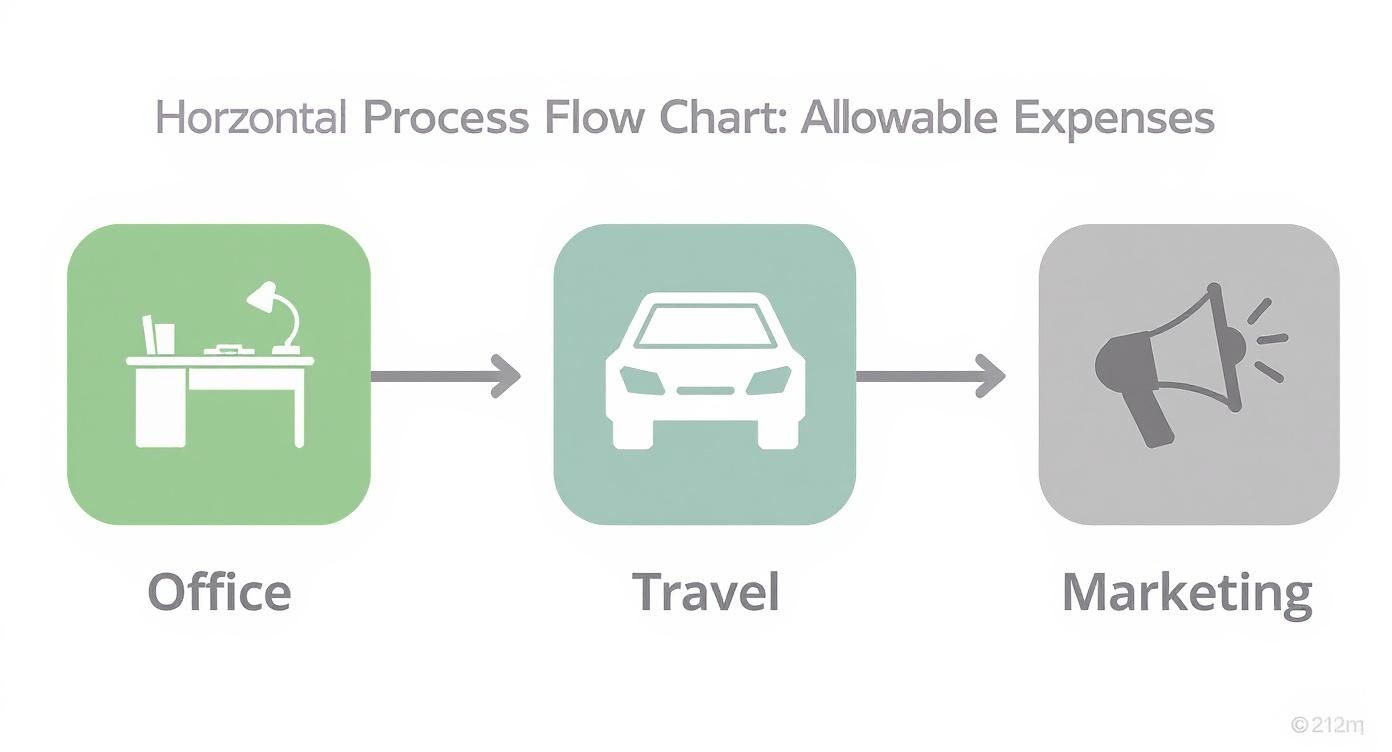
As you can see, your final tax calculation hinges on accurately tracking a whole range of expenses, from office costs right through to your marketing spend.
Unravelling Payments on Account
This concept often trips up new sole traders, so let's clear it up. Payments on Account are simply advance payments towards your next year's tax bill.
HMRC looks at your last tax bill and essentially assumes you'll earn a similar amount in the coming year. They then ask you to pay half of that estimated bill in advance on 31st January and the other half on 31st July.
Think of it like pre-paying for your electricity. You pay an estimated amount through the year based on past usage, and then you settle the final, actual bill later. Payments on Account work in exactly the same way for your tax.
This system can come as a real shock if you're not expecting it, making your first tax payment feel like a double-whammy. If this still feels tricky, our guide on self-employed Payments on Account offers a deeper dive into managing them without creating a cash flow crisis.
The Tax Pizza Analogy
So, what taxes are you actually paying? Imagine your total profit for the year is a big, delicious pizza. Before you get to enjoy it, HMRC comes along to take a few slices.
- Income Tax (The Big Slice): This is the main tax on your profits. The size of this slice depends on how much you earn, with different tax rates applied to different profit bands.
- Class 2 National Insurance (The Small, Fixed Slice): Think of this as a small, flat-rate contribution that gives you access to things like the State Pension. It's a fixed weekly amount.
- Class 4 National Insurance (The Percentage Slice): This is an extra contribution you pay, but only once your profits go over a certain threshold. It’s calculated as a percentage of those profits.
Your Self Assessment return is just you telling HMRC how big your pizza was, so they know how many slices to take. This is why tracking your expenses is so important—every allowable business expense shrinks the size of the pizza before HMRC takes its share!
Feeling overwhelmed? Don’t be. At Artema, we specialise in turning tax season into a smooth, straightforward process. Reach out to us, and let's make your next Self Assessment the easiest one yet.
Preparing for Making Tax Digital
Right, let’s talk about a big change on the horizon: Making Tax Digital, or MTD for short. Don't panic. This isn't nearly as scary as it sounds. Think of it less as a looming tax monster and more as HMRC finally catching up with the 21st century.
At its heart, MTD is the government's plan to swap the annual paper-chase tax return for a fully online system. The whole point is to make tax admin more efficient, accurate, and straightforward for everyone, including us sole traders. It’s all about ditching that shoebox full of receipts for digital records and compatible software.
Because of MTD, the way sole traders in the UK handle their accounts is changing fast. From April 2026, if you're a sole trader with an income over £30,000, you’ll need to send quarterly updates to HMRC. That’s a huge shift from the traditional yearly scramble. This is why so many business owners are getting ahead of the curve now, moving to accounting software to get their digital records in order.
What MTD for ITSA Actually Means for You
So, what's really changing? Instead of one massive tax return at the end of the year, the new system breaks it down into smaller, more manageable steps. It’s a bit like swapping one huge Sunday roast for several smaller meals throughout the week. Much easier to digest.
For sole traders, this system is called MTD for Income Tax Self Assessment (ITSA). Here’s how it works:
- Digital Records are a Must: You’ll need to keep all your business records—both income and expenses—digitally. That trusty spreadsheet you’ve been using might not cut it anymore; you'll need MTD-compatible software.
- Quarterly Updates to HMRC: Every three months, you'll send a summary of your business income and expenses to HMRC, straight from your software. These aren't final tax returns, just quick check-ins.
- End of Period Statement: At the end of your accounting year, you’ll finalise all your business income and expenses.
- Final Declaration: Just like you do now, you'll submit a final declaration. This is where you confirm any other income (like from a rental property or investments) and settle your final tax bill for the year.
The core idea behind MTD is simple: it encourages you to stay on top of your accounts in real-time, rather than having a massive, panic-induced accounting session every January.
Finding MTD-Compliant Software
The key to a stress-free MTD transition is picking the right software. HMRC won't let you just type your figures into their website anymore; you have to use software that can 'talk' directly to their systems.
When you’re looking for a tool, there are a few features you absolutely want:
- HMRC Recognition: First and foremost, the software must be officially recognised by HMRC as being MTD-compliant. No exceptions.
- Bank Feeds: It should connect directly to your business bank account, automatically pulling in transactions. Honestly, this is a game-changer.
- Receipt Capture: Look for tools that let you snap a photo of a receipt with your phone and upload it instantly. No more faded bits of paper.
- User-Friendly Interface: It should be designed for business owners, not accountants. You want something clear and simple, not overwhelmingly complex.
Many sole traders are already using digital systems for their VAT returns, so the principles are quite similar. If you're curious, you can check out our guide on whether your accounts system complies with MTD for VAT to get a better feel for the requirements.
Getting ready for MTD now is a smart move. It gives you time to choose your software, get comfortable with a new digital routine, and turn what seems like a big hurdle into a simple, organised part of your business. If you’re unsure where to start, give the team at Artema a call. We can help you find the perfect software and make your MTD transition completely seamless.
Ready to Master Your Finances?
Right, you've made it through. The world of accounting for sole traders in the UK probably feels a lot less like a foreign language now.
You should have the confidence and the know-how to get a real grip on your finances. This isn’t just about getting through your tax return without a last-minute panic; it’s about building a healthier, more profitable business.
Let's boil it all down. If you do nothing else, commit these three golden rules to memory. Stick to them, and you'll always be on the right path, leaving the financial headaches behind for good.
The Three Golden Rules of Sole Trader Accounting
You don’t need to be a maths genius to get this right. It just takes a bit of discipline and a commitment to these core principles. They're the bedrock of a well-run business.
-
Separate Everything, Always: Your business is not your personal piggy bank. If you haven't already, open a separate business bank account today. Honestly, this one simple move makes tracking what's coming in and going out a thousand times easier. It gives you a true picture of how your business is actually doing.
-
Log It When It Happens: Don't let that pile of receipts fester in a shoebox or the glove compartment. Get into the daily habit of recording your income and expenses as they happen. Whether you use a simple app or a spreadsheet doesn't matter nearly as much as the consistency. A few minutes each day will save you hours of frantic searching down the line.
-
Put Tax Money Aside: Never, ever think that all the money sitting in your business account is yours to spend. A brilliant rule of thumb is to shift 25-30% of every single payment you receive into a separate savings account. Think of it as your tax pot. When that bill from HMRC eventually lands, you'll be ready for it, completely calm.
Remember, good bookkeeping isn't a chore you do just for the taxman. It's the ultimate act of self-care for your business. It gives you the clarity you need to make smart decisions and the peace of mind to focus on growth.
Feeling a bit more in control? You should be. The journey from financial chaos to total clarity starts with one small, decisive action.
So, what's your first step going to be? Are you going to open that business bank account this afternoon? Or maybe download a free accounting app and log your first expense? Whatever it is, do it now while the momentum is with you.
If you're ready to make your financial admin truly effortless and want to be sure you're making the smartest moves for your business, get in touch with the team at Artema. We're here to help you turn these golden rules into an automated, stress-free system.
Your Burning Questions Answered
Right, let's get into the nitty-gritty. We've covered a lot of ground, but there are always a few lingering questions that pop up. Here are the most common ones we hear from sole traders, with straightforward answers.
Do I Really Need a Separate Bank Account?
Legally speaking, no. But from a practical, sanity-saving point of view? Absolutely, one hundred percent, yes!
Trying to unpick your business income from your weekly shop at Tesco or your personal bills is a recipe for disaster come tax time. A separate account gives you a crystal-clear picture of what’s coming in and going out of the business, which makes filling out your tax return infinitely less painful.
When Exactly Do I Have to Register as a Sole Trader?
You need to let HMRC know you're in business as soon as you've earned more than £1,000 from your self-employment in a single tax year. This is your ‘trading allowance’. The tax year runs from 6th April to 5th April, by the way.
Once you cross that £1,000 threshold, you're officially on the clock to register for Self Assessment. Don't put it off—the deadline is the 5th of October following the end of the tax year you started trading.
How Long Should I Keep All My Receipts and Records?
HMRC is very specific about this. You must hang onto your records for at least five years after the 31st January submission deadline for that tax year.
So, for the 2023-24 tax year (which you'll file by January 2025), you need to keep those records safe until at least the end of January 2030. It sounds like a long time, but a simple digital folder makes this a piece of cake.
Can I Pay Myself a Salary?
This is a really common point of confusion. As a sole trader, you and your business are legally the same entity. That means you don’t pay yourself a formal salary through a payroll system like you would in a limited company.
Instead, you just take money out of the business for your personal use. In the accounting world, we call these 'drawings'. The good news is there’s no tax on the drawings themselves. You simply pay tax on the business's overall profit for the year, no matter how much cash you've taken out.
Think of your business account as a pot of money. Your profits are whatever is left in that pot after you've paid all your expenses. Your 'drawings' are just you dipping into that pot to pay for your own life. HMRC is only interested in the total profit left in the pot at the end of the year, not how many times you took money out.
Feeling a bit clearer? We hope so. But if you've still got that one question nagging at you, that's what we're here for. At Artema Ltd, our job is to make accounting simple, so you can get on with running your business.
Get in touch with our friendly team today for a no-obligation chat. We'd love to hear about what you're building.