
Trying to get your head around buy-to-let and tax can sometimes feel less like a savvy investment and more like trying to solve a Rubik's Cube in the dark. The reality is simple: your rental income is taxable. The trick is understanding how it's taxed so you can keep your venture profitable and, of course, keep the taxman happy.
Your Guide to Nailing Buy-To-Let Tax
So, you're a landlord. Congratulations! It's an exciting path, but let's be honest, the moment someone mutters "buy to let and tax," it’s easy to feel a sudden urge to hide under the duvet. You probably imagined yourself collecting rent and maybe fixing the odd leaky tap, not spending your evenings wrestling with tax codes.
Think of this guide as your plain-English translator for all things HMRC. We're here to slice through the jargon and lay everything out clearly, simply, and without the usual headaches.
Our goal is to give you the confidence to handle your landlord taxes like a pro. When you know the rules, you can plan ahead, sidestep any nasty surprises, and make your property investment really work for you. We’ll cover the absolute must-knows to get you started:
- Income Tax: How your rental profit is actually worked out and taxed.
- Allowable Expenses: The glorious list of costs you can subtract to shrink your tax bill.
- Section 24: The infamous rule change that completely shook up the landlord world (we'll make it simple, promise).
- Capital Gains Tax: What you need to know for when you eventually sell up.
Before we dive into the nitty-gritty, let's have a quick peek at the main taxes you'll bump into on your landlord journey.
Key UK Landlord Taxes At A Glance
| Tax Type | What It's For | The Lowdown |
|---|---|---|
| Income Tax | Your rental profits (income minus your running costs). | The profit gets added to your other income (like your salary) and is taxed at your personal rate (20%, 40%, or 45%). |
| Capital Gains Tax (CGT) | The profit you make when you sell your rental property. | You get a tax-free allowance each year, and the rate you pay depends on how much you earn. |
| Stamp Duty Land Tax (SDLT) | The tax on buying the property itself. | There's a 3% extra charge on top of the usual rates for additional properties, which can be a hefty upfront cost. |
| National Insurance Contributions (NICs) | If being a landlord is your main job and your profits are over a certain amount. | Most landlords don't pay this, but it's good to know the rules if property is your full-time gig. |
This table gives you the headlines, but the real devil is in the detail, which we'll unpack throughout this guide.
The Big Picture on Property Tax
At its heart, being a landlord means you're running a business, and the taxman rightly wants a slice of the profits. Your rental income gets added to any other cash you have coming in, like a salary, to work out your total Income Tax bill for the year.
However, the world of buy to let and tax has been shaken up more than a James Bond martini recently. The arrival of Section 24 back in 2017 was a massive game-changer, and not in a good way for many landlords. It scrapped the ability to deduct your full mortgage interest payments as an expense.
Instead, you now get a basic-rate tax credit. This single change meant a landlord who once paid £1,600 in tax could suddenly see their bill leap to around £3,000, even if their rent and mortgage costs stayed exactly the same. Ouch.
Getting landlord tax right isn't just about ticking boxes for HMRC; it's about smart strategy. Knowing what you can claim and how rules like Section 24 affect your bottom line is the difference between a thriving portfolio and a financial headache.
This guide will walk you through each piece of the puzzle, turning confusion into confidence. For a wider look at keeping your tax liabilities down, these 8 Real Estate Investment Tax Strategies for Savvy Investors are well worth a read.
Ready to get started? Let’s dive in.
Figuring Out Your Rental Income Tax
Alright, let's get down to the brass tacks: working out how much tax you actually owe. It might sound scary, but the basic idea is surprisingly simple.
Think of your buy-to-let property as a little corner shop. The rent you collect is your total sales for the year. From this, you subtract your running costs—what HMRC calls ‘allowable expenses’. Whatever is left is your profit, and that’s the number the taxman is interested in.
What's Your Total Rental Income?
First things first, you need to add up all the money you’ve received from tenants over the tax year (which runs from 6th April to 5th April). This is your gross rental income, and it's the starting point for all your sums.
For most landlords, this is just the monthly rent. But don't forget to include any extra payments from tenants for things like cleaning shared areas or covering bills if that's part of your deal. It's worth remembering that tax rules are different everywhere; for instance, understanding your Australian rental income tax obligations involves a whole different rulebook.
Once you have that total income figure, the next job is to work out your taxable profit by taking away your allowable expenses. We’ll get to the fun part (expenses!) in the next section, but for now, just remember that profit is what you'll be taxed on.
How Your Profit Gets Taxed
Here’s a super important point that catches many new landlords out: your rental profit isn't taxed on its own. HMRC adds it on top of your other earnings for the year, like your salary or pension. This combined total decides which Income Tax band you fall into.
The UK tax system has different rates for different levels of income:
- Basic Rate: You pay 20% tax.
- Higher Rate: The tax rate jumps to 40%.
- Additional Rate: For the top earners, the rate is 45%.
These bands have specific income levels, and your rental profit can easily nudge you into a higher bracket than you might expect.
It's a classic rookie mistake. Your day job might put you comfortably in the basic rate, but adding a few thousand pounds of rental profit could tip you over into the 40% tax band, making your overall tax bill much bigger.
A Quick Example
Let's put this into practice. Meet Sarah, a landlord who also works full-time.
- Total Annual Rent: Sarah gets £15,000 in rent over the tax year.
- Allowable Expenses: She spends £3,000 on things like insurance, repairs, and letting agent fees.
- Taxable Profit: Her rental profit is £12,000 (£15,000 – £3,000).
- Total Taxable Income: Sarah earns a salary of £45,000. Her total taxable income is now £57,000 (£45,000 + £12,000).
- The Tax Bill: This total income pushes her into the higher-rate tax band. This means a chunk of her rental profit will now be taxed at 40%, not the 20% she might have guessed.
This simple example shows just how vital it is to see the whole picture. Figuring this out helps you budget properly and avoid any heart-stopping moments when the tax bill lands on your doormat. Ready to learn how to legally shrink that profit figure? Let’s talk expenses.
Claiming Your Allowable Expenses
Now for the part every landlord loves. Think of allowable expenses as your secret weapon in the battle against a big tax bill. Getting your head around buy to let and tax isn't just about paying what you owe; it's about making absolutely sure you don't overpay by a single penny.
These expenses are simply the legitimate, day-to-day costs of running your property rental business. By subtracting them from your rental income, you shrink your taxable profit. This isn't about sneaky tax avoidance; it's about being smart and claiming everything you are legally entitled to.
What Makes an Expense "Allowable"?
The golden rule from HMRC is that any expense must be ‘wholly and exclusively’ for the purpose of renting out the property. In plain English, if you bought it or paid for it specifically for your rental property, there's a very good chance you can claim for it.
This is where good record-keeping becomes your new best friend. A shoebox overflowing with faded receipts from two years ago just isn't going to cut it when you're trying to remember if that trip to B&Q was for your tenant's leaky tap or your own wonky garden shed.
Keeping a simple spreadsheet or using proper accounting software will save you a world of pain and help you claim every last eligible expense.
Repairs vs. Improvements: A Crucial Difference
This is a classic banana skin for new and even experienced landlords. Understanding the difference between a repair and an improvement is absolutely vital because HMRC treats them very differently.
- A repair is tax-deductible. It's all about fixing something that was already there but is now broken or worn out. You're basically putting the property back to how it was.
- An improvement is a capital expense and is not tax-deductible from your rental income. This is when you upgrade or add something brand new that wasn’t there before, making the property better.
A great way to think about it is this: fixing a broken boiler is a repair you can claim for. Ripping out that old boiler and installing a fancy new eco-system with underfloor heating is an improvement. One keeps things running; the other makes it fundamentally better.
But don't just bin those improvement receipts! While you can't deduct them from your rental income now, you can use these costs to lower your Capital Gains Tax bill when you eventually sell the property.
Common Allowable Expenses You Can Claim
Let's break down some of the most common costs you can—and definitely should—be claiming. This isn't the full list, but it covers the big hitters for most landlords.
- Letting agent and management fees: If you use an agent to find tenants or manage the property, their fees are fully deductible.
- Landlord insurance: Premiums for buildings, contents, and public liability policies are all fair game.
- Maintenance and repairs: This covers everything from fixing a dripping tap and repainting between tenancies to mending a fence or getting a gas safety check.
- Accountancy fees: The cost of hiring an accountant to help with your tax return is deductible.
- Utility bills: If you're paying for council tax, water, gas, or electricity at the property (maybe when it's empty), you can claim these costs.
- Direct running costs: This covers smaller but essential items like business-related phone calls, stationery, and adverts for new tenants.
Claiming these expenses diligently can make a huge difference to your final tax bill, turning a good investment into a great one. If you're feeling overwhelmed by the paperwork, that's where we can help. Get in touch with us at Artema, and we'll make sure your accounts are in perfect shape so you never miss a single claim.
Understanding Section 24 and Mortgage Interest
Right, let's tackle the elephant in the room for any landlord talking about buy-to-let and tax: Section 24. This single piece of legislation, often called the ‘tenant tax’, completely flipped the script on how you can handle your mortgage interest. If that sounds a bit dramatic, it's because for many landlords, it really was.
You could almost think of it as the government changing the rules of Monopoly halfway through a game. Before 2017, things were simple. The interest you paid on your mortgage was a business expense, just like your letting agent fees. You could deduct the entire amount from your rental income before calculating your tax bill. Easy peasy.
But Section 24 chucked that out the window. Instead of a full deduction, landlords now get a tax credit equal to 20% of their mortgage interest payments. On the surface, it might not sound too bad, but the impact on your final tax bill can be massive, especially if you’re a higher or additional-rate taxpayer.
The Old Way vs. The New Way
Let's see this in action. The best way to really get your head around it is to look at a simple before-and-after for a landlord in the 40% tax bracket.
Imagine a landlord, David, who gets £12,000 in rent a year and pays £5,000 in mortgage interest. His other running costs are £2,000.
Before Section 24 (The Good Old Days):
- Rental Income: £12,000
- Deductible Costs: £5,000 (mortgage interest) + £2,000 (other expenses) = £7,000
- Taxable Profit: £12,000 – £7,000 = £5,000
- Tax Bill (at 40%): £5,000 x 0.40 = £2,000
David's tax bill was clear, fair, and based on his actual profit.
After Section 24 (The New Reality):
- Rental Income: £12,000
- Deductible Costs: Only the £2,000 of other expenses can be deducted now. The mortgage interest is handled separately.
- Taxable Profit: £12,000 – £2,000 = £10,000
- Initial Tax Bill (at 40%): £10,000 x 0.40 = £4,000
- Tax Credit: Now, we apply the 20% credit on the mortgage interest: £5,000 x 0.20 = £1,000
- Final Tax Bill: £4,000 (initial tax) – £1,000 (credit) = £3,000
In this scenario, David's tax bill has shot up from £2,000 to £3,000—a whopping 50% increase—even though nothing about his property has changed. This is the real sting of Section 24.
Why This Matters More Than Ever
The problem has only been made worse by the recent rollercoaster of interest rates. Buy-to-let mortgage rates, which were sitting comfortably below 2% before 2022, rocketed to over 6% before starting to settle. This surge in borrowing costs now has a much bigger, more painful impact. In fact, research shows just how sensitive the market is to these changes. You can discover more insights about this on the Joseph Rowntree Foundation website.
Navigating these complexities is now absolutely essential. Exploring different mortgage solutions can help you structure your finances in the most tax-efficient way possible. This isn't just about hunting for a good rate anymore; it’s about smart planning to keep your investment healthy.
Feeling a bit dizzy after all that? You’re not alone. Section 24 has been a major headache for landlords. The key takeaway is this: your mortgage interest is no longer a simple deduction, and you absolutely must factor this new calculation into your financial planning. If you're struggling to make the numbers work, reach out to us at Artema. We can help you navigate the rules and make sure your buy-to-let business is set up for success.
Other Property Taxes Landlords Must Know
While Income Tax loves the spotlight in the world of buy to let and tax, it's far from the only player on the field. Think of Income Tax as your regular league season—it's consistent and happens every year. But there are a few crucial cup finals you need to be ready for, and ignoring them can lead to some painful financial surprises.
Let's walk through the other key taxes that should be on every landlord's radar, starting with the one you'll face when it's time to sell.
The Profit Police: Capital Gains Tax
Eventually, the day might come when you decide to sell your rental property. When you do, any profit you make from that sale is subject to Capital Gains Tax (CGT). Put simply, CGT is a tax on the 'gain'—the difference between what you originally paid for the property and what you sell it for.
Imagine you bought a property for £200,000 and later sell it for £275,000. Your 'gain' is £75,000, and it's this profit that HMRC is interested in.
Luckily, it’s not quite that simple. You can deduct certain costs from your gain, like estate agent fees, solicitor's fees, and the cost of any capital improvements you made over the years (like that new kitchen you couldn't claim against your rent). Everyone also gets an annual CGT allowance, which is a certain amount of gain you can make each year tax-free. For a deeper dive, check out our guide on capital gains on the disposal of a property.
The infographic below gives a great visual of how tax rules, such as Section 24, have moved from a simple deduction system to a tax credit model.
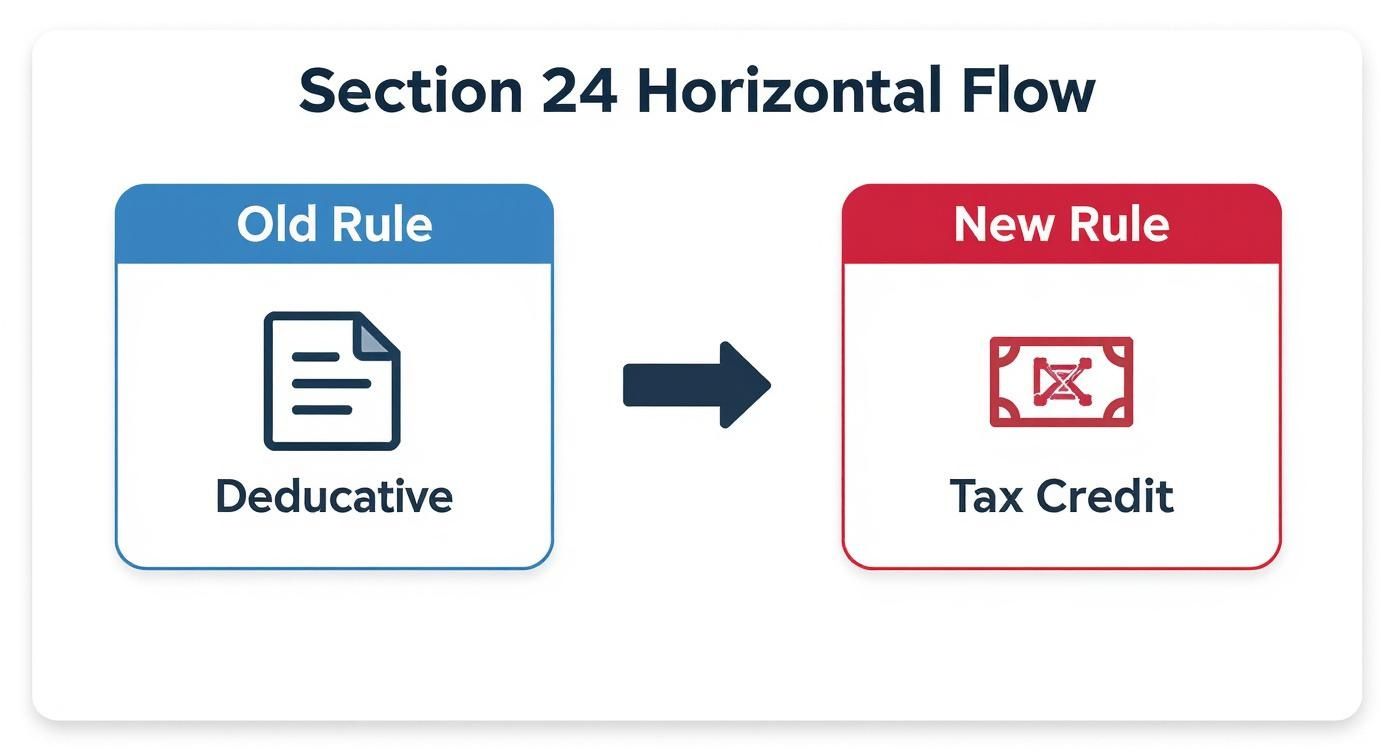
As you can see, this change effectively inflates a landlord's taxable income, which can easily push them into a higher tax bracket and increase their overall liability.
The Upfront Hurdle: Stamp Duty Land Tax
Before you even collect your first pound of rent, you’ll bump into Stamp Duty Land Tax (SDLT). This is a tax you pay when you buy a property in England or Northern Ireland, and for landlords, there's an extra sting in the tail.
If you're buying a second home or a buy-to-let property, you'll have to pay a 3% surcharge on top of the standard SDLT rates. This can add thousands to your upfront costs, so it’s something you must factor into your initial budget.
Think of the SDLT surcharge as a cover charge for entering the landlord club. It’s a big one-off cost that you need to be fully prepared for before you sign on the dotted line.
Beyond the Obvious: Other Considerations
Finally, a couple of other areas are worth a quick mention. Inheritance Tax (IHT) can come into play if you plan to pass your property portfolio on to your family. Property is a significant asset, and its value will be counted as part of your estate.
You may have also heard about landlords using a limited company to manage their properties. This can be a savvy move, especially for higher-rate taxpayers, as it neatly sidesteps the Section 24 mortgage interest rules. Profits are subject to Corporation Tax instead of Income Tax, but this route comes with its own set of costs and admin.
Navigating all these different taxes can feel like a lot to juggle. If you want to make sure you're planning effectively for every eventuality, why not book a consultation with us? We can help you build a strategy that works for you and your portfolio.
How To Tame Your Tax Paperwork
All the tax-saving strategies in the world are useless if you miss the filing deadline. When it comes to managing your buy-to-let tax obligations, being organised isn't just nice; it's the foundation of a stress-free landlord life.
Think of it as a gift to your future self—the one who won't be frantically rummaging through a drawer for a crumpled receipt on the 30th of January. The good news is you don't need a complicated system. A simple, well-kept spreadsheet can do the trick, or you could explore some of the excellent landlord software out there. The key is to find a method that works for you and stick to it.
What Paperwork Should You Keep?
Getting your records in order from day one will save you a world of pain later. HMRC can ask to see your records going back several years, so you need a system for storing everything safely. Your digital or physical landlord folder should include:
- Proof of Income: Keep all bank statements showing rent payments coming in.
- Proof of Expenses: This means every single receipt and invoice for anything you claim as an allowable expense.
- Agreements: Hold onto all tenancy agreements and contracts with letting agents.
- Mortgage Statements: These are vital, especially for calculating your tax credit.
So, how long do you need to play librarian with all this paperwork? HMRC requires you to keep your records for at least five years after the 31st January submission deadline of the relevant tax year.
Don't Miss The Self Assessment Deadlines
For landlords, the Self Assessment tax return is the main event. It’s how you declare your rental income and tell HMRC what you owe. Getting to grips with the process can feel a bit daunting, but our guide explaining Self Assessment tax returns breaks it down into simple, manageable steps.
There are a few dates you absolutely must burn into your calendar:
- 5th October: The deadline to register for Self Assessment if you're a new landlord.
- 31st January: The all-important deadline for filing your online tax return and paying any tax you owe from the previous tax year.
Missing the 31st January deadline isn't just a minor slip-up. It comes with an instant £100 penalty, even if you don't owe a penny in tax. The longer you delay, the more the penalties rack up. Nobody wants that!
Staying organised isn't about being perfect; it's about making your life easier. By keeping tidy records and being aware of the deadlines, you can turn tax time from a mad panic into a calm, straightforward process. Your future self will thank you for it.
Your Buy-to-Let and Tax Questions Answered
Even with the best guide in hand, a few head-scratchers are bound to pop up. Let's be honest, navigating the world of buy to let and tax often feels like a game where the rules are written in another language.
To help you out, we’ve gathered some of the most common questions we hear from landlords. Think of this as your quick-fire round to clear up those last few queries.
Do I Have to Pay Tax on Rental Income If I Make a Loss?
In a word, no! If your allowable expenses for the year are higher than your rental income, you’ve made a loss. The taxman doesn’t expect you to pay tax when you’re not making a profit. Phew.
But here’s the good bit: that loss isn’t just forgotten. You can carry it forward to use against profits from the same rental business in future years. It’s like having a tax-saving voucher tucked away for when things are looking up.
The crucial step is that you must declare the loss on your Self Assessment tax return. If you forget, you lose the chance to use it later, which would be a real shame.
Should I Set Up a Limited Company for My Buy-To-Let Property?
This is the million-dollar question for many landlords right now. Setting up a limited company can be a very smart move, especially for higher-rate taxpayers.
Why? The biggest perk is that it lets you sidestep those painful Section 24 mortgage interest rules. For a limited company, mortgage interest is a proper business expense, meaning you can deduct the entire amount before working out your profit. Your company then pays Corporation Tax on its profits, which can be lower than the 40% or 45% Income Tax rates.
However, it’s not a magic wand. There are a few downsides to think about:
- Extra Admin and Costs: Running a limited company means more paperwork and accountancy fees.
- Mortgage Challenges: Getting a mortgage for a company can sometimes be trickier and more expensive than a personal one.
- Getting Your Money Out: Taking money out of the company for yourself needs careful planning to be tax-efficient, usually through a mix of salary and dividends.
A limited company is a powerful tool, but it's not for everyone. It's like buying a high-performance sports car—fantastic if you know how to handle it, but overly complicated and expensive if all you need is a run-around for the weekly shop.
The only way to know for sure is to get professional advice. A quick chat can help figure out if the benefits outweigh the faff for your specific situation.
What Happens If I Lived in the Property Before Renting It Out?
This is a fantastic question and one that often comes with a very welcome tax break. If the property was your main home before you started renting it out, you could be eligible for something called Private Residence Relief (PRR) when you eventually sell it.
This relief can seriously slash your Capital Gains Tax bill. It works by making a portion of the gain on the sale completely tax-free.
The tax-free amount is based on two things:
- The number of years you actually lived in the property as your main home.
- Plus, the final 9 months of ownership are always exempt, even if you were renting it out during that time.
So, if you lived in your property for five years before letting it out for another ten, a big chunk of your profit would be exempt from Capital Gains Tax. It’s a valuable relief, so keeping clear records of when you lived there is a must.
Feeling clearer? We hope so. The world of buy to let and tax is certainly complex, but with the right knowledge, you can manage it with confidence. If you're tired of second-guessing your tax returns and want professional, friendly advice to make sure you're getting it right, the team at Artema Ltd is here to help. We'll take the stress out of the numbers so you can focus on being a great landlord. Book a consultation with us today!