
When you're running a business, it often feels like money is only ever flowing in one direction: out. But what if there was a way to get a decent chunk of that cash back from the taxman? Welcome to the wonderful world of capital allowances.
Think of them as a well-deserved thank you note from HMRC, rewarding you for spending money to improve your commercial property. This isn’t some sneaky loophole for giant corporations; it's a fantastic financial tool for any business owner who invests in their own premises. It's basically the tax system's version of a high-five.
A Guide to Unlocking Your Property Tax Savings
Let's say you've just bought a new office or given your warehouse a much-needed makeover. You've installed flashy new air conditioning, upgraded the lighting so it no longer feels like a bat cave, and fitted a top-notch security system.
You might just see these as boring business expenses. But with capital allowances, HMRC lets you deduct a slice of their value straight from your profits. This means your corporation tax bill shrinks. It's almost like getting a partial refund on investments you were going to make anyway. It’s a win-win!
This guide will break down capital allowances on commercial property without the confusing jargon. We’ll show you exactly how they can deliver:
- A much smaller tax bill: Keep more of your hard-earned money where it belongs – in your business.
- Happier cash flow: With less tax to pay out, you'll have more cash free for operations, growth, or maybe just a few extra biscuits for the break room.
- A better return on your building: Turn your property from a simple asset into a powerful tool for financial efficiency.
Why This Is a Big Deal Right Now
Getting a handle on your taxes is always a smart move, but it's especially important when property is involved. So many businesses completely miss this valuable relief, leaving a mountain of money on the table for HMRC. Don't be one of them!
And the scale of this is massive. In the 2023-2024 financial year alone, UK businesses claimed a staggering £175.7 billion in qualifying expenditure for capital allowances. This figure, from official government data, shows just how much is being invested and successfully claimed.
Of course, capital allowances are just one piece of the puzzle. A good landlord's guide to rental property tax deductions can reveal even more ways to manage your tax liabilities effectively.
By the time you've finished reading, you'll see capital allowances not as a daunting tax chore but as a golden opportunity. To explore more of our tax insights, check out our section all about tax.
Ready to find the savings hidden in the bricks and mortar of your business? Let's dive in.
Uncovering the Hidden Value in Your Building
Alright, it’s time to put on your treasure hunter hat. When you hear the term “plant and machinery,” what pops into your head? For most people, it’s conveyor belts, factory robots, or giant pieces of equipment that go "whirr".
While that’s not wrong, in the world of capital allowances on commercial property, the definition is much broader and, frankly, far more exciting. It covers a huge range of items embedded within your building—things you walk past every day without giving them a second thought.
Think of it this way: your building isn't just a big box. It’s an active environment packed with systems that let your business do its thing. Many of these systems are exactly the "plant and machinery" HMRC is interested in, and they hold some serious hidden value.
What Are Integral Features?
The real key to unlocking a hefty claim is getting to grips with integral features. These are the unsung heroes of your property; the essential systems that are literally part of the building's fabric. Without them, your commercial space would just be a cold, dark, and probably very damp box.
These features are so fundamental that they often get overlooked, mistaken as just "part of the building." But spotting them is like finding a forgotten £20 note in an old coat pocket—only on a much, much larger scale.
Let's break down some of the most common integral features you can claim for:
- Electrical and Lighting Systems: This covers all the wiring, sockets, trunking, and light fittings that keep your business lit up and powered on.
- Cold Water Systems: Every single pipe, tap, and tank bringing cold water into the property can qualify.
- Space or Water Heating Systems: We’re talking about the whole shebang—boilers, radiators, and all the pipework that connects them.
- Ventilation or Air-Conditioning Systems: Absolutely crucial for keeping everyone happy and productive, these complete systems are qualifying assets.
- Lifts, Escalators, and Moving Walkways: These complex bits of machinery are prime examples of claimable items.
- External Solar Shading: That fancy system you installed to keep the building cool in summer? That can count, too.
The crucial takeaway here is that you're not just claiming for a single boiler or a lightbulb. You can claim for the entire system that makes it work, from the main components down to the unseen wiring and pipework.
Spotting the Treasure in Your Own Property
Now, take a mental stroll through your own building. As you move from reception to the offices, the warehouse, or the shop floor, start noticing these systems. Look at the fire alarm panels, the CCTV cameras, the data cabling, and even the loos and sinks in the bathrooms.
These items represent thousands, or even hundreds of thousands, of pounds in potential tax relief. On average, the value of embedded plant and machinery in a commercial building can be anywhere from 15% to 45% of the property’s purchase price.
To give you a clearer picture, here’s a simplified breakdown of common items you can claim for.
Common Qualifying Assets in Commercial Properties
| Asset Category | Specific Examples | How It's Claimed |
|---|---|---|
| Electrical Systems | General lighting, emergency lighting, fire alarms, power distribution | Usually in the Main Pool (or Special Rate Pool for some long-life assets) |
| Mechanical Systems | Heating, air conditioning, ventilation, hot & cold water systems | Usually in the Special Rate Pool |
| Fixtures & Fittings | Kitchens, sanitaryware (toilets, sinks), security systems, signage | Usually in the Main Pool |
| External Plant | Car park barriers, external lighting, specific drainage systems | Usually in the Main Pool (or Special Rate Pool depending on the asset) |
Recognising these opportunities is the first step towards a successful claim. Uncovering these details can make a massive difference to your tax bill.
For more detailed insights into managing your investments, you can explore our various articles on all things property.
How the Different Allowances Actually Work
Alright, let's talk numbers. Don't worry, we'll keep this simple and skip the headache-inducing tax manuals. Think of capital allowances not as a single tool, but as a toolkit with a few different instruments, each designed for a specific job.
Understanding how they work is the key to picking the right one for your commercial property investments. It’s like knowing the difference between a sledgehammer and a scalpel; both are useful, but you need to know when to use each one. Let's open up the toolkit and see what's inside.
The Instant Gratification: Annual Investment Allowance
First up is the star of the show: the Annual Investment Allowance (AIA). Imagine HMRC giving your business a generous 'tax-free spending voucher' every single year. That's pretty much what the AIA is.
It lets you deduct 100% of the cost of most qualifying plant and machinery from your profits in the year you buy it. This is the fast track to tax relief. Instead of waiting years to get the full benefit, you get it all upfront, which is a massive boost for your cash flow.
A huge development here is that the AIA limit was made permanent at £1 million from 1 April 2023. This gives businesses a huge, ongoing incentive to invest. You can read more about these crucial updates on PKF Francis Clark's website.
The Slow and Steady: Writing Down Allowances
So, what happens when you’ve used up your £1 million AIA, or you've bought something that doesn't qualify? This is where Writing Down Allowances (WDAs) come into play. Think of these as a slow-release vitamin for your business finances.
Instead of getting 100% tax relief at once, you claim a percentage of the asset's value each year. Your qualifying assets get sorted into two main 'pools':
- The Main Rate Pool: This is for most of your standard plant and machinery. You can claim a WDA of 18% on the reducing balance of this pool each year.
- The Special Rate Pool: This is for certain 'integral features' like air-con systems, electrical wiring, and other long-life assets. The allowance here is a more modest 6% per year.
While it’s not as instant as the AIA, it provides a consistent and valuable tax reduction over the lifespan of your assets.
The real art of claiming capital allowances on commercial property is using these different allowances together. A smart strategy often involves maxing out the AIA for the immediate tax hit, then letting WDAs handle the rest over time.
This infographic gives a great breakdown of how these allowances typically flow.
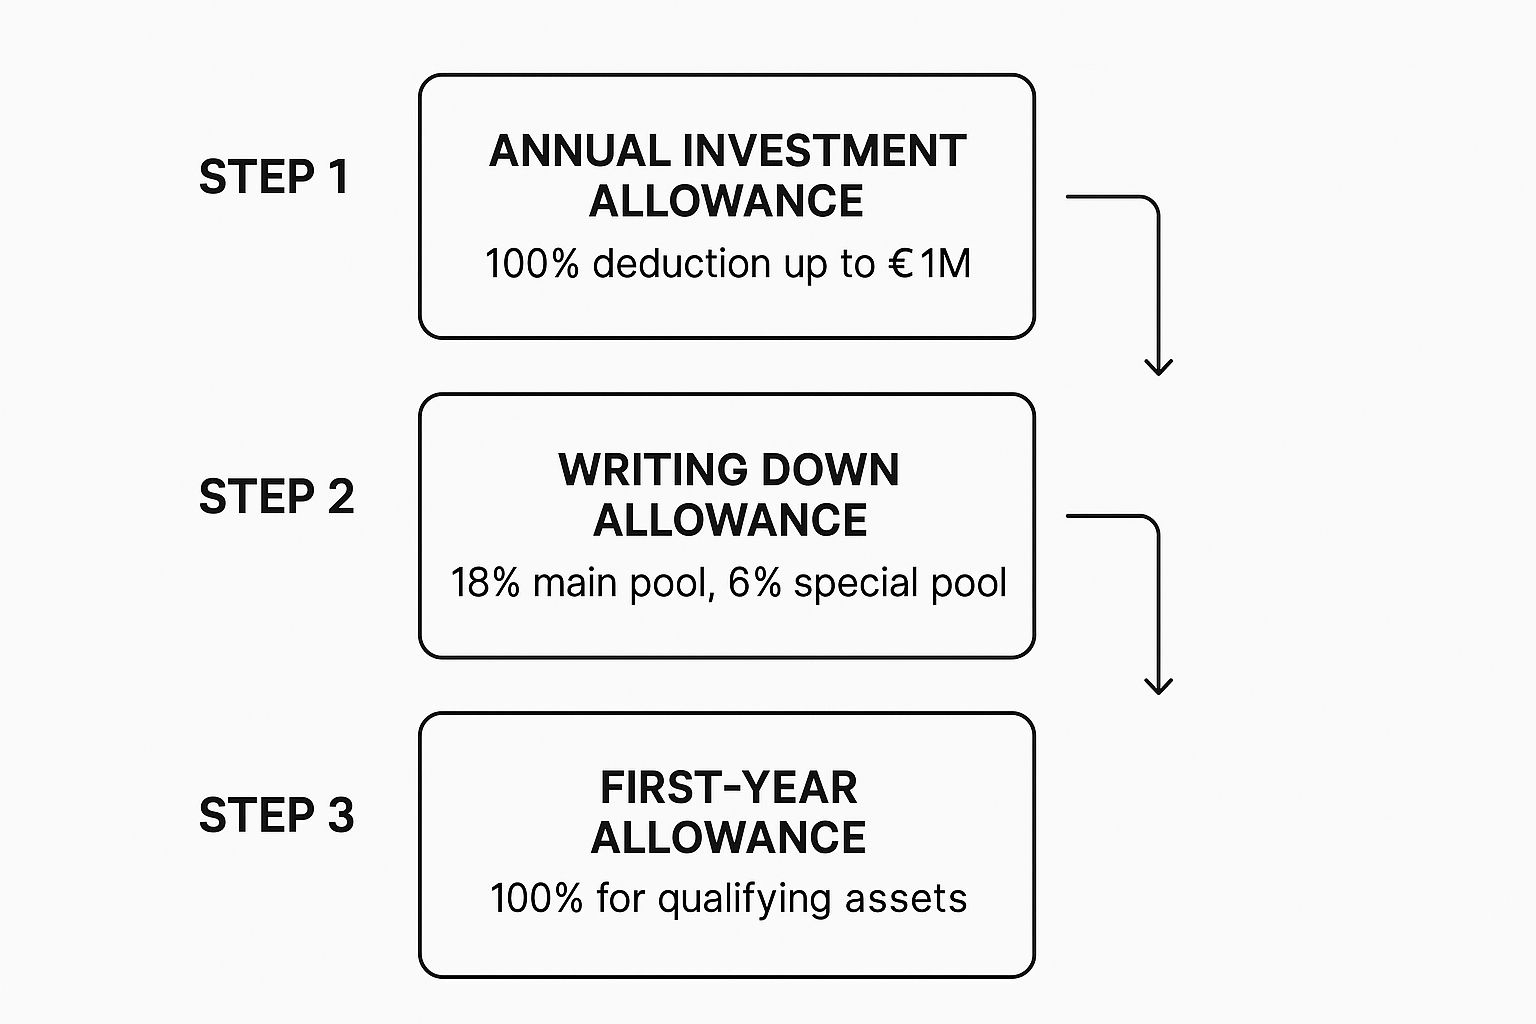
As you can see, there’s a clear hierarchy. You prioritise the powerful 100% upfront allowances like the AIA and FYA, followed by the steady, long-term relief from Writing Down Allowances.
The Turbo Boost: First-Year Allowance
Finally, there’s another handy tool in the box called the First-Year Allowance (FYA). This acts like a powerful accelerator for your tax savings, but only on specific types of assets.
Just like the AIA, it lets you claim 100% of the cost in the first year.
The catch is that FYAs are targeted at specific, government-approved investments. For instance, you could get a 100% FYA for buying new and unused zero-emission goods vehicles or certain energy-saving equipment. It's HMRC's way of giving you a pat on the back for making eco-friendly or tech-savvy choices.
Getting your head around these different options is the first step to building a really effective tax strategy for your property. Ready to see how we can put this into action for your business? Get in touch with our team today, and let's explore the hidden value in your building.
Making Your Claim: From Paperwork to Payout
So, you’ve unearthed the hidden value tucked away in your property and you’ve got your head around the different allowances. Now for the best part: turning that knowledge into real-world tax savings.
Making a claim might sound daunting, like you're about to venture into the labyrinth of HMRC’s filing system. But really, it’s more like following a good recipe. Get the steps right, and the result is brilliant.
The whole process is logical. With a bit of organisation, you can navigate it with confidence. This guide will walk you through it, from spotting your assets right up to seeing that lovely reduced tax bill. Let’s get that claim rolling.
A successful claim is built on a solid foundation of evidence, not guesswork. Getting your paperwork in order from the get-go is the smartest move you can make.
Stage 1: Identify and Value Your Assets
First things first: you need a detailed list of every single qualifying item. This is where you put those treasure-hunting skills to good use. Go through your property and document everything—from the big-ticket items like air conditioning and electrical wiring down to fire alarms and security cameras.
Once you’ve got your list, the next job is to assign a value to each item. If you’ve just finished a refurbishment, the invoices from your contractors are your new best friend. It gets a bit trickier if you've bought a property, as the cost of these embedded items is all bundled into the purchase price. This is often the point where many businesses realise they need a bit of professional help.
Stage 2: The Specialist Surveyor – A Real Game Changer
Let’s be honest, most of us can’t tell one commercial boiler from another, let alone put an accurate value on an entire building's electrical system. This is where a specialist capital allowances surveyor becomes your secret weapon. They’re part quantity surveyor, part tax expert, and they know exactly what to look for.
A specialist will carry out a detailed survey, identifying assets you might have overlooked and preparing a robust valuation report that HMRC will accept. Their fee is almost always a fraction of the tax they save you, making it one of the best investments in this whole process. In the UK, a good surveyor can often identify qualifying assets worth between 15% and 45% of a property's purchase price.
Think of it like this: you wouldn't try to fix your own teeth; you'd see a dentist. When it comes to something as specialised as capital allowances, bringing in an expert ensures the job is done right and your claim is maximised.
Stage 3: Crunch the Numbers and Make the Claim
With your comprehensive, valued list in hand, it’s time to do the maths. This breaks down into four key steps:
- Pool the Assets: You’ll group your assets into the correct pools—either the main rate pool (18% WDA) or the special rate pool (6% WDA).
- Apply the Allowances: Now, decide how to use the allowances you’ve learned about. You'll almost certainly want to use your £1 million Annual Investment Allowance (AIA) first to get that immediate 100% relief on as much as possible.
- Calculate the Relief: Once the allowances are applied, you can calculate the total deductible amount for that financial year.
- Submit to HMRC: Finally, this calculated figure is included in the capital allowances section of your company's corporation tax return (the CT600).
This final stage is where all your hard work pays off, translating directly into a lower corporation tax bill. It requires attention to detail, but it’s a clear path to some very significant savings.
Feeling ready to tackle your claim but want a helping hand? Our team at Artema specialises in making this process smooth and successful. Get in touch with us today, and let’s make sure you don’t leave a single penny on the table.
Common Pitfalls and How to Avoid Them
Navigating the world of capital allowances on commercial property can feel incredibly rewarding, but like any great adventure, there are a few banana peels lying around. Even the most clued-up investors can take a tumble if they aren't careful.
The good news? Most of these mistakes are easily avoidable once you know what to look for. Think of this as your guide to sidestepping the rookie errors, making sure your claim is as solid as possible. Let’s learn from the slip-ups of others so you don’t have to.
Mistake 1: Overlooking the Embedded Treasure
The single biggest mistake is also the simplest: completely forgetting about the "embedded" fixtures and fittings when buying a property. It’s a bit like buying a car and valuing it only for its chassis, ignoring the engine, electronics, and seats.
When a property changes hands, all those integral features we talked about—the wiring, heating, and plumbing systems—are often just seen as "part of the building." This is a huge oversight. These items represent a massive chunk of potential tax relief that often goes unclaimed because nobody thinks to look for it.
Solution: Always assume there's a claim to be had. Make a detailed capital allowances review a standard part of your to-do list whenever you acquire a new commercial property.
Mistake 2: The Awkward Silence at Closing
Another classic blunder happens during the property transaction itself. When you buy a building, both you and the seller need to formally agree on the value of the embedded plant and machinery. This is done through something called a Section 198 election.
Failing to agree on this value can cause chaos. If the seller has claimed allowances, you need to agree on a figure so you know what you can claim going forward. Ignoring this step can result in the value being fixed at £0, meaning you could lose the right to claim anything on all that historic spending. Ouch.
The lesson here is simple: talk about capital allowances early and get it in writing. It's far easier to agree on a value during the friendly negotiation phase than to try and sort it out months after the deal has closed. Don't let a moment of awkwardness cost you thousands in tax relief.
Mistake 3: Forgetting About Refurbishments
Many business owners think capital allowances only apply to brand-new purchases. They spend a significant sum upgrading their property and simply class it all as 'repairs' or 'improvements' in their accounts, missing a golden opportunity.
A major refurbishment is a prime time for a claim. Replacing an old heating system, installing a new electrical network, or fitting out a modern office kitchen are all activities packed with qualifying expenditure. The UK's commercial property market is booming, especially in cities like London, which has attracted over £68 billion in private investment over the last decade. This surge in acquisitions and refurbs creates countless opportunities for savvy investors to make claims. You can discover more insights about this trend and its impact on UK property investment here.
Avoiding these common pitfalls is all about being proactive. A little foresight can turn a potential problem into a massive tax-saving opportunity, ensuring you get the full benefit you're entitled to.
Feeling overwhelmed by the details? Don't be. Contact our expert team at Artema today, and we’ll help you navigate the process flawlessly, making sure no banana peels get in your way.
It’s Time to Unlock Your Property’s Hidden Value
You’ve now got the tools to make a real difference to your bottom line. Understanding capital allowances on commercial property isn't just a box-ticking exercise for your tax return; it's about actively reclaiming money you've already spent on your business. Think of it as a powerful financial lever just waiting for you to pull.
From complex heating systems right down to the humble fire alarm, every qualifying item we’ve covered represents a slice of your initial investment. Each one can be offset against your profits, which directly lowers your tax bill. Not taking advantage of this is like finding a winning lottery ticket and simply forgetting to cash it in.
Taking the Next Step
Knowledge is one thing, but action is where the real value lies. Don't let what you've learned here gather dust. The savings hidden within your property's fixtures and fittings are substantial, and the only way to tap into them is to get the process started.
Here’s a simple plan to get moving:
- Review Your Assets: Take a proactive look at any property you've bought or refurbished in the last few years.
- Gather Your Paperwork: Dig out those purchase contracts, refurbishment invoices, and any other related documents.
- Seek Expert Advice: Don't try to go it alone. A specialist can spot opportunities you'll almost certainly miss and ensure your claim is completely solid.
The most costly mistake you can make with capital allowances is simply assuming you don’t have a claim. It is always worth investigating—the rewards can genuinely transform your cash flow and provide the funds for your next growth phase.
Partner with a Specialist
While the basic ideas are fairly straightforward, maximising a claim really does require a specialist’s eye. An expert will make sure every single qualifying item is identified and valued correctly. It removes the stress from your shoulders and guarantees you get back every penny you’re entitled to. This turns a complex job into a simple and rewarding process. It's also vital to consider how this fits into your wider financial strategy. For example, you should also be familiar with the rules for capital gains on the disposal of a property to manage your tax position effectively over the long term.
Ready to Unlock the Secrets to Tax Efficiency and Financial Freedom? The money is right there, just waiting for you to claim it.
Don’t let this opportunity pass you by. Contact our expert team at Artema today for a no-obligation chat, and let’s start your journey to significant tax savings.
Frequently Asked Questions
You’ve made it this far, and hopefully, the world of capital allowances on commercial property feels a lot less mysterious. It’s normal to still have a few questions buzzing around. Think of this section as a quick Q&A to clear up any final thoughts before you go off and find those hidden tax savings.
Here are some quick-fire answers to the questions we hear most often.
Can I Claim Allowances on a Property I Bought Years Ago?
Absolutely, and this is a big one. You can often make a retrospective claim on a property you bought years ago, as long as the previous owner hadn't already claimed the allowances on the embedded fixtures.
There are time limits, of course, but it’s always worth investigating historical purchases. It's like finding a forgotten gift card down the back of the sofa, only this one could be worth thousands.
What Happens When I Sell the Property?
This is a great question. When you sell, the value of the allowances you’ve claimed is factored into a final calculation. This might result in a "balancing charge" (where you pay some tax back) or a "balancing allowance" (where you get a bit more tax relief).
The key is to handle this properly during the sale by agreeing on a value with the buyer. This is then formalised in a Section 198 election. A bit of paperwork now saves a massive headache later.
Is It Really Worth Hiring a Specialist?
In a word, yes. While you could technically make a claim yourself, a specialist surveyor will almost always identify far more qualifying items than an untrained eye. They know exactly what HMRC looks for and can prepare a robust, evidence-backed report that maximises your claim.
Think of it this way: you could try to service your own car, but a professional mechanic will do it faster, safer, and probably spot issues you’d never have noticed. The return on investment for using a specialist is usually incredibly high.
Don't let the fear of complexity stop you from claiming what you're owed. The process is straightforward with the right guidance, and the financial rewards can be a genuine game-changer for your business's cash flow.
Still have questions, or are you feeling ready to put this knowledge into action? Our team is here to help you navigate every step of the process.
Ready to uncover the hidden financial potential in your property? Artema Ltd specialises in helping business owners like you make the most of capital allowances. Get in touch with us today for a friendly, no-obligation chat!