
Ever sold an investment and had that nagging feeling, "Uh oh, does the taxman want a piece of this?" If you’ve nodded along, you're in exactly the right place. This guide is your friendly map to understanding Capital Gains Tax (CGT) on investments in the UK, without the headache-inducing jargon.
Think of it as the tax on the profit you make when you sell something for more than you paid for it. It's like selling a concert ticket for more than face value, but for your stocks and shares.
Your Guide to Capital Gains Tax on Investments
Let's kick off with a simple story. Imagine you bought a rare vinyl record for £20. A few years later, a collector offers you £100 for it. That lovely £80 difference is your 'capital gain', and HMRC is quite interested in getting a slice of that profit. That's the whole idea behind capital gains tax in a nutshell.
When you sell or 'dispose of' an asset and make a profit, that gain could be taxable. This doesn't just apply to records; it covers a whole bunch of common investments you might have.
What Investments Are We Talking About?
Most of us aren't trading rare vinyl, so what does this mean for your investment portfolio? The taxman's net is pretty wide and catches profits from several places:
- Shares and Stocks: Selling your shares in a company like BP or Tesla for more than you paid.
- Funds and Trusts: This includes popular investments like unit trusts and investment trusts.
- Property: Any property that isn't your main home, like that buy-to-let flat or holiday cottage.
- Cryptoassets: Yep, even your profits from selling Bitcoin or Ethereum are on HMRC's radar. Sorry!
Just a heads-up: a 'disposal' isn't just about selling for cash. It can also mean swapping one asset for another, giving it away as a gift, or getting an insurance payout for it.
The Get-Out-of-Jail-Free Cards
Now for the good news! Not every investment profit will land you with a tax bill. The government offers a few fantastic ways to grow your money without having to share it with the taxman.
The most popular is the Individual Savings Account (ISA). Any investments held within a Stocks and Shares ISA grow completely free of capital gains tax. The same goes for your pension pot. These tax-efficient wrappers are your best friends for long-term investing.
Feeling a bit overwhelmed? Don't be. Getting your head around the basics is the first step to being a savvy investor. For broader ideas, you might find this investor-focused advice on property and financial planning useful.
We're here to help you make sense of it all. If you want to see how these rules affect you, check out our other articles on capital gains tax or get in touch. A little planning goes a very, very long way.
Understanding the Capital Gains Tax Allowance
Everyone loves a tax-free perk, right? Think of the Capital Gains Tax (CGT) allowance, officially called the Annual Exempt Amount, as your personal tax-free bubble for investment profits. It's the amount of gain you can pocket each year before HMRC starts asking for its share.
It’s a fantastic benefit that lets you lock in some profit completely tax-free. But, and it’s a big but, this tax-free shield isn't as big as it used to be. Not by a long shot.
The Shrinking Shield: A Heads-Up for Investors
In a move that's caught many off-guard, the government has taken a rather large pair of scissors to this allowance. For any investor, this is a massive deal, as profits that were once comfortably shielded might now land you with a tax bill.
The annual exemption has been dramatically slashed. Back in the 2022-23 tax year, you had a generous allowance of £12,300. This was chopped by more than half to £6,000 for 2023-24 and then sliced in half again to just £3,000 for the 2024-25 tax year.
That’s a whopping 75% reduction in just two years. The tax net has been cast much wider, pulling more and more investors into paying CGT. You can explore a detailed history of these changes to get the full, slightly depressing, picture.
What does this really mean? It means even pretty modest gains from your investments could now be taxable. It’s a real game-changer that means you need to be a bit smarter about when you sell.
Use It or Lose It: A Golden Rule
One of the most important things to get your head around is that the annual allowance is strictly a ‘use it or lose it’ deal. You can't roll any unused part of it over to the next tax year.
The tax year runs from 6th April to 5th April. If you haven’t used your £3,000 allowance by the time the clock strikes midnight on 5th April, it simply vanishes. Poof. Gone forever. It resets on 6th April, giving you a fresh start.
This rule really encourages you to be on top of your portfolio. Instead of letting gains build up for years and facing a monster bill, it can be much smarter to cash in smaller profits each year to make the most of this tax-free perk.
This makes timing the sale of your assets a key part of smart tax planning. A little forward-thinking can save you a surprising amount of money.
A Smart Trick for Couples
Here's a brilliant—and perfectly legal—trick for married couples and those in a civil partnership. You can effectively double your tax-free power.
Each person gets their own individual Capital Gains Tax allowance. So, as a couple, you have a combined tax-free allowance. For the 2024-25 tax year, that’s a combined £6,000 (£3,000 each).
So, how can you use this to your advantage?
- Transfer Assets: You can transfer assets between spouses or civil partners without triggering a CGT bill. It’s a really handy tool.
- Share the Gain: The partner who receives the asset also inherits its original cost price. When they sell it, they can use their own annual allowance to offset the gain.
Let’s say one partner is sitting on an investment with a large gain. They could transfer half of it to their spouse. The spouse could then sell their portion, using their own £3,000 allowance to shelter the profit. It’s a simple yet powerful way to manage your capital gains tax on investments and keep more of your money in your household. Teamwork makes the dream work!
How To Calculate Your Investment CGT Bill
Alright, it’s time to crunch the numbers. But don't break out in a cold sweat! Working out your potential Capital Gains Tax (CGT) bill isn't nearly as scary as it sounds.
The whole thing boils down to three simple stages: work out your profit, take away your tax-free allowance, and then apply the right tax rate to what's left. That's it. Let’s do this.
Step 1: Work Out Your Total Gain
First things first, you need to figure out your actual profit. This isn't just the selling price minus the buying price; you can also deduct certain costs you picked up along the way. Think of it as calculating your net profit.
The basic formula is simple:
Selling Price – (Original Cost + Associated Fees) = Your Capital Gain
So, what counts as an 'associated fee'? These are the legit costs of buying and selling.
- Broker Fees: The commission you paid your trading app or broker.
- Stamp Duty: The tax you paid when you first bought the shares.
- Other Professional Fees: For more complex stuff, this could include a valuer's fee.
Keeping good records is absolutely key here. You'll need proof of these costs if HMRC ever comes knocking. Getting the details right is vital, and mastering investment portfolio tracking will make sure you have everything you need.
Step 2: Subtract Your Annual Allowance
Remember that tax-free bubble we talked about? Now's the time to use it. Once you have your total gain, you get to deduct your annual CGT allowance.
For the 2024-25 tax year, this allowance is £3,000. This means the first £3,000 of your profit is completely tax-free. Hooray! You only pay tax on the amount above this.
Think of the allowance as a head start in a race. Everyone gets to begin £3,000 ahead of the taxman. It’s only when your gains cross that line that you need to start paying.
The infographic below shows just how much this allowance has shrunk, making it more important than ever to do your sums.
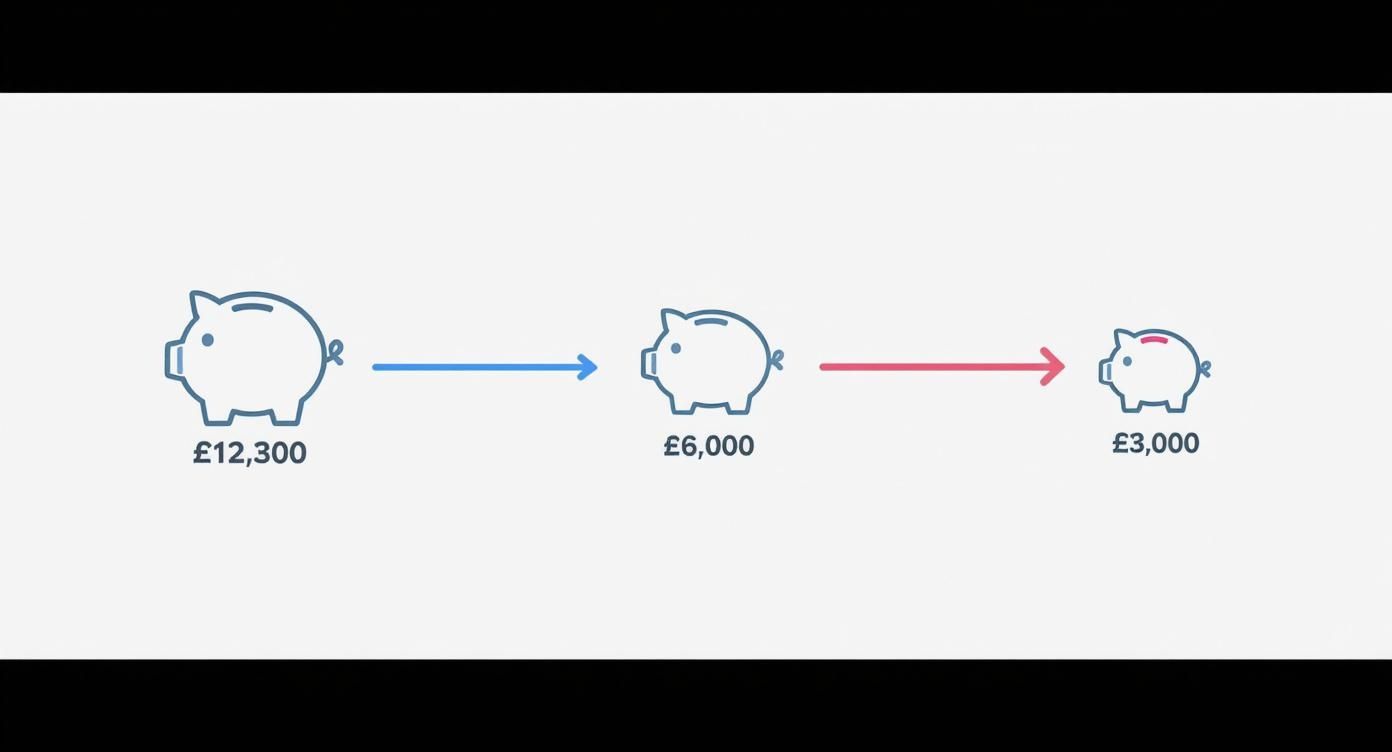
This picture really brings home the dramatic reduction, which means even smaller profits are now on the taxman's radar.
Step 3: Apply The Correct Tax Rate
This is the final hurdle. The amount of tax you pay on your remaining gain depends on two things: your Income Tax band and what you sold.
HMRC wants to know if you're a basic-rate or a higher-rate taxpayer. To figure this out, you add your taxable capital gain (the amount left after taking off your allowance) to your total taxable income for the year.
If the combined total keeps you in the basic rate band, you pay the lower CGT rate. If it pushes you into the higher rate band, you'll pay the higher CGT rate on the bit of the gain that falls into that band.
The rates are also different for different assets. You pay a lower rate on things like shares and funds, but a higher rate on residential property that isn't your main home. Our complete guide to what is the capital gain tax rate dives deeper into these specifics.
UK Capital Gains Tax Rates
Here’s a quick-glance table to make things clearer. It shows how your income affects the CGT you'll pay.
| Asset Type | CGT Rate for Basic-Rate Taxpayers | CGT Rate for Higher-Rate Taxpayers |
|---|---|---|
| Shares, Funds, and most assets | 10% | 20% |
| Residential Property (not main home) | 18% | 24% |
As you can see, the government is a bit tougher on property gains compared to other investments.
Let's See It In Action With Sam
Okay, theory is great, but let's make this real. Meet Sam, a basic-rate taxpayer.
- The Investment: A few years ago, Sam bought shares in a company for £10,000. The broker charged him £100 in fees.
- The Sale: This year, he sold them for £18,100. The selling fee was another £100.
- Calculate the Gain:
- Total Cost = £10,000 (purchase) + £100 (buy fee) + £100 (sell fee) = £10,200
- Total Gain = £18,100 (sale price) – £10,200 (total cost) = £7,900
- Subtract the Allowance:
- Taxable Gain = £7,900 (total gain) – £3,000 (allowance) = £4,900
- Apply the Tax Rate:
- Sam's taxable gain of £4,900, when added to his income, doesn't push him into the higher tax bracket. Since he sold shares, he pays the basic CGT rate of 10%.
- CGT Bill = £4,900 x 10% = £490
And there you have it! Sam’s final tax bill is £490. Not so bad when you break it down, right? Calculating your capital gains tax on investments is totally manageable.
If you need a hand with your own figures, don't hesitate to reach out to our team at Artema for some friendly, professional help.
How to Report and Pay Your CGT Bill
Right, you’ve crunched the numbers and worked out your profit. The hard part is over! Now it’s just a case of letting HMRC know and squaring up. Honestly, it's not as scary as it sounds.
Think of it like getting the bill after a good meal. You’ve enjoyed the profit from your investment, and now you just need to settle the tab. HMRC gives you a couple of ways to do this, and which one you use depends on what you’ve sold.
It might feel like a personal headache, but you're in a pretty exclusive club. In the 2023-24 tax year, CGT brought in a hefty £12.1 billion from just 378,000 taxpayers. So, pat yourself on the back for making a big contribution! You can discover more insights about these tax trends to see the bigger picture.
Choosing Your Reporting Route
For most people selling shares or funds, the path is simple: the annual Self Assessment tax return. But if you’ve sold a property, HMRC has a special fast-track service you need to use.
Let’s bring this to life with Chloe. This tax year, she sold two different assets:
- A portfolio of shares that did rather well.
- A buy-to-let flat she’s owned for years.
Because she’s sold two different kinds of assets, she’ll actually need to use both reporting methods.
The Real-Time Service for Property Gains
When Chloe sold her buy-to-let flat, she couldn't just pop the details on her next tax return. HMRC has strict rules for UK residential property sales.
She has to report the gain and pay the estimated capital gains tax on investments like property within 60 days of the sale completing. This is all done through HMRC's online 'real-time' Capital Gains Tax service. It's more of a sprint than a marathon, and missing that 60-day window can lead to penalties. Yikes.
The Self Assessment Tax Return
Things are much more chilled for the profit Chloe made from her shares. She'll simply report this on her Self Assessment tax return. This is the same annual form lots of people use to declare income that isn’t taxed automatically, like earnings from self-employment.
The deadlines for Self Assessment are far more generous:
- 31st October if you’re brave enough to file a paper tax return.
- 31st January of the following year if you file online (like most of us).
So, if Chloe made her share profit during the 2024-25 tax year (which ends on 5th April 2025), she has until 31st January 2026 to file online and pay. That gives her plenty of breathing room.
This is a super important point: the 60-day rule is only for UK residential property. For everything else, it’s your standard Self Assessment deadlines that count.
What About Reporting a Loss?
But what happens when an investment goes the other way? No one likes making a loss, but there is a silver lining—you can tell HMRC about it. It might feel like admitting defeat, but it's actually a very smart tax move.
When you report a capital loss, you can use it to cancel out any capital gains you’ve made in the same tax year. This directly reduces your tax bill.
Even better, if your losses are bigger than your gains, you don't lose the difference. You can carry forward any unused losses to reduce gains in future years. Think of it as banking a tax-saving voucher to use on a rainy day.
Juggling deadlines and different reporting methods can feel tricky, especially if you have a mix of investments like Chloe. If you want to make sure you're getting it right, our team at Artema is here to help. Get in touch for some friendly, professional guidance.
Smart Strategies to Legally Reduce Your CGT
Paying tax is part of being a grown-up, but let's be honest, nobody enjoys paying more than they have to. Think of it this way: you wouldn't deliberately overpay for a pint at the pub, so why overpay the taxman? The good news is, you don't have to.
There are plenty of smart, completely legal ways to plan your investments and minimise your Capital Gains Tax (CGT) bill. This isn't about sneaky loopholes; it's about using the rules as they were designed to be used. Let's open up your toolkit for savvy tax planning.
Time Your Sales With the Tax Year
One of the simplest yet most effective strategies is to keep an eye on the calendar. Your CGT Annual Exempt Amount—that lovely tax-free bubble—resets every single tax year on 6th April. It’s a classic case of "use it or lose it."
By timing when you sell, you can make this allowance work hard for you. Instead of selling a large chunk of shares with a big gain all at once, you could sell smaller portions across different tax years.
- How it works: Imagine you have an investment with a gain of £5,000. If you sell it all in one go, you'd use up your £3,000 allowance and still have a taxable gain of £2,000.
- A smarter way: You could sell just enough in March to make a gain of £3,000. Then, after the new tax year starts in April, sell the rest to get the remaining £2,000 gain. Both fall within a tax-free allowance, resulting in a £0 tax bill. Genius!
- Who it's best for: This is a fantastic strategy for any long-term investor who has flexibility on when they need to access their cash.
Embrace Tax-Free Investment Wrappers
Why worry about timing sales when you can invest in a place where CGT doesn't even exist? This is where tax-efficient accounts like ISAs and pensions are your superheroes. They are the ultimate shields against capital gains tax on investments.
Any profit you make from investments held inside a Stocks and Shares ISA or a pension (like a SIPP) is completely sheltered from CGT. You can buy and sell as much as you like within these accounts, and you'll never see a tax bill on the growth.
Think of an ISA as a tax-free greenhouse for your investments. Inside, your money can grow freely, protected from the weather of CGT and income tax, letting your portfolio flourish without being trimmed back by the taxman.
For the 2024-25 tax year, you can put up to £20,000 into an ISA. Using this allowance each year is one of the most powerful moves you can make to build your wealth tax-efficiently.
Share the Love (and the Allowance)
If you're married or in a civil partnership, you have a brilliant, government-approved strategy you can use. You can transfer assets between each other without triggering an immediate CGT charge.
This allows you to make full use of both of your individual annual allowances, effectively doubling your household's tax-free potential.
- How it works: Let's say you have shares with a £6,000 gain and have already used your own allowance for the year. You can transfer half of those shares to your spouse. They can then sell their portion, using their own £3,000 allowance to cover the gain.
- The result: The entire £6,000 gain is realised completely tax-free. It’s a perfect example of teamwork making the dream work!
- Who it's best for: This is ideal for couples where one partner may have used their allowance while the other has not, or where one partner pays a lower rate of tax.
Explore Other Tax-Efficient Schemes
Beyond the mainstream options, there are other investment schemes designed by the government to encourage investment in smaller, growing UK companies. These come with some tasty tax advantages, including CGT relief.
Schemes like the Enterprise Investment Scheme (EIS) and Venture Capital Trusts (VCTs) offer attractive tax breaks to compensate for the higher risk. While not for everyone, they can be a powerful addition to a portfolio for more experienced investors. If you're curious, you can learn more about how to invest in Venture Capital Trusts in our detailed guide.
Making smart choices can make a huge difference to your final returns. If you want to create a plan that fits you, our team at Artema is here to help you make the most of your money. Give us a call today for a friendly chat about your financial goals.
Your Capital Gains Questions Answered
Still got a few questions buzzing around? That’s perfectly normal. CGT can feel a bit tangled, so let's clear up some of the most common queries.
What Happens if My Investment Makes a Loss?
Nobody likes to see an investment lose value, but there is a small silver lining. You can—and absolutely should—report any losses to HMRC.
These losses can then be used to cancel out any capital gains you make in the same tax year, which directly shrinks your tax bill. Even better, if you don't have any gains to offset, you can carry that loss forward indefinitely. Think of it as a tax-saving voucher you can use against future profits.
Do I Owe CGT on Inherited Investments?
No, you don't pay any CGT when you first inherit something. The tax clock resets. You get the investment at whatever its market value was on the date of the person's death.
This is called a "stepped-up" cost basis. CGT only comes into play if you later decide to sell that asset for a profit. Your gain is calculated from the value when you got it, not from what the original person paid.
Is Profit from Crypto Subject to CGT in the UK?
Yes, it absolutely is. HMRC sees your Bitcoin or Ethereum as property, not currency.
That means whenever you dispose of crypto—whether you're selling it for cash, trading it for another coin, or even using it to buy a pizza—any profit you make is potentially liable for capital gains tax on investments, just like selling shares.
How Are Gains Inside an ISA or Pension Taxed?
Here’s the best news of all: they aren't! This is the superpower of these accounts. Any gains your investments make inside a Stocks and Shares ISA or a pension are completely shielded from Capital Gains Tax. This makes them incredibly powerful tools for building wealth over the long term.
Working through the details of CGT can feel daunting, but you don't have to figure it all out on your own. The team at Artema Ltd is here to offer clear, friendly advice to help you manage your tax obligations and make the most of your investments. Visit us at https://www.artema.co.uk to see how we can support you.