
Feeling a bit baffled by company tax on dividends? You're not alone. It can seem like a complex world of its own, complete with confusing jargon and scary-looking forms. But don't worry, we're here to break it down.
In simple terms, a dividend is just a share of your company's profits paid out to you, the shareholder, after all the business taxes are sorted. Think of it as your company's way of saying "well done" with a cash bonus, but one that comes with its own special tax rules.
Your Friendly Guide to Company Dividends and Tax
So, you've steered your limited company through a successful year, and there’s a nice pile of profit sitting in the bank. Fantastic news! But how do you get that money into your own pocket without giving HMRC an unnecessarily large slice of the pie? This is where understanding company dividends becomes your superpower.
A dividend is a payment made from post-tax profits. This means your company must first work out its profit for the year and pay Corporation Tax on it. Whatever is left over is then fair game for a dividend payout. It's a two-step tax tango: first, the company pays its tax, and then you personally pay tax on the dividend you receive.
Why Bother with Dividends at All?
You might be wondering, "Why not just pay myself a big salary?" The main reason is tax efficiency. For many company directors, taking a combination of a small salary and larger dividend payments often results in a lower overall tax bill compared to taking the entire amount as salary. This strategy is one of the biggest limited company tax benefits available to business owners.
This guide is designed to be your jargon-free map for navigating the world of dividends. We'll break down the essentials you need to know, including:
- The Dividend Allowance: A handy tax-free amount you can receive each year.
- Dividend Tax Bands: The different rates of tax you’ll pay depending on your total income.
- The Correct Process: How to declare and pay a dividend legally to stay on the right side of the rules.
The key takeaway is this: a dividend isn't just 'taking money' from your business. It's a formal distribution of profit with specific tax implications for both the company and you as an individual shareholder.
Properly managing your company's finances is the foundation of this entire process. Before you can even think about dividends, you need clean, accurate books to calculate your profit. For a deeper dive into getting this right, these practical small business bookkeeping tips are a great starting point.
By the end of this guide, you’ll have a much clearer picture of how company tax on dividends works, helping you make smarter decisions about your income. Ready to get started? Let's dive in. And if you have any questions along the way, our team at Artema is always here to help.
How to Properly Pay Yourself a Dividend
So, your company has turned a profit after paying its Corporation Tax. Fantastic! Now, how do you get that money from the company’s bank account into your own pocket without giving HMRC a reason to start asking questions? The answer is by declaring and paying a dividend, and thankfully, it’s not as complicated as it might sound.
Think of a dividend as a formal, well-documented bonus you give yourself from the company’s leftover profits. For most small business owners, you’re not just the director; you’re also the main shareholder. This means you’re both the one authorising the payment and the one receiving it. It might feel a bit like writing a permission slip for yourself, but the paperwork is absolutely crucial.
Let’s follow the story of a fictional founder, Priya, to see how it’s done. Priya runs a successful graphic design agency and has £20,000 in retained profits she wants to pay herself. She can’t just transfer the money and call it a day. She needs to follow a simple but non-negotiable process to keep everything above board.
The Essential Steps to a Legal Dividend
First, Priya needs to be certain her company actually has enough retained profits to cover the dividend. This is the accumulated profit from this year and previous years after Corporation Tax has been sorted. You can only pay dividends from these profits—not from the company’s initial capital or a bank loan.
Next, she holds a board meeting to declare the dividend. Yes, even if the "board" is just her and her cat, she needs to formally document this decision.
A common mistake is thinking this is all just corporate fluff. In reality, creating a paper trail is your best defence. It proves the dividend was declared correctly from legitimate profits, which is exactly what HMRC wants to see.
This process ensures the dividend is legal and properly recorded, which is what keeps you compliant.
This simple flow shows exactly how profits become dividends.
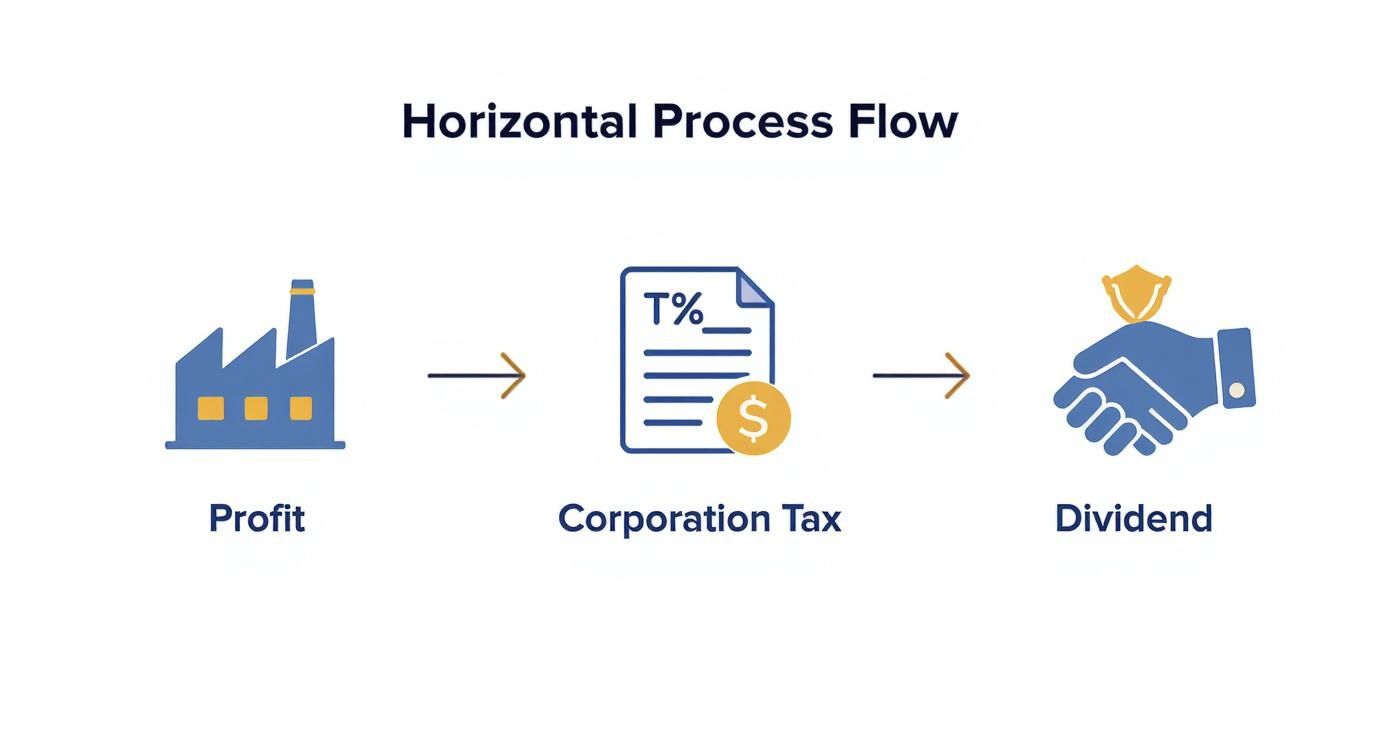
The key takeaway here is that dividends are paid from what's left after the company has settled its tax bill, not before.
Creating the Dividend Voucher
After the "meeting," Priya creates two vital documents:
- Board Meeting Minutes: This is just a written record of the decision. It should state who was present (Priya and Mittens the cat, perhaps), the dividend amount, and the date it was approved.
- A Dividend Voucher: Think of this as a payslip for your dividend. It’s a legal document that must be created for each payment and given to every shareholder (even if that’s just you).
The dividend voucher must include specific information to be valid:
- The company’s name and registered number.
- The payment date.
- The name and address of the shareholder receiving the money.
- The total number of shares that shareholder owns.
- The dividend payable per share.
- The total dividend amount.
Priya creates a voucher with all these details, signs it as the director, and keeps one copy for her company records and another for her personal tax file. Now she can finally transfer the £20,000 to her personal account. Simple!
What Is an Illegal Dividend?
An "illegal dividend" sounds dramatic, but it’s usually just a dividend paid when the company didn’t have enough retained profits to cover it. If you accidentally pay yourself more than the company can afford, HMRC can demand you pay it back. This is why checking your accounts before declaring a dividend is so important.
The process of paying yourself from your limited company involves more than just dividends. For a complete overview of combining salary and dividends effectively, you can learn more about how to pay yourself from a limited company in our detailed guide.
Getting this process right ensures you stay compliant and avoid any future trouble. If you’re ever unsure about your company’s profit position or the paperwork involved, it's always best to ask for help. Get in touch with our team at Artema, and we can make sure your dividend payments are handled perfectly every time.
The Two Taxes on Your Company's Profit
When your limited company turns a profit, it's a fantastic feeling. But before you move that cash into your personal account, you need to understand how HMRC views that money. They see it in two separate stages, and each one comes with its own tax bill. It's not a tax double-whammy, just a two-step process.
Think of it like a journey. First, the company pays its tax. Then, you personally pay tax on whatever you decide to take out. This clean separation is fundamental to getting your head around how company and dividend taxes work together.
Level One: Corporation Tax
The first hurdle is Corporation Tax. This is the tax your limited company pays directly to HMRC on its taxable profits. That includes profit from your day-to-day trading, any investments the company has made, and gains from selling assets for more than they cost.
To figure this out, your company calculates its total profit, subtracts all the allowable business expenses (things like salaries, rent, and software subscriptions), and then pays Corporation Tax on the figure that’s left. This is the company’s responsibility, paid straight from the company's bank account.
The rates do change, but for the 2024/25 tax year, the main rate of Corporation Tax is 25%. There’s good news for smaller businesses, though. If your company’s profits are below £50,000, you’ll pay a much lower rate of 19%. For profits sitting between £50,000 and £250,000, a system called 'marginal relief' comes into play, which smoothly brings the rate up towards the full 25%.
Think of Corporation Tax as the price of admission. Before any profits can be shared with the owners (that's you!), the company must settle up with the government. Once that's done, you've cleared level one.
After paying this tax, you're left with what's known as "post-tax profit." This is the pot of money from which you can legally pay dividends.
Level Two: Personal Dividend Tax
Once the company has paid its Corporation Tax, the profits left over can be distributed to you and any other shareholders in the form of dividends. Now, the spotlight is on you. Any dividends you receive are considered part of your personal income, and you might need to pay tax on them.
This brings us to the second tax in the journey: Dividend Tax.
This is a completely separate tax that you, as an individual, are responsible for. It’s handled through your annual Self Assessment tax return. How much you pay depends on your total income from every source (salary, rental income, etc.) and which personal tax band you fall into. The key takeaway here is that Dividend Tax rates are lower than the income tax rates you'd pay on a salary.
This is where the real tax planning comes in. Here's why this structure is so popular with business owners:
- Tax Efficiency: By paying yourself a small, tax-efficient salary and taking the rest of your income as dividends, you can often significantly reduce your overall tax bill. Your salary is an allowable expense for the company (which lowers its Corporation Tax bill), while dividends are taxed at more favourable personal rates.
- No National Insurance: This is a big one. Unlike a salary, dividends are not subject to National Insurance Contributions – not for you, and not for your company. This alone can result in savings of thousands of pounds every year. Who doesn't love saving money?
This combination of a small salary and larger dividends is the cornerstone of tax planning for most directors of small UK companies. It's the main reason dividends are such an attractive way to take money out of a profitable business.
By keeping the company’s tax separate from your personal tax, the system opens the door to smart, efficient planning. Your company pays its Corporation Tax, and then you pay a lower personal tax on the dividends you draw. It’s a structure that rewards you for your hard-earned success.
Figuring out the perfect balance for your specific situation can be tricky. If you want to be sure you're taking profits out of your business in the most tax-efficient way possible, get in touch with our team at Artema. We can help you build a strategy that saves you money and keeps you fully compliant.
Maximising Your Tax-Free Allowances
Now for the fun part—making the tax system work for you. Before we even get to the specific tax rates, it’s vital to get your head around the tax-free allowances. Think of these as a head start from HMRC, letting you earn a certain amount each year before paying a single penny in tax.
For company directors, there are two key allowances you absolutely need to know about. Getting a grip on how these work together is the first step to truly efficient tax planning.
Your Two Tax-Free Shields
First up is the one most people have heard of: the Personal Allowance. This is the amount of income you can earn from almost any source—salary, rent, you name it—completely tax-free. For the 2024/25 tax year, the standard Personal Allowance is £12,570.
The second is your special, tax-free dividend bonus, officially called the Dividend Allowance. This is an extra allowance specifically for dividend income. For the 2024/25 tax year, this allowance is £500. It's much smaller, but it’s a dedicated tax-free zone just for your dividends.
The magic happens when you use these allowances together. A common strategy is to pay yourself a salary right up to the Personal Allowance, and then use your Dividend Allowance on top of that. This gives you a significant chunk of income completely free of tax.
This simple combination forms the bedrock of smart profit extraction for thousands of business owners across the UK.
The Income Bucket Analogy
So, how do the tax bands fit into all this? The easiest way to picture it is to imagine your total annual income is like water filling up a series of buckets, one after the other. Each bucket is a different tax band, and once one is full, the water spills over into the next.
Crucially, your income fills these buckets in a specific order:
- Non-savings income first: This is your salary. It starts filling up your Personal Allowance bucket.
- Savings income next: Any interest from savings would go in here.
- Dividends last: Your dividend income is the final thing to be poured in, filling up any remaining space in the lower buckets before spilling into the higher ones.
This order is critical. It means your salary uses up your Personal Allowance first, which then dictates which tax band your dividend income falls into.
A Real-World Example in Action
Let's put this all together with a clear, worked example. Meet David, the sole director of his own consulting company. He wants to pay himself £50,000 this year in the most tax-efficient way possible. His accountant suggests a small salary and taking the rest in dividends.
- Total Desired Income: £50,000
- Strategy: Pay a salary of £12,570 and take the remaining £37,430 as dividends.
Here’s a step-by-step look at how David's tax is calculated.
Worked Example for a Company Director
Follow this example to see how salary, dividends, allowances, and tax bands work together in a real-world scenario.
| Income Source or Allowance | Amount | Tax Calculation | Tax Due |
|---|---|---|---|
| Salary | £12,570 | Fully covered by £12,570 Personal Allowance | £0 |
| Dividend Allowance | £500 | First £500 of dividends are tax-free | £0 |
| Remaining Dividends | £36,930 | Taxed at the basic rate (8.75%) | £36,930 x 8.75% = £3,231.38 |
| Total Tax Due | £3,231.38 |
Let's break that down.
-
Salary: David’s salary of £12,570 perfectly uses up his Personal Allowance of the same amount. This means he pays £0 Income Tax on his salary. (He will have some National Insurance to consider, but for simplicity, we'll focus on income and dividend tax here).
-
Dividends: David receives £37,430 in dividends. The first £500 are covered by his tax-free Dividend Allowance, so no tax there. This leaves £36,930 (£37,430 – £500) of his dividends to be taxed.
-
The Final Calculation: Because his salary has already used up the tax-free personal allowance, this entire remaining dividend amount falls into the basic rate tax band. The dividend tax rate for basic rate taxpayers is 8.75%. So, the tax is £36,930 x 8.75% = £3,231.38.
From a total income of £50,000, David’s personal tax bill on his dividends is just £3,231.38. This is significantly less than if he’d taken the entire £50,000 as salary, where he would have faced much higher income tax rates and hefty National Insurance contributions.
This example clearly shows how combining salary and dividends, while making full use of your allowances, is a powerful way to manage your tax bill. It gives you control and helps you keep more of the profits you've worked so hard to earn.
Feeling a bit overwhelmed by the numbers? You're not alone. Figuring out the optimal salary and dividend mix for your unique situation is what we do best. Contact Artema today, and let's have a friendly chat about building a tax plan that works for you.
How Dividend Tax Rules Have Changed
The dividend tax system we know today hasn't just appeared out of thin air. Like a classic TV show that gets a modern reboot, the rules have gone through some major rewrites over the years. Understanding a bit of this backstory isn’t just a history lesson; it helps explain why we have the allowances and tax rates we do today.
It often feels like tax rules are designed to be as confusing as possible, but there's usually a logic behind the madness. The current system is the result of decades of tweaks as governments try to balance collecting revenue with encouraging investment and keeping business owners on side. It's a tricky act to pull off, and it has led to some dramatic changes.
The biggest plot twist in the story of UK dividend tax happened way back in 1999. Before then, the system was a completely different beast, built around something called Advance Corporation Tax, or ACT.
The Old World of Reclaimable Tax Credits
Before 1999, when a company paid a dividend, it also had to pay a slice of tax—ACT—directly to HMRC at the same time. Shareholders then received this dividend with a "tax credit" attached. Think of it as getting a little voucher from the taxman with your dividend payment.
For many, this was brilliant news. Non-taxpayers, like pension funds or individuals on very low incomes, could actually cash this voucher in and reclaim the tax from HMRC. This was a huge deal, especially for pension funds, which relied on this reclaimable tax to boost their returns.
This old system was a game-changer for certain investors. Imagine a pension fund getting a £1.2 million dividend payment; under the old ACT rules, they could reclaim a whopping £400,000 in tax. This was a massive source of income that many funds had come to depend on.
However, in April 1999, the government decided to scrap ACT. The abolition of Advance Corporation Tax fundamentally transformed how UK dividends were taxed, and the change sent shockwaves through the financial world. The reclaimable tax credit was slashed to just 10% and was no longer payable, meaning pension funds and non-taxpayers lost a significant income stream almost overnight. You can dive deeper into this landmark change by reading the history of UK corporation tax.
The Modern Era and the Dividend Allowance
Fast forward to more recent times, and the changes have kept coming. Another significant shift occurred in 2016 with the introduction of the Dividend Allowance. This was a brand-new concept designed to simplify the system for smaller investors and business owners.
Instead of the complicated tax credit system, the government introduced a straightforward, tax-free allowance just for dividends. When it first launched, it was a generous £5,000. This meant you could receive the first £5,000 of dividends each year without paying a penny of tax, regardless of your other income.
Since then, this allowance has been chipped away at. It's a clear reminder that when it comes to company tax dividends, the rules are always evolving. Staying on top of these changes is absolutely essential for effective tax planning.
Understanding this journey—from the days of ACT to the modern Dividend Allowance—gives you valuable context. It shows that the system is constantly being adjusted, and what works today might be different tomorrow. That’s why getting professional, up-to-date advice is so important.
If you have questions about how the current rules affect your business, book a call with the Artema team. We're here to help you make sense of it all and plan for the future.
Tax-Efficient Dividend Planning Strategies
Alright, you've got the hang of the rules and the history behind them. Now it's time to get strategic. Smart dividend planning isn't about finding secret loopholes; it's about using the established rules to your advantage, making sure you can extract your hard-earned profits as efficiently as possible.
Think of it like packing a suitcase for a holiday. You could just chuck everything in and hope for the best, or you could plan a little, fold everything neatly, and suddenly find you’ve got loads more space. The same idea applies to your company tax dividends—a bit of foresight goes a very long way.
The whole point is to keep more of what you earn, rather than sending an unnecessarily large slice over to HMRC. With a few practical strategies, you can make a real difference to your take-home pay.
The Classic Salary and Dividend Mix
For most UK company directors, the cornerstone of tax planning is the tried-and-tested combination of a small salary and larger dividends. It's popular for a very good reason: it just works. By paying yourself a small salary, you stay on the right side of the system, while taking the bulk of your earnings as dividends keeps your overall tax and National Insurance bill much lower.
The "sweet spot" for your salary can change from year to year, but it’s typically set around the Personal Allowance threshold or the point where National Insurance contributions kick in.
- Small Salary: This part of your income is an allowable business expense, which shaves a bit off your company's Corporation Tax bill. It also means you’re making National Insurance contributions, which count towards your state pension down the line.
- Larger Dividends: The rest of your income comes from dividends. These aren't subject to National Insurance at all and are taxed at lower personal rates than a salary would be.
This simple one-two punch is often the most effective strategy a small business owner can use.
Timing is Everything
Ever tried booking a last-minute flight in August? The price is outrageous. But book that same flight in advance for a Tuesday in November, and you’ll save a fortune. Timing your dividend payments works in a similar way. Hurriedly taking a large dividend at the wrong moment can be a very costly mistake.
A common pitfall we see is directors declaring a large dividend just before the tax year ends on 5th April, without first checking their total income for the year. Doing this can easily push you into a higher tax bracket, meaning a much bigger chunk of that dividend goes straight to the taxman.
A savvy director plans ahead. By reviewing your income and profits quarterly, you can time your dividend payments to make full use of your allowances without tripping into a higher tax band. It’s all about smoothing out your income, not creating last-minute spikes.
Smart timing shows just how sensitive people are to tax changes. After the government announced higher dividend tax rates in 2015, analysis showed company directors brought forward a staggering £10.7 billion in dividend payments to beat the deadline—about 40% more than predicted.
Share the Love: Structuring for Co-owned Businesses
If you run your business with a spouse or partner, you open up even more strategic options. By properly structuring your company's shareholdings, you can split dividend income between you. For instance, if you and your spouse are both shareholders, you can each use your own set of tax-free allowances.
This effectively doubles your tax-planning power, allowing you to use two Personal Allowances and two Dividend Allowances. For those with significant investments and company holdings, navigating dividend tax can get complex; specialised solutions for high net worth individuals can offer tailored advice on optimising dividend income and overall tax liabilities.
And don't forget other ways to take profits out of the business. Making payments into a pension scheme directly from your limited company, for example, is a highly effective, tax-efficient strategy. You can find out more in our guide on https://www.artema.co.uk/limited-company-pension-contributions/.
These strategies are powerful, but they aren't one-size-fits-all. Your personal situation, other income, and your business structure all play a huge part. It's always best to get professional advice before making any big decisions.
Your Dividend Questions Answered
When you get into the nitty-gritty of director's pay, dividends can feel a bit like a puzzle. To help put the pieces together, here are a few of the most common questions we get from business owners trying to get it right.
Can I Pay a Dividend Whenever I Want?
In theory, yes, but only if your company has enough retained profits to cover it. In practice, however, it’s much smarter to plan your dividend payments.
Most directors declare them quarterly or annually. This gives you a much better handle on your cash flow and stops you from accidentally paying out more than the company has earned – an ‘illegal dividend’ that can cause serious headaches down the line. Think of it less like a constant raid on the biscuit tin and more like a planned treat.
Do I Pay National Insurance on Dividends?
Nope! And honestly, this is one of their biggest advantages. Unlike a salary, dividends aren't subject to National Insurance contributions – not for you, and not for your company. This is the main reason why the classic salary-and-dividend mix is such a popular strategy for running a tax-efficient business.
It’s useful to remember that a dividend is your reward for being a shareholder—an owner of the business. It isn't a payment for the work you do as a director. That's what your salary is for, and it's why the two are treated so differently for tax.
What if My Only Income Is Dividends?
Even if dividends are your sole source of income, the tax system works in much the same way. You’ll still get your £12,570 Personal Allowance and your £500 Dividend Allowance to use first. Any dividend income you receive above these allowances will then be taxed at the relevant rates, starting at the basic rate of 8.75%.
Feeling a bit clearer, but still have questions about how this all applies to your company? When it comes to dividends and tax, a quick chat can make all the difference. The team here at Artema Ltd can give you straightforward, expert advice to make sure you’re paying yourself in the smartest way possible. Get in touch with us today for a no-obligation consultation.