
Fed up with the 9-to-5 grind and dreaming of a bit more freedom? When you contract through a limited company, you're essentially creating a separate legal identity just for your business. Think of it as giving your work life its own superhero cape. It’s the go-to choice for UK contractors, and for good reason—it draws a clean, protective line between your personal piggy bank and your professional hustle.
Ready To Become Your Own Boss?
So, the idea of contracting has caught your eye. Fantastic! The thought of being your own boss is thrilling, and for many people in your shoes, setting up a limited company is the smartest first move. Don't think of it as building a huge corporate empire (unless you want to, of course!). See it more as putting a professional, tax-savvy framework around your freelance career.
This isn't some niche, secret club, either. It’s become the default way of doing business in the UK. Recent ONS figures show that companies with just a single employee now make up a massive 44.0% of all limited companies, with professional and technical wizards like you leading the charge.
Why This Guide Is for You
Think of this guide as your friendly, no-nonsense map to figuring out what contracting through a limited company is really all about. We'll walk you through the brilliant perks (hello, tax savings!) and be upfront about the not-so-exciting admin that tags along for the ride. We’ll even demystify the dreaded IR35 without making your brain hurt.
Our aim is simple: to give you a clear, honest picture so you can decide if this is the right move for you. We'll be covering:
- The juicy benefits and the potential pitfalls.
- A step-by-step on how to get your company set up (it's easier than assembling IKEA furniture, we promise).
- Everything you need to know about tax and staying on the right side of the law.
- A peek at your day-to-day admin duties.
A great way to think of a limited company is like a protective financial bubble. If your business ever hits a bump in the road, your personal stuff—like your home and savings—are generally safe. That’s a world away from being a sole trader, where you and your business are legally seen as one and the same.
Making the Right Choice
Picking a business structure is a huge decision, and it’s not just about crunching the numbers. It’s about finding what fits your career goals and how much paperwork you're willing to put up with. Before you dive in, it's worth getting a handle on the main differences between your options. For a proper deep dive, have a read of our guide comparing a sole trader vs limited company.
Ready to see if becoming a company director is your next career adventure? Let’s jump in.
So, you're wondering if contracting through a limited company is the golden ticket everyone says it is. Is it really the key to a fatter wallet and a better lifestyle?
Honestly, it’s a bit of a mixed bag. There are some fantastic perks that can make it incredibly rewarding, but they come with a side of paperwork you simply can't ignore.
Let's start with the good stuff—the reasons so many contractors go down this route in the first place.
The Upside: More Money, More Protection
One of the biggest draws is tax efficiency. When you're the director of your own company, you have a lot more flexibility in how you get paid. Instead of taking everything as a salary (which gets hit hard by National Insurance), you can opt for a small, tax-friendly salary and take the rest as dividends.
This clever combo often means you keep more of your hard-earned cash at the end of the day. It’s a core strategy for maximising your take-home pay, and we've put together a handy guide that explains exactly how to pay yourself from a limited company in more detail.
Then there’s the professional shield known as limited liability. This is a huge deal. It means your company is a completely separate legal entity from you. If the business ever ran into financial trouble, your personal assets—like your house, car, and savings—are protected. Think of it as a financial firewall between your work life and your home life.
This legal separation is the main reason many contractors choose to incorporate. It provides a level of security and peace of mind that being a sole trader simply can't match, allowing you to take calculated business risks without betting the house—literally.
The Downside: The Admin You Can't Avoid
Now for the other side of the coin: the paperwork. Being a company director isn't just a fancy title for your LinkedIn profile; it comes with real, legal responsibilities. You're not just a contractor anymore; you're running a proper business, and both HMRC and Companies House expect you to act like it.
This means you're on the hook for a few key things:
- Maintaining Accurate Records: You’ll need to keep on top of all your invoices, receipts, and bank statements. Good bookkeeping isn't just a nice-to-have; it's a legal requirement.
- Filing Official Documents: Every year, you’ll need to file a Confirmation Statement and your company accounts. Miss these deadlines, and you could be looking at some rather unfriendly fines.
- Managing Company Finances: All company money must go through a dedicated business bank account. You can't just use your personal account for client payments or business expenses. No dipping into the company cookie jar for your weekly shop!
It might sound like a lot, and it can be. But with a bit of organisation (and maybe a good accountant whispering sweet nothings in your ear), it's completely manageable. The key is knowing what’s expected of you from day one.
Limited Company vs Umbrella vs Sole Trader: A Quick Comparison
To help put it all into perspective, it's useful to see how operating as a limited company stacks up against the other popular options for contractors. Each has its own place, depending on what you value most.
| Feature | Limited Company | Umbrella Company | Sole Trader |
|---|---|---|---|
| Tax Efficiency | High. Potential for significant savings via salary/dividend mix. | Low. You are taxed as an employee (PAYE). | Medium. Less flexible than a limited company. |
| Admin Effort | High. You are responsible for all company admin and filings. | Very Low. The umbrella company handles it all. | Medium. Less complex than a company, but still requires self-assessment. |
| Legal Protection | Excellent. Your personal assets are legally separate. | Excellent. You're an employee, so you're protected. | None. You and the business are legally the same entity. |
Ultimately, choosing to set up a limited company is a trade-off. You're swapping the simplicity of being an employee or sole trader for greater control, higher earning potential, and robust legal protection. For many contractors, the extra admin is a small price to pay for those significant financial benefits and the peace of mind that comes with them.
Building Your Company From The Ground Up
So, you’re ready to make it official and bring your limited company to life? It might sound a bit daunting, but setting up is surprisingly straightforward. Think of it less like navigating a bureaucratic maze and more like creating your own superhero origin story.
Let's walk through the key steps, one by one, without any of the confusing legal speak.
Choosing The Perfect Company Name
First up, the fun part: picking a name! This is your business's identity, so choose something that sounds professional and is easy for clients to remember.
There are a few ground rules, though. Your name can't be too similar to one already on the Companies House register. It also can’t be offensive or suggest a connection to government bodies unless you have special permission. A quick search on the Companies House website will tell you if your dream name is available.
Appointing Your Directors and Shareholders
Next, you need to decide who’s in charge. For most contractors just starting out, this is the easy bit. You’ll likely be the sole director (the person running the company) and the sole shareholder (the person who owns it).
A director handles the day-to-day management and makes sure the company meets its legal duties. A shareholder owns the company through shares and is entitled to a cut of the profits, usually paid as dividends. Don't worry, you can absolutely wear both hats at once!
Think of it like this: as the director, you're the captain of the ship, steering it through client projects and deadlines. As the shareholder, you're the one who owns the ship and gets to enjoy the treasure (profits) it brings in.
Picking Your Registered Office
Every limited company needs an official address, known as the registered office. This is where all formal letters from Companies House and HMRC will be sent, and it must be a physical address in the UK.
Crucially, this address is publicly available online. If you work from home and don’t fancy your personal address being on the public record for all to see, using a virtual office address or your accountant’s address is a very smart move. It keeps your home life private and adds a professional touch.
This flow chart gives you a bird's-eye view of the typical contractor journey, from weighing up the perks to managing the ongoing paperwork.
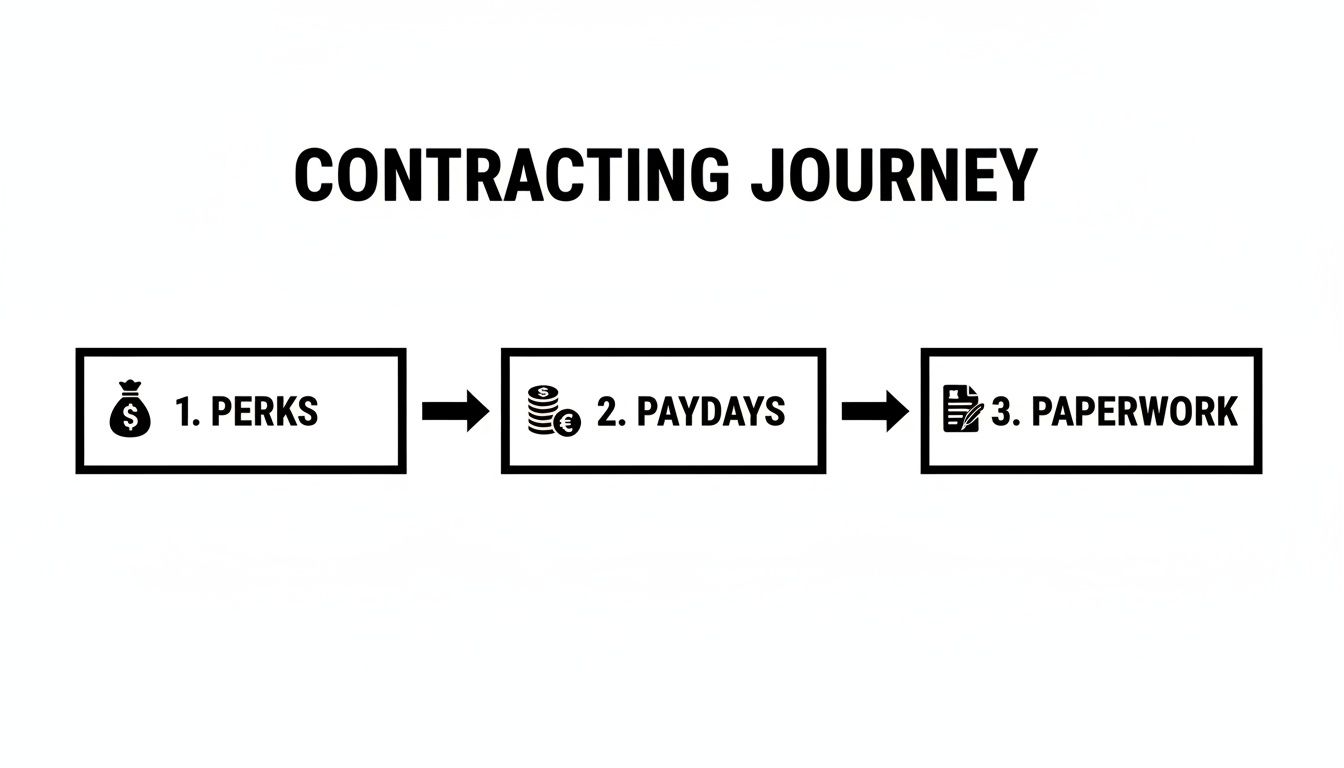
As you can see, the path involves balancing the financial rewards with the admin duties that come with being your own boss.
The Official Setup With Companies House
With your name, director, and address sorted, it’s time to incorporate. This is simply the formal process of registering your company.
You'll need to provide a few key details about your company, its directors, and its shareholders. You'll also come across a couple of standard documents:
- Memorandum of Association: A simple statement from the first shareholders agreeing to form the company.
- Articles of Association: These are the rules for running the company, like how decisions are made. Most contractors just use the standard 'Model Articles'. No need to reinvent the wheel here!
The setup process is fast and can often be done online in under 24 hours for a small fee. While starting is easy, it's worth noting that sustained success takes commitment. In the first quarter of a recent year, Companies House recorded 211,112 new incorporations but also 190,147 dissolutions. You can read more about these UK business trends on GOV.UK.
Your First Tasks After Incorporation
Congratulations, you’re officially a company director! Before you pop the champagne, there are a couple of immediate jobs to tick off the list.
First, open a business bank account. This is non-negotiable. All your company’s income must go into this account, and all business expenses paid from it. Keeping your business and personal finances separate is a golden rule of contracting and will save you endless headaches.
Next, you need to let HMRC know you exist. You must register your new company for Corporation Tax within three months of starting to trade. Getting these first steps right lays a solid foundation for a stress-free and successful contracting career. Feeling overwhelmed? Don't be—a good accountant can handle most of this for you.
Right, let's talk about the bit that often makes new contractors a bit twitchy: tax.
It sounds complicated, but the basics are actually quite logical once you get the hang of it. Think of it less as a scary monster under the bed and more as a set of rules you need to play by to keep your business healthy and your finances in great shape.
The main reason contracting through a limited company is so popular comes down to one thing: tax efficiency. You have far more control over how and when you take money out of your business, which can often lead to keeping more of what you earn. But with great power comes… well, the responsibility to pay the right taxes.
Your Main Tax Responsibilities
As a company director, you'll be juggling a few different types of tax. Don't worry, you don't need to become an expert overnight, but knowing what's what is the first step to staying on the right side of HMRC.
- Corporation Tax: This is the tax your company pays on its profits—the money left over after you've paid all your business expenses and your own salary. It’s a key part of your annual financial duties.
- VAT (Value Added Tax): If your company's turnover hits a certain threshold (currently £90,000 per year), you’ll need to register for VAT. This means you charge VAT on your invoices and pay it to HMRC, often claiming back the VAT you’ve paid on business purchases.
- National Insurance: This comes in two flavours. Your company pays Employer’s National Insurance on your salary, and you pay Employee’s National Insurance from your salary. This is a big reason why contractors often take a smaller salary and larger dividends.
The core strategy here is usually quite simple: pay yourself a low salary that sits below the main tax thresholds, and then take the rest of your income as dividends from the company’s post-tax profits. This method is perfectly legal and can significantly reduce the amount of National Insurance you both pay, boosting your take-home pay.
This is a major source of revenue for the government; in fact, HMRC reported that total corporate tax receipts reached £97.2 billion in a recent fiscal year, showing just how much limited companies contribute. You can discover more insights about UK corporate tax statistics on taxathand.com.
The Big One: Understanding IR35
Now for the elephant in the room: IR35. You’ve probably heard contractors whispering about it in hushed, fearful tones. But it's not as terrifying as it sounds once you understand what it’s trying to do.
At its heart, IR35 is a set of rules designed to spot 'disguised employees'. HMRC wants to make sure that contractors who are essentially doing the job of a permanent employee are paying the same level of tax as one.
Imagine you’re a taxi driver. If you own your own cab, decide your own hours, and can send another qualified driver in your place if you’re sick, you are genuinely self-employed. But if a company gives you a car, tells you when and where to work, and insists only you can drive it, you look a lot more like an employee. That’s the IR35 test in a nutshell.
If your contract and working practices are deemed 'outside IR35', you’re operating as a genuine business. You can continue to pay yourself tax-efficiently with a mix of salary and dividends.
If you’re caught 'inside IR35', HMRC sees you as an employee for tax purposes. This means your client must deduct tax and National Insurance from your fees before they even reach your company, wiping out most of the financial benefits of being a limited company contractor.
For a deeper dive into how these rules work, check out our guide on the off-payroll working rules known as IR35.
Staying on the Right Side of IR35
So, how do you prove you're a genuine business and not a disguised employee? HMRC looks at several key factors in your contract and how you actually work day-to-day.
- Substitution: Can you send someone else with the right skills to do the job for you? A true business can, while an employee cannot. This is a powerful indicator of being outside IR35.
- Control: How much say does your client have over how you do your work? If they control your hours, location, and methods, it points towards employment. If you have autonomy, you look more like a business.
- Mutuality of Obligation (MOO): Is the client obliged to offer you more work after the contract ends, and are you obliged to accept it? A genuine contract is for a specific project with a clear end date, not an ongoing, open-ended arrangement.
Getting your IR35 status right is critical. An incorrect assessment can lead to a hefty, unexpected tax bill down the line. This is one area where getting professional advice isn't just helpful—it's your best defence. An expert can review your contracts and working practices to give you peace of mind and ensure you’re set up for success.
Managing Your Day-To-Day Company Admin
Your company is officially live—fantastic! But now the real work begins. Running the day-to-day operations of your limited company might sound like a chore, but getting organised is the secret sauce that keeps everything ticking over smoothly.
Being organised isn't just about having tidy folders; it's what separates the thriving contractors from the ones constantly putting out fires. Let's break down the admin tasks that will quickly become part of your routine.
Good Bookkeeping: Your Secret Weapon
First up, bookkeeping. This is the non-negotiable foundation of your company's finances. In simple terms, it's just the process of recording all the money coming in and going out of your business. Get this right from day one, and everything else becomes ten times easier.
Good bookkeeping shows you exactly how your business is performing, helps you plan for the future, and makes filing your taxes a breeze instead of a last-minute nightmare. It’s also how you track your business expenses, which is absolutely vital for reducing your Corporation Tax bill.
Think of bookkeeping as the health tracker for your business. It tells you its vital signs—cash flow, profit, and expenses—so you can make smart decisions and keep it in peak condition. Ignoring it is like never going for a check-up; you won't spot problems until they become serious.
Claiming Expenses: What You Need to Know
One of the biggest perks of being a limited company contractor is the ability to claim a wide range of business expenses. Any cost that is "wholly and exclusively" for your business can be deducted from your company's profit before tax is calculated.
So, what can you claim? The list is longer than you might think:
- Office Equipment: That new laptop, monitor, and comfy office chair are all legitimate expenses.
- Software & Subscriptions: Your accounting software, professional tools, and industry subscriptions all count.
- Professional Development: Courses or training to improve your skills are a fantastic, claimable investment in yourself.
- Travel Costs: Journeys to client sites (that aren't your regular commute) can be claimed.
- Accountancy Fees: Yes, the cost of hiring an accountant to help you with all this is tax-deductible!
The golden rule? Keep every single receipt. Whether it’s a digital invoice or a paper slip, you need proof for every expense you claim.
Juggling Deadlines and Payments
Being a company director means you have a few key dates to circle on your calendar. Missing these can result in automatic fines from HMRC and Companies House, so it really pays to be prepared.
Alongside filing your annual accounts and tax returns, you'll need to manage your own pay. This usually involves running a monthly payroll for your small salary and documenting any dividends you take from the company’s profits. Each dividend payment needs a formal paper trail, including meeting minutes and a dividend voucher.
Of course, effective daily operations are about more than just compliance; they're the heart of a successful contracting business. This includes everything from handling client work efficiently to growing your business. For those looking to sharpen their operational skills, there's a great resource on mastering project management for freelancers that can help you stay on track.
It might sound like a lot to juggle, but this is precisely where professional help becomes invaluable. A specialist contractor accountant doesn't just crunch the numbers at year-end; they can manage your payroll, remind you of deadlines, and ensure your bookkeeping is spot on. They are less of a cost and more of an investment in your sanity and success.
Feeling like you could use an expert to handle the admin while you focus on your contracts? Let's have a chat about how we can make your life easier.
Your Contractor Success Checklist
Right, let’s pull all of this together. You’ve weighed up the pros and cons, stared down the paperwork, and even survived the dreaded IR35 chat. Now it's time to turn all that knowledge into action.
Think of this as your pre-flight check before you take off. It’s a simple list of the key steps we’ve covered, designed to make sure you have a smooth and successful launch into the world of contracting.
Your Step-by-Step Launch Sequence
Ready to make it official? Here are the essential tasks to tick off as you get going. This isn't just a to-do list; it’s the bedrock of your new contracting career.
- Finalise Your Company Name: Pick a professional name that’s free on the Companies House register. No pressure, but it's going to be on everything!
- Appoint Directors: Officially name yourself as the director (and, most likely, the sole shareholder). Welcome to the corner office.
- Incorporate with Companies House: This is the moment your business is truly born. Make it official by registering your company.
- Open a Business Bank Account: This is a golden rule. You must keep your business and personal finances completely separate from day one.
- Register for Taxes: Let HMRC know you exist by registering for Corporation Tax. It’s always best to stay on their good side.
- Get Clear on IR35: Assess your first contract to figure out your IR35 status. Don’t just guess on this one—it’s far too important to get wrong.
- Set Up Your Bookkeeping: Choose your weapon, whether it’s simple software or a spreadsheet, and start tracking every penny immediately.
- Calendar Your Filing Dates: Pop your key deadlines for accounts and tax returns into your calendar to avoid any last-minute panic.
Following these steps is like having a map for your first big adventure. But even the best explorers need a guide. While this checklist gives you the route, a specialist accountant is your expert navigator, helping you sidestep pitfalls and find the smartest path forward.
You Don't Have to Do It Alone
While you absolutely can manage all of this yourself, the real question is, should you? Juggling client work, finding new contracts, and handling all the company admin is a serious balancing act. Trying to become a tax expert overnight is a recipe for stress, not to mention costly mistakes.
Bringing a specialist contractor accountant on board from the very beginning is one of the smartest business decisions you can make. They’ll make sure you’re set up correctly, stay compliant, and operate in the most tax-efficient way possible, freeing you up to do what you do best.
Ready to start your contracting journey with confidence? Get in touch with Artema today, and let’s make sure you’re set up for success right from the start.
Frequently Asked Questions
It's completely normal to have a few questions buzzing around. In fact, asking them is the smartest way to start your journey as a limited company contractor. Here are some of the most common ones we get asked.
What's The Real Cost of Running a Limited Company?
Think of it in two main parts. First up is the one-off setup fee to get your company registered at Companies House. This is surprisingly low, often under £20. It’s cheaper than a decent Friday night takeaway!
The more significant cost is the ongoing accounting. A good contractor accountant will likely charge somewhere between £80 to £150+ per month. While you could try to do it all yourself, this fee buys you something invaluable: peace of mind. It also ensures you're as tax-efficient as possible and saves you from a world of admin headaches.
How Do I Get a Mortgage as a Contractor?
Getting a mortgage is absolutely doable, but lenders will look at your finances a little differently. Instead of just focusing on a PAYE salary, they'll usually assess your income based on your daily rate, or a combination of your salary and dividends.
The key is preparation. Most lenders will want to see at least one to two years of company accounts and a solid track record of consistent earnings. Having your financial documents perfectly organised by an accountant makes you look like a much safer bet to them.
What Business Insurance is Essential?
This is one area you really can't afford to skip. There are two main types of insurance that you’ll almost certainly need:
- Professional Indemnity Insurance: This has your back if a client claims your work was negligent or ended up costing them money.
- Public Liability Insurance: This protects you if you accidentally cause an injury or damage property while working at a client's site.
Don't be surprised if your client's contract makes having these policies a mandatory requirement before you can even set foot in the door.
When Should I Switch From Sole Trader?
The usual trigger point is your income level. Once you start earning over the £40,000 to £50,000 a year mark, the tax savings of operating as a limited company often become too good to ignore.
It’s that tipping point where the extra bit of admin is easily outweighed by the extra cash staying in your pocket.
Navigating all these questions is much easier with an expert in your corner. If you're ready to make your contracting journey a success, the team at Artema Ltd is here to help. Get in touch with us today for a friendly, no-obligation chat.