
So, you’re thinking about becoming a contractor? Awesome! It’s a brilliant path that offers tons of freedom, flexibility, and the chance to finally be your own boss. But with great freedom comes… well, a bit of paperwork. One of the first big decisions you'll face is how to set yourself up, which is where you’ll hear the phrase ‘contracting as a limited company’.
When you set up a limited company, you’re creating a whole new legal person that’s separate from you. You become the director of that company, its captain.
Don't let the formal name spook you. Think of it like this: instead of being 'Jane Doe, the Marketing Guru', you become 'Jane Doe, director of Doe Marketing Magic Ltd'. In the eyes of the law, you and your company are now two separate things. This creates a protective bubble, often called a 'corporate veil'. If the business were to hit a financial rough patch, your personal stuff—like your house or your car—is generally safe and sound.
The Perks and the Paperwork
Choosing to set up a limited company brings some fantastic advantages, but it’s not all sunshine and tax savings. You are stepping into the role of a company director, and that comes with some grown-up legal responsibilities. It’s really important to weigh up both sides before you dive in headfirst.
To help you get your head around it, here’s a quick rundown of what it all means in practice.
Limited Company Contracting at a Glance
Here’s a quick summary of the key pros and cons to help you weigh up your decision.
| Key Aspect | What It Means for You |
|---|---|
| Tax Efficiency | This is the biggie. You can pay yourself a small salary and take the rest as dividends, which have a lower tax rate. This can seriously boost your take-home pay compared to other routes. Ker-ching! |
| Professional Image | Operating as ‘Your Name Ltd’ often looks more professional to clients. Some bigger companies even insist their contractors work through a limited company. |
| Liability Protection | Your personal finances are separate from the business. If the company gets into debt, your personal assets are protected. Phew! |
| More Admin | You're responsible for filing annual accounts with Companies House and a Corporation Tax return to HMRC. It’s more paperwork, for sure. Think of it as the price of admission. |
| Director Duties | As a director, you have legal duties to act in the company's best interests. This is a formal role with rules to follow, so no going rogue! |
| IR35 Complexity | You need to be aware of the IR35 rules, which are HMRC's way of checking if you're a genuine contractor. Getting this wrong can be a costly headache. |
Ultimately, deciding whether to go limited is a personal choice. It really depends on your potential earnings, how much you like (or loathe) admin, and how comfortable you are with the responsibilities. Many contractors find the benefits far outweigh the extra work, especially with a good accountant on their side to handle the boring bits.
If you’re ready to learn how you can keep more of what you earn while building a professional brand, you’re in the right place.
Feeling a bit bamboozled by the detail? Don't worry, that's what we're here for. Get in touch with Artema for a friendly chat about your options.
Comparing Your Three Main Options as a Contractor
Right, so you’ve decided to take the plunge into contracting. Excellent choice. Now for the next big decision: how are you going to operate? Think of it like choosing a car for a road trip. Are you after a high-performance sports car that’s incredibly efficient but needs regular maintenance? Or is a reliable, easy-to-drive hatchback more your speed?
Let's line up your three main choices: setting up a Limited Company, working as a Sole Trader, or using an Umbrella Company.
Choosing the right structure isn’t about finding the single "best" option. It’s about finding the one that's best for you. It all comes down to your expected income, how much admin you're willing to handle, and what your long-term plans are.
The Main Contenders
Let's break down the three paths you can take. Each has its own distinct personality, and getting to know them is the first step toward making a smart choice.
- Limited Company: This is your high-performance model. It's generally the most tax-efficient and, crucially, protects your personal assets by creating a separate legal entity. The trade-off? It comes with the most admin. You're the director, the boss, and the chief paper-pusher.
- Sole Trader: The simplest way to get up and running. It’s just you, your skills, and your business name. The admin is much lighter, but there’s no legal separation between you and the business. This means your personal assets, like your house, are on the line if things go wrong. Yikes.
- Umbrella Company: This is the "pay-as-you-go" route. You effectively become an employee of the umbrella company. They handle all your tax, National Insurance, and invoicing in exchange for a fee. It’s by far the least hassle but also the least tax-efficient of the three.
To help you visualise this decision, the flowchart below walks you through the key questions you should be asking yourself.
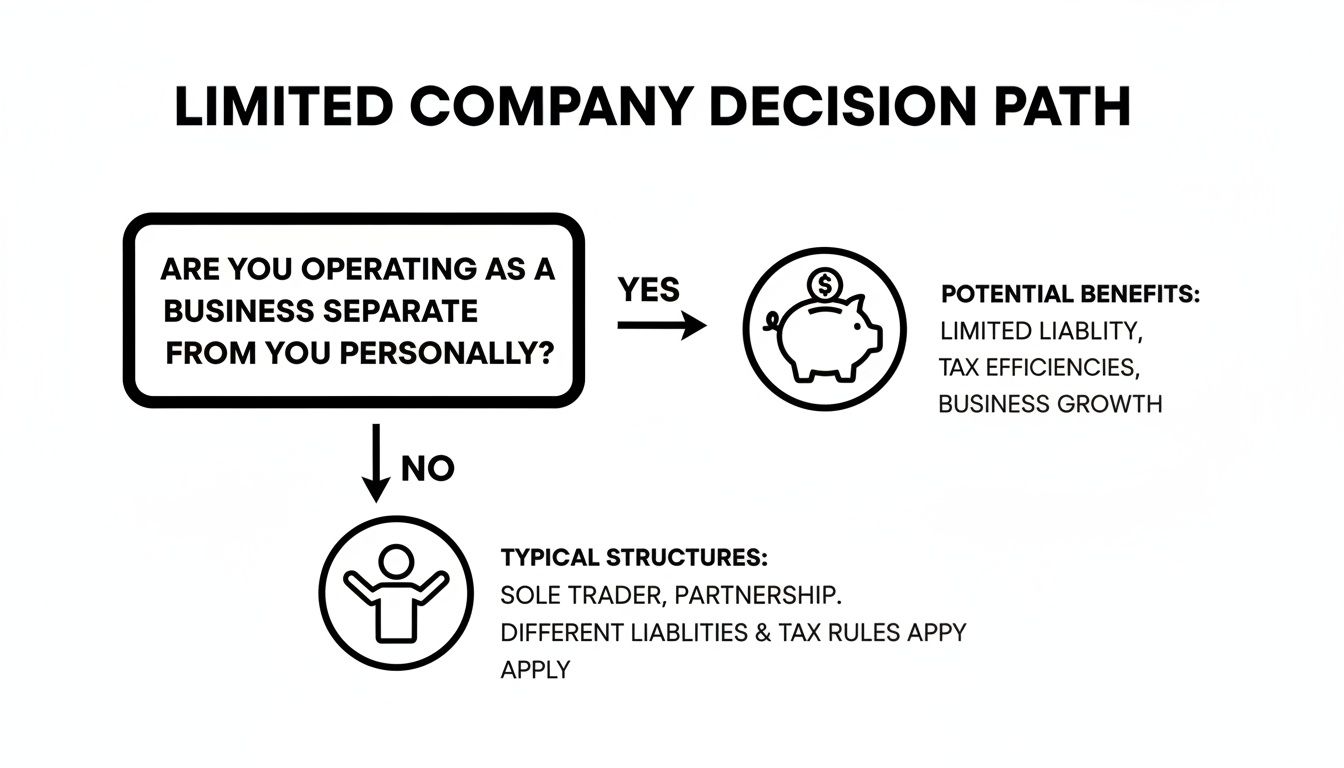
As you can see, the choice often comes down to a trade-off: balancing your potential earnings and liability against the amount of administrative work you’re prepared to take on.
Let’s Talk Money: A Simple Example
Imagine you’ve just landed a great contract and invoiced your client for £5,000. How does that cash actually get into your pocket in each scenario? Here’s a very simplified look.
Limited Company: The £5,000 lands in your dedicated business bank account. From its profits, the company pays Corporation Tax. You can then pay yourself a small, tax-efficient salary and draw the rest out as dividends, which are taxed at lower rates than regular income. This structure almost always results in the highest take-home pay.
Sole Trader: That £5,000 is your income. You’ll pay Income Tax and National Insurance on your profits via your annual Self Assessment tax return. It’s straightforward, but you’ll likely pay more tax overall, especially as your earnings increase. For a detailed breakdown of the numbers, check out our guide comparing a sole trader vs limited company.
Umbrella Company: The umbrella firm invoices the client for your £5,000. They then deduct their fee, employer's National Insurance, and income tax (PAYE) before paying you the rest as a standard salary. It’s simple and requires no effort from you, but it also gives you the lowest take-home pay.
The Growing Popularity of Going Limited
There's a clear trend of UK professionals choosing the limited company route, and it's not by chance. Recent official data shows that between March 2024 and March 2025, the number of limited companies grew by 1.8%. In contrast, the number of sole proprietorships actually decreased by 4.1%.
A huge 44.0% of UK companies are now single-employee businesses—a structure perfectly suited to contractors seeking liability protection and smarter tax planning. You can explore the full business population estimates to see these trends for yourself.
Ultimately, for contractors earning a healthy income, operating as a limited company is often the logical next step. It allows you to be more tax-efficient and protects you legally. While it does come with more responsibility, the financial rewards and professional standing can make it well worth the effort.
Feeling a bit lost in the options? That’s completely normal. Just drop us a line at Artema. We can have a friendly, no-obligation chat to figure out which "car" is the right fit for your contracting journey.
Setting Up Your Limited Company Without the Headaches
The words ‘company formation’ probably bring to mind stuffy boardrooms and endless stacks of legal documents. Let’s get rid of that image right now. Setting up your limited company is a lot more like building a flat-pack wardrobe: it looks a bit complicated on the box, but if you just follow the steps, you'll have something solid and functional in no time.
This is your friendly, plain-English guide to getting registered with Companies House, the official registrar of all UK companies. We'll walk through the process together, making sure you start your contracting journey on the right foot.
Naming Your New Venture
First things first, you need a name. This is the fun part, but there are a few rules of the road. Your company name has to be unique and can't be too similar to one that’s already registered. A quick search on the Companies House register will tell you if your brilliant idea has already been taken.
Your chosen name also must end with ‘Limited’ or ‘Ltd.’. This isn’t just for show; it’s a clear signal to everyone that they’re dealing with a limited company, which is what gives you that all-important limited liability protection.
Finally, you’ll need to steer clear of any 'sensitive' words or expressions that could be misleading or offensive. You can’t just call yourself ‘British Contracting Royalty Ltd’ without some serious justification!
Appointing a Director and Shareholders
With a name picked out, you need to define the key players. This might sound grand, but for most contractors, it’s wonderfully simple.
- Director: This is the person legally responsible for running the company. Guess who? That's you! As the director, you’ll be making the key decisions and making sure the company meets all its legal duties.
- Shareholders: These are the owners of the company. And again, for a typical contractor, this will also be you. You'll almost certainly be the sole shareholder, owning 100% of the shares.
Think of it as being the captain and the sole passenger of your own ship. You steer it, and you own it. It’s a straightforward setup that gives you complete control.
Your Registered Office Address
Every limited company needs an official, physical UK address. This is your 'registered office', and it’s where all the official post from Companies House and HMRC will land. Critically, this address is on the public record for all to see.
For obvious privacy reasons, many contractors are hesitant to use their home address. That’s a very sensible thought! Luckily, you have a couple of easy alternatives:
- Use your accountant's address: This is a popular and professional option. It keeps your home life separate and means important mail goes straight to your financial expert.
- Use a virtual office service: These services provide a mailing address for a small monthly fee and simply forward your post on to you.
A key takeaway here is that your registered office doesn't have to be where you actually do your work. It's simply the official correspondence address for your business, so choose one that works best for your privacy and professionalism.
When to Call in the Experts
You can absolutely register your company yourself directly with Companies House online. The process is fairly quick and the fee is small. However, getting it right from the very start can save you a world of pain later on.
This is where a good accountant makes all the difference. An experienced contractor accountant can handle the entire formation process for you, making sure everything is set up correctly from day one. They’ll ensure your share structure is right for tax efficiency and that all the details are perfectly aligned with HMRC's requirements.
Letting an expert handle the setup lets you focus on what you do best: finding and starting your first contract. To get your operations running smoothly from the beginning, consider using essential small business tools that can simplify admin, project management, and client communication.
Starting your limited company doesn't need to be a major headache. By breaking it down into these simple steps, you can get set up and ready for business with confidence.
Feeling ready to make it official but want a guiding hand? Get in touch with us at Artema. We can manage the entire setup process, so you can start your contracting career on solid ground.
Managing Your Money: Taxes and Take-Home Pay
Right, let's get to the good stuff: the money. This is probably the biggest question you have about contracting through a limited company. How do you actually get paid, and how can you legally hang onto more of your hard-earned cash?
Let's unpack the financial side of things without sending you to sleep.
The most popular way to pay yourself is through a clever combination of a low salary and dividends. Think of it like a financial cocktail designed for tax efficiency. You pay yourself a small, regular salary—just enough to qualify for state benefits like the State Pension, but low enough to keep National Insurance payments to a minimum.
Then, you take the rest of your earnings as dividends. These are simply payments made to shareholders (that's you!) from the company's profits. The beauty of this is that dividends are taxed at a much lower rate than a regular salary, meaning your take-home pay gets a very welcome boost.
Getting Friendly with Tax
The word "tax" might make you want to run for the hills, but it's not as scary as it sounds once you know who the main players are. As a limited company director, you'll mainly deal with these:
- Corporation Tax: This is the tax your company pays on its profits. Before you can touch any dividends, you have to work out your profit and pay this tax to HMRC.
- VAT (Value Added Tax): If your company’s turnover tips over a certain threshold (currently £90,000 a year), you must register for VAT. You'll then add VAT to your invoices and pay it to HMRC, after deducting any VAT you've paid on your own business purchases.
- National Insurance: This is paid on your salary. By keeping that salary low, you can significantly reduce both your employee contributions and the company's employer contributions. It's a double win.
Many contractors find the VAT Flat Rate Scheme really helpful. Instead of tracking every bit of VAT on your purchases, you pay a fixed, lower percentage of your turnover to HMRC. It can massively simplify your bookkeeping, which is always a good thing.
The Magic of Business Expenses
One of the best perks of running a limited company is the ability to claim legitimate business expenses. Every pound you spend on running your business can be deducted from your company's profit before Corporation Tax is calculated. Less profit means less tax. Simple!
So, what can you actually claim for? The list is longer than you might think. As long as the expense is "wholly and exclusively" for business purposes, it's usually fair game.
Remember, claiming expenses isn't about finding sneaky loopholes; it's a legitimate way to reduce your tax bill. Think of it this way: your company is paying for its own running costs, not you personally. This is a fundamental benefit of having a separate legal business entity.
Common Expenses for Contractors
To give you an idea, here are some of the most common things contractors claim for. Keeping good records of these is key.
- Office Costs: A portion of your home bills (like heating, electricity, and broadband) if you work from home.
- Travel: Journeys to a temporary workplace, including mileage, train fares, and accommodation.
- Equipment: Laptops, software, and any other tech you need to do your job.
- Professional Fees: This includes accountancy fees (like ours!) and professional indemnity insurance.
- Phone Bills: The business part of your mobile phone contract.
Understanding how to structure your income and what expenses you can claim is vital for maximising what you take home. For a more detailed look, our guide on https://www.artema.co.uk/how-to-pay-yourself-limited-company/ breaks down the numbers even further.
Beyond the basics, you can explore other ways to make your money work harder for you, such as various tax efficient investing strategies. With smart financial management, you can ensure your contracting career is as profitable as it can be.
Navigating the Murky Waters of IR35
Ah, IR35. Just hearing those two letters can send a shiver down the spine of even the most seasoned contractor. It’s the topic that often comes up in hushed tones, but let's clear the air.
IR35 isn’t a bogeyman hiding under your desk; it’s simply a set of tax rules designed to figure out one thing: are you a genuine, independent business, or are you a 'disguised employee' for tax purposes? That's it. HMRC wants to ensure that people who are essentially doing the job of an employee aren't using a limited company structure just to pay less tax.
The Key Tests: What Is HMRC Looking For?
To decide if a contract falls ‘inside’ or ‘outside’ IR35, HMRC looks at the reality of your working relationship with a client. They use a few key tests to build a picture of your engagement, and understanding them is your best defence.
Let's break down the big ones.
- Control: Who is in the driving seat? If your client dictates your exact working hours, tells you precisely how to do your job, and manages you like a regular team member, that’s a red flag. A genuine contractor controls how they deliver the agreed work.
- Substitution: Can you send a replacement? A truly independent business should have the right to send another qualified person to do the work in their place. If you personally must be the one to do the job, it looks more like employment.
- Mutuality of Obligation (MOO): Is there an expectation of more work? Once your current project is finished, is the client expected to offer you more work, and are you expected to accept it? If so, that looks like an ongoing employment relationship.
Think of it like hiring a plumber. You don't tell them which spanner to use or make them attend the family meeting. You just agree on the job (fix the leak) and the price, and they get on with it. That’s the kind of business-to-business relationship you want to have with your clients.
Inside vs. Outside IR35
Your contract’s IR35 status has a huge impact on your finances. The client is usually responsible for determining this status these days, but you absolutely need to understand what it means for you.
A contract is either ‘inside’ IR35 (you're treated like an employee for tax) or ‘outside’ IR35 (you're a genuine business). Getting this right is crucial for staying compliant and managing your take-home pay.
If your contract is deemed ‘inside’ IR35, the fee-payer (often the client or recruitment agency) must deduct income tax and National Insurance from your invoice before paying your company. This means your take-home pay will be significantly lower, just like a regular employee's.
But if you’re ‘outside’ IR35, you’re in the clear. You can receive your gross invoice amount into your company bank account and continue to pay yourself with that tax-efficient mix of salary and dividends.
Staying on the Right Side of the Rules
The best way to manage IR35 is to ensure your contracts and working practices genuinely reflect a business-to-business relationship. The rules have evolved over the years, and understanding the extension of off-payroll rules to the private sector is essential.
Be proactive, get your contracts reviewed, and operate like the independent professional you are.
IR35 can feel complicated, but it doesn't have to be a constant worry. If you’re ever unsure, getting expert advice is the smartest move you can make. Feeling a bit lost in the IR35 maze? Contact Artema today, and we’ll help you navigate it with confidence.
Your Pre-Flight Checklist for a Smooth Takeoff
Right, we’ve covered a lot of ground. You've learned about setting up, managing your money, and have even stared the dreaded IR35 beast in the eye. Now it’s time to turn all that theory into action.
Think of this as your pre-flight checklist before you take off on your contracting adventure. Getting these things right from the start is about building a solid foundation, not just ticking boxes.
The Launchpad Checklist: Your First Steps
Getting the initial setup sorted is crucial. It’ll save you a world of headaches later on and makes sure you’re operating professionally from day one. It’s a bit like assembling flat-pack furniture—follow the instructions in the right order, and you won’t be left with any mysterious spare screws at the end.
Here’s what you need to do first:
- Register Your Company: Head over to Companies House (or let your accountant handle it) to officially register your limited company name and details.
- Open a Business Bank Account: This one's non-negotiable. You absolutely must keep your business finances separate from your personal money. It makes bookkeeping a thousand times easier and, more importantly, it's a legal requirement.
- Get Insured: Don't even think about skipping this! Professional Indemnity and Public Liability insurance are essential. Many clients won’t even consider working with you unless you have them.
- Appoint an Accountant: Find a specialist contractor accountant (ahem, like us!). This is probably the most important step you can take. A good accountant will handle the tricky stuff, keep you compliant, and save you money in the long run.
Staying on Track: Ongoing Tasks
Once you’re up and running, the journey doesn’t stop. Being a company director comes with a few ongoing responsibilities. Staying on top of these will keep you compliant and let you sleep at night.
Think of these as your regular maintenance checks.
- Keep Your Books Tidy: Record every invoice you send and every business expense you incur. Good bookkeeping is the bedrock of a healthy business, and modern accounting software makes this a doddle.
- Set Money Aside for Tax: This is the golden rule. When a client pays you, immediately move a portion (say, 20-25%) into a separate savings account for your Corporation Tax and VAT bills. Future you will be incredibly grateful.
- File Your Accounts: Each year, you'll need to submit annual accounts to Companies House and a Corporation Tax return to HMRC. Again, this is where your accountant really earns their keep.
Remember, contracting as a limited company means you're not just a contractor; you're the director of a business. Embracing this mindset is the key to success. It’s about being organised, proactive, and making smart decisions from the start.
Choosing the right accountant isn't just another cost on your spreadsheet; it’s the single best investment you can make in your new career. A great accountant does more than just file your taxes—they become your financial co-pilot, guiding you through the complexities and ensuring you’re as tax-efficient as possible.
Ready to launch your limited company with confidence? Get in touch with Artema today. We’ll handle the numbers, so you can focus on what you do best.
Your Questions Answered
We’ve unpacked a lot of information, but a few questions might still be bubbling away. Let’s tackle some of the most common ones we hear from contractors who are just starting out.
How Much Does It Cost to Set Up and Run a Limited Company?
Getting started is surprisingly affordable. You can register your company with Companies House for just £12 – probably less than you spent on coffee last week! The real ongoing cost comes from professional accountancy services, which typically range from £80 to £150+ per month.
It’s best to see these costs not as an expense, but as an investment. A sharp accountant doesn't just keep you compliant; they actively find ways to save you money, often far more than their monthly fee.
When Should I Switch from Sole Trader to a Limited Company?
There isn't a single magic number, but a common trigger point is when your annual profits start getting close to the higher-rate income tax threshold (currently £50,271). Once you cross that line, the tax efficiencies you can get from a limited company's salary and dividend structure really start to shine, usually making the extra admin well worth it.
Another big reason is liability. If you’re taking on bigger contracts, or simply want to create a clear legal barrier between your business and your personal assets (like your home), forming a limited company is a very smart move.
Do I Really Need an Accountant for My Limited Company?
Technically, no. But it's a bit like trying to do your own dental work – possible, but definitely not recommended! The accounting and filing requirements for a limited company are worlds apart from the simplicity of a sole trader tax return. You're juggling Corporation Tax, VAT, payroll, annual accounts, and confirmation statements, all with strict deadlines.
A great contractor accountant does more than just file your taxes. They become a proactive part of your business, ensuring you're structured in the most tax-efficient way possible. Their advice should easily save you more than they charge, making them one of the best investments you can make.
Feeling ready to take the next step in your contracting career? Getting the right accountant on your side from day one is the single best way to start off on the right foot. The team here at Artema can take care of all the financial heavy lifting, leaving you free to focus on what you do best: delivering fantastic work for your clients.
Get in touch with us today for a friendly, no-obligation chat!