
Alright, let's dive straight in. One of the biggest head-scratchers for people setting up a new business is about tax and Limited Liability Partnerships (LLPs). So, the burning question is: do LLPs pay Corporation Tax in the UK?
The short and sweet answer is a big, friendly no.
An LLP itself doesn’t get a bill from the taxman for Corporation Tax. Think of it like a see-through pipe—the profits flow straight through the business and land in the pockets of the members. It's the members who then have a chat with HMRC and sort out their tax on their personal tax returns, not the LLP as a business.
The Short Answer: Do LLPs Pay Corporation Tax?
So, you’re weighing up the pros and cons of an LLP. The tax question is always a whopper, and the key idea to wrap your head around is tax transparency.
When we say an LLP is ‘tax transparent’, it’s just a fancy way of saying HMRC basically wears X-ray specs, looking straight through the business to see the individual members behind it. This is a totally different ball game to how a limited company is treated.
A limited company is its own legal 'person' (and a taxpayer). It's like a solid box. The company makes a profit, pays Corporation Tax on that profit, and then the directors can share out what’s left to shareholders as dividends.
What Tax Transparency Really Means
For tax purposes, an LLP is treated a lot like a classic partnership. The LLP itself still has to file a Partnership Tax Return (form SA800) to let HMRC know what it earned, but it won’t actually pay any tax from its own bank account.
Instead, the profits are divvied up between the individual members. Each member then pops their share on their personal Self-Assessment tax return and pays the right amount of Income Tax and National Insurance. Easy peasy.
This setup is pretty common worldwide, though the rules can change a bit from place to place. If you're curious about how LLPs are handled elsewhere, you can explore this comprehensive guide to Limited Liability Partnerships in Canada to see another perspective.
The big takeaway is this: With an LLP, the tax headache shifts from the business to the individuals. The LLP makes the money, but the members pay the tax.
Getting this right is super important when you're picking the best structure for your business.
To make things crystal clear, we've knocked together a quick comparison table that breaks it all down.
Quick Look: LLP vs Limited Company Tax
This table shows the fundamental tax differences at a glance.
| Feature | Limited Liability Partnership (LLP) | Private Limited Company (Ltd) |
|---|---|---|
| Primary Tax Paid | Income Tax & National Insurance (by members) | Corporation Tax (by the company) |
| Tax Entity | Tax Transparent (profits pass through) | Separate Legal & Tax Entity |
| Profit Distribution | Profits allocated directly to members | Profits retained or paid as dividends |
Understanding this key difference is your first step to becoming a business finance whizz. Now, let’s see what this all means for you as an LLP member in the real world.
Understanding How LLP Members Are Taxed
So, if the LLP isn't getting a bill for Corporation Tax, who is? Well, that would be you, the member. The tax responsibility flows right past the business and lands squarely on your doormat. It’s one of the defining features of this structure.
This is because, in HMRC’s eyes, each member is treated as self-employed. Your share of the LLP's profit is simply your personal income for the year. The business is the vehicle for making the cash, but the tax is all on you.
This means you won't be wrestling with PAYE or Corporation Tax filings for the LLP's main profits. Instead, you'll be diving into the wonderful world of Self-Assessment.
Your Personal Tax Responsibilities
As an LLP member, your main tax duties are your personal Income Tax and National Insurance Contributions (NICs). These are the same taxes a sole trader would pay. You’ll be responsible for:
- Income Tax: Paid on your slice of the profits according to the standard UK income tax bands.
- Class 2 National Insurance: A flat weekly rate, paid if your profits are over a certain amount.
- Class 4 National Insurance: A percentage-based contribution paid on profits between certain limits.
Each member calculates and pays these taxes through their own annual Self-Assessment tax return. To get a handle on how LLP members are taxed, it's useful to understand the basics of a partnership tax return, even if the rules vary by country.
The crucial point is that your personal finances and the business's finances are directly linked for tax purposes. Keeping meticulous records isn't just good practice; it's essential for getting your tax return right and avoiding a telling-off from HMRC.
A Practical Example In Action
Let's imagine two freelance web developers, Alex and Ben, form an LLP. They have a brilliant year and their LLP makes a profit of £100,000. Their agreement says they split profits 50/50.
Here’s how the tax situation plays out:
- Profit Split: The £100,000 profit is divided. Alex gets £50,000, and Ben gets £50,000.
- No Corporation Tax: The LLP pays nothing. Zip. Zilch. Nada.
- Self-Assessment Time: Both Alex and Ben must declare their £50,000 share on their individual Self-Assessment tax returns.
- Paying the Taxman: They will each pay Income Tax and Class 2 and Class 4 National Insurance on their £50,000 income.
This simple scenario shows why personal financial planning is a top priority for LLP members. The business might be flying, but you need to be ready for your personal tax bill.
Feeling a bit bamboozled by the numbers? That’s totally normal. Getting expert advice on how to structure your drawings and plan for tax can make a world of difference. Feel free to get in touch with our team at Artema for a friendly, no-jargon chat about your situation.
The Corporate Member Plot Twist
Just when you thought you had the LLP tax thing all figured out, here comes a plot twist. So far, we’ve established that LLPs don't pay Corporation Tax. Simple. But what happens if one of the members isn't a person at all, but a limited company?
This is where the picture gets a bit more colourful. An LLP with both human and corporate members is what HMRC calls a 'mixed membership partnership'. It's a bit like a band where most members are solo artists, but the drummer is a registered corporation. HMRC keeps a very close eye on these setups to make sure they aren’t just a sneaky way to shuffle profits around to pay less tax.
When Corporation Tax Enters The Scene
Under specific anti-avoidance rules, HMRC can decide that a chunk of the LLP's profit should be shifted from an individual member to a corporate one. If this happens, that profit suddenly becomes subject to Corporation Tax.
This usually happens if the corporate member has a lot of say over the individual’s profit share, and it looks like the main reason for the setup is to get a tax advantage. The rules are there purely to stop profits from being sneakily diverted to a company just to take advantage of lower Corporation Tax rates.
To get a clearer picture, it’s worth understanding the typical tax advantages that limited companies can offer, which explains why these rules are in place.
Essentially, if HMRC suspects that a corporate member is just being used to sidestep higher rates of personal Income Tax, they can step in. The corporate member would then be on the hook to pay Corporation Tax on the profits it's deemed to have received.
This scenario shows just how complex business structures can get. It's a far cry from the £97.2 billion in total corporate taxes collected in the UK for 2024-25, a figure that standard LLPs don't contribute to unless these specific rules are triggered. You can discover more UK corporation tax statistics to see the bigger picture.
Navigating these mixed-member rules is definitely not a DIY job. This is the point where getting professional advice becomes an absolute must to stay on the right side of the taxman.
If you're thinking about a more complex LLP structure, let's have a chat at Artema. We can help you understand all the fiddly bits and make sure everything is set up correctly from the get-go.
Choosing Your Structure: LLP vs Limited Company
Right, let's get down to business. In one corner, you've got the flexible and friendly Limited Liability Partnership (LLP). In the other, the traditional and solid Private Limited Company (Ltd). Choosing between them can feel like a business showdown, but it’s not about finding a single winner—it’s about finding the perfect fit for what you want to achieve.
This decision is about more than just tax. It's about finding a structure that feels right for your vision. Are you a team of consultants wanting an easy way to split the profits? Or are you building a brand, aiming to reinvest and grow like crazy? Answering these questions is the first step.
Tax Efficiency: The Big Picture
We’ve established that LLPs don't pay Corporation Tax, but that doesn’t automatically make them the most tax-efficient choice for everyone. A limited company pays Corporation Tax on its profits, and the rate can often be lower than higher-rate personal Income Tax. This is a massive advantage if your main goal is growth.
By keeping profits inside the company, you can pump that cash back into the business after only paying Corporation Tax on it. This is a huge reason why so many businesses choose the limited company route. The UK's tax system encourages this, with HMRC data showing onshore Corporation Tax receipts hitting a whopping £82.3 billion in the 2023-2024 financial year, thanks to the 25% main rate. You can read more about these Corporation Tax statistics on the government's website.
An LLP, on the other hand, passes all its profits directly to its members, who then pay Income Tax at their personal rates. This is brilliant for its simplicity but can be less efficient if you want to keep a lot of money in the business to fund future projects.
Flexibility vs. Formality
Another key difference is how you share the goodies. An LLP agreement can be incredibly flexible, letting you slice up the profits almost any way you like, regardless of how much cash each member put in. Need to give a new partner a bigger slice in their first year as a welcome bonus? With an LLP, that's a piece of cake.
A limited company is much more structured. Profits are usually shared out to shareholders as dividends, based on how many shares they own. While you can get creative with different share structures, it’s generally less fluid than an LLP’s profit-sharing setup. This choice is a bit like deciding between being a sole trader or a limited company; if that’s on your mind, our guide on sole trader vs limited company has some really useful insights.
Key Takeaway: If your priority is reinvesting profits for growth, a limited company often has the edge. If you value simplicity and flexible profit sharing among partners, an LLP is tough to beat.
To help you see the differences side-by-side, here’s a quick head-to-head.
Head-to-Head: LLP vs Limited Company
Comparing the key features of LLPs and Limited Companies to help you decide which structure suits your business needs.
| Consideration | Limited Liability Partnership (LLP) | Private Limited Company (Ltd) |
|---|---|---|
| Tax on Profits | Profits are taxed directly on members via their personal Income Tax and NICs. The LLP itself pays no tax. | The company pays Corporation Tax on its profits. |
| Extracting Profits | Members draw profits as per the LLP agreement. Taxed as income. | Profits are extracted via salaries (subject to PAYE) and/or dividends (taxed separately). |
| Reinvesting Profits | Less tax-efficient as all profits are deemed distributed to members each year, attracting personal tax rates. | Very tax-efficient. Profits can be retained in the company after paying only Corporation Tax, allowing for faster growth. |
| Ownership & Management | Owned and managed by its members (partners). | Owned by shareholders and managed by directors (can be the same people). |
| Flexibility | Super flexible. Profit-sharing ratios can be easily changed through the LLP agreement. | More rigid. Profit distribution is based on shareholdings. Less flexible day-to-day. |
| Privacy | Must file accounts, but less detail is required compared to a limited company (no directors' report needed for small LLPs). | Requires more detailed public filings at Companies House, including a confirmation statement and annual accounts. |
| Best For | Professional services (solicitors, accountants), joint ventures, and businesses where flexible profit-sharing is key. | Businesses aiming for serious growth, looking for external investment, or wanting to build a saleable brand. |
Ultimately, choosing your business structure is a massive decision. It will impact your tax bills, your admin load, and your growth potential for years. Making a confident, informed choice now is one of the best things you can do for your future success.
Feeling a bit stuck between the two? It’s a big decision, and you don’t have to make it alone. Book a call with the Artema team, and we'll help you weigh up the pros and cons for your unique situation.
Your Simple LLP Compliance Checklist
Running an LLP means you've got a few routine tasks to keep everything ticking over nicely with HMRC. It's less like navigating a legal minefield and more like remembering to put the bins out on the right day – you just need to be organised.
Think of compliance as the MOT for your business engine – it keeps everything running smoothly without any surprise breakdowns. With a simple checklist, you can handle your duties without the headache. It's not a test; it's just about getting the right info to the right people at the right time.
This decision tree shows how your growth goals can influence whether an LLP or a Limited Company is the better fit for you.
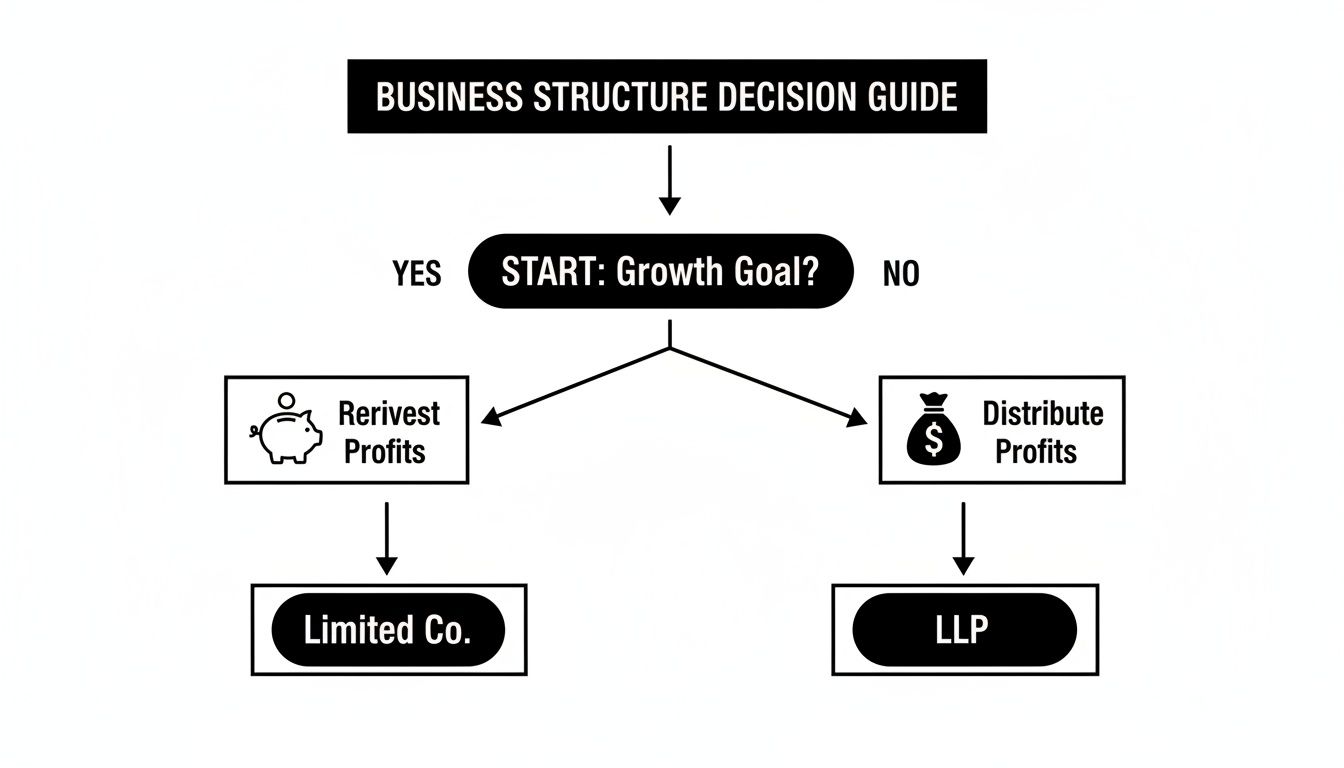
The key takeaway is clear: if your priority is distributing profits directly to members, the LLP structure is often the most direct route.
Key Filing Obligations
Here are the main admin jobs you'll need to stay on top of. Ticking these off each year will keep you in HMRC’s good books, which is always a happy place to be.
-
Partnership Tax Return (SA800): This is the LLP’s own tax return. It tells HMRC how much profit the partnership made and how it was split between the members. Crucially, no tax is paid with this form—it’s just for information.
-
Members' Self-Assessment (SA100): This is where the tax actually gets paid. Each individual member must declare their share of the LLP profit on their personal tax return and pay the Income Tax and National Insurance that's due.
-
Annual Accounts: Your LLP must file accounts with Companies House each year. The level of detail needed depends on the size of your LLP, but it's a non-negotiable step.
Other Important Considerations
Beyond the main tax filings, a couple of other duties might appear on your to-do list as your business grows.
Don't let compliance become a chore you dread. With a simple system in place, it’s just another part of running a successful business. Getting it right from the start saves a world of hassle later on.
First up is VAT. If your LLP’s taxable turnover goes over the VAT registration threshold (currently £90,000), you must register for VAT. This means you’ll need to start charging VAT on your sales and submitting regular VAT returns to HMRC.
Finally, remember that registering your partnership correctly is the very first step. For a clear breakdown of the process, our guide on how to register a partnership with HMRC is a great place to start. Getting the setup right makes all the ongoing jobs much simpler.
Feeling unsure about any of these steps? That’s what we're here for. Give the Artema team a shout, and we can walk you through it all, stress-free.
So, Which Structure is Right for Your Business?
Feeling a bit clearer on the whole Corporation Tax thing? Good. By now, you know the big secret: LLPs don't pay Corporation Tax. Instead, the tax responsibility lands on the members, making personal tax planning the name of the game – a completely different world to running a limited company.
Let’s wrap it all up. Choosing your business structure isn't just a box-ticking exercise; it's one of the most important decisions you'll make. It affects how you take home your earnings, how much tax you pay, and how much paperwork lands on your desk.
Think of it like choosing a car for a journey. An LLP is like a nimble, adaptable 4×4, perfect for navigating varied terrain with partners. A limited company is more like a powerful lorry, built for heavy lifting and reinvesting for the long haul. Both are brilliant, but you wouldn't take the lorry on a weekend trip to the beach.
Aligning Your Structure with Your Ambition
So, which one fits you? The answer really boils down to your goals.
- Creative partners: A couple of freelance web designers teaming up would probably love the simplicity and flexible profit-sharing of an LLP.
- Property investors: A group managing a property portfolio might favour an LLP to distribute rental income directly to the members, dodging the complexities of corporation tax.
- High-growth startups: A tech business aiming for rapid expansion will almost certainly lean towards a limited company. It’s far more tax-efficient for holding onto profits to fuel growth.
Making the right call from day one sets you up for a smoother ride. The wrong one can lead to unnecessary tax bills and a mountain of admin headaches.
Getting this right isn't just about saving tax this year; it's about building a financial foundation that supports your vision for tomorrow. This single decision has long-term consequences for your personal wealth and the growth of your business.
Feeling stuck? Don’t let the decision paralyse you. Navigating the maze of tax rules and business structures is exactly what we’re here for. A quick, informal chat can often bring your options into sharp focus and give you the confidence to move forward.
Why not make it easy on yourself? Get in touch with the Artema team today for a no-obligation chat. We'll help you pick the right vehicle for your business journey, making sure you're on the fastest, smoothest road to success.
A Few Final Questions
Right, we've covered a lot, but a few common questions always pop up. Let's tackle them head-on with some quick-fire answers.
Can HMRC Ever Force an LLP to Pay Corporation Tax?
As a general rule, absolutely not. The whole point of an LLP is that it's ‘tax transparent’ – the tax liability flows straight through to the members. But, there’s always an exception that proves the rule. As we touched on earlier, if HMRC thinks a mixed-member LLP is being used just to dodge tax, they have the power to step in.
In these specific cases, they can reallocate profits to the corporate member. That slice of the profit pie would then get hit with Corporation Tax. It’s a specific anti-avoidance measure, not the norm.
What Happens if an LLP Member Lives Abroad?
Now this is where things can get particularly tricky. For a member who isn't a UK resident, their tax bill depends entirely on their residency status and any double-taxation agreements between the UK and their home country.
Typically, they will still be on the hook for UK tax on their share of any profits from the LLP's UK-based activities. This is definitely one of those situations where getting professional advice is a must-have, not a nice-to-have.
Are LLP Members Classed as Self-Employed?
Yes, for all tax purposes, individual members of an LLP are treated as self-employed. This means they aren't on a payroll and don't pay tax through PAYE. Instead, it's up to them to file a personal Self-Assessment tax return each year and sort out their own Income Tax and National Insurance.
The key takeaway is simple: in almost all standard setups, the answer to "do LLPs pay corporation tax" is a firm no. The responsibility falls squarely on the individual members.
Thinking about your business structure and feeling a bit lost in the details? Getting it right from the start is one of the best things you can do for your business.
Navigating tax rules doesn't have to be a headache. The team at Artema Ltd is here to provide clear, friendly advice to help you choose the right path and stay compliant, leaving you free to focus on what you do best. Get in touch with us for a no-obligation chat today.