
A cash flow forecast is your business's financial sat-nav. It's all about tracking the money coming in and going out over a set period, like a month or a quarter. The goal is simple: map out your expected income against your anticipated expenses. This shows you what your future bank balance will look like, helping you spot potential potholes before they become a real problem.
Your Business Crystal Ball: Why a Forecast Is Non-Negotiable
Let's be honest, the term 'cash flow forecast' sounds about as exciting as watching paint dry. But what if it was the closest thing your business had to a crystal ball? A financial guide pointing you towards success and away from trouble?
This guide is for you if you've ever felt that familiar knot of anxiety staring at your bank balance, wondering if you can really afford that new hire, that crucial piece of equipment, or even just next month's rent. It’s a feeling far too many business owners in the UK know well. In fact, a shocking 82% of business failures are chalked up to poor cash flow management. Ouch.
The Profit vs. Cash Conundrum
Many businesses fall into a simple but dangerous trap: confusing profit with cash. Your profit and loss statement might show you’re making money, which is fantastic! But that profit isn't cold, hard cash in the bank until your customers actually pay their invoices.
A cash flow forecast cuts through the confusion. It focuses solely on the actual money moving in and out of your account. Think of it as your financial reality check, helping you answer critical questions like:
- Will we have enough cash to cover payroll at the end of the month?
- When is the best time to invest in that new marketing campaign?
- Can we survive if our biggest client pays 30 days late?
By getting a clear view of these movements, you can learn more about the fundamentals of what financial forecasting is and why it's a game-changer for any business owner.
A cash flow forecast isn't just an accounting exercise; it's a strategic tool for survival and growth. It transforms reactive panic into proactive planning, giving you the confidence to make bold decisions.
More Than Just Numbers on a Page
Ultimately, learning how to create a cash flow forecast gives you control. It’s your early warning system, highlighting potential cash gaps months in advance so you can act accordingly. Instead of crossing your fingers and hoping for the best, you can plan for big moves with confidence.
To truly get the most out of your forecast, exploring various financial prediction methodologies can be invaluable. This insight helps you build a more robust and reliable picture of your financial future.
This guide will demystify the entire process in plain English. No scary jargon, no complicated formulas—just practical steps to build a forecast that gives you peace of mind. Ready to stop guessing and start planning? Let's dive in.
Gathering Your Financial Puzzle Pieces
Before you can predict the future, you need a clear picture of the present. Trying to build a forecast without the right information is like trying to bake a cake with half the ingredients missing – it’s just not going to end well. This stage is all about rounding up your key financial documents without getting lost in a sea of spreadsheets.
Think of it as a manageable treasure hunt, not an overwhelming accounting exercise. You’re simply gathering the clues that will reveal your business’s financial story.
Your Essential Data Checklist
To get started, you don't need every receipt from the last five years. You just need a solid overview of your recent financial activity. Looking back over the past 12 months is usually the sweet spot, as this historical data is your best guide for what might happen next.
Here’s a simple checklist of what to grab:
- Bank Statements: This is the big one! Your statements from the last year show every penny that has actually come in and gone out.
- Sales Records: This includes all your issued invoices, even the unpaid ones. It helps you see who owes you money and when you can realistically expect that cash to land.
- Supplier Invoices: Gather all the bills you owe to others. This isn’t just about what you’ve already paid, but what you’re committed to paying soon.
- Details of Regular Payments: Jot down those recurring costs like rent, salaries, software subscriptions (yes, all of them!), and any loan repayments.
Having this information at your fingertips is the first step in learning how to create a cash flow forecast that is both accurate and genuinely useful. These documents tell the real story of your cash movements, which is very different from the theoretical world of profits. For a deeper dive, understanding how to read a profit and loss statement can clarify that crucial difference between earned revenue and actual cash in the bank.
Spotting Your Business Rhythms
Once you have your data, it’s time to play detective. Looking back over the last 12 months helps you spot patterns and seasonal trends you might not have consciously noticed. Business is rarely a flat line; it has peaks and troughs, and your forecast needs to reflect this reality.
Start asking yourself a few questions as you review your records:
- Are there quiet months? Perhaps you’re a landscape gardener who sees a dip in sales every February.
- When do clients typically pay? Do your customers always seem to settle their invoices a bit late around Christmas?
- Are there big, lumpy payments? Don’t forget about those chunky, less frequent expenses that can catch you off guard if you're not prepared.
For UK businesses, a classic example is the quarterly VAT bill. It’s a significant cash outflow that doesn't happen every month. Forgetting to account for it is one of the quickest ways to find yourself in a tight spot.
By identifying these rhythms, you move from pure guesswork to informed estimation. You can anticipate the slow periods and prepare for the big bills, turning potential cash flow crises into manageable events. This historical context is the secret sauce that makes your forecast a genuinely powerful planning tool.
So, grab a cuppa, put on some good music, and let's get those puzzle pieces on the table.
Building Your First Cash Flow Forecast
Right, you’ve gathered your financial puzzle pieces and you’re ready for the main event. This is where we turn that pile of statements and invoices into something genuinely powerful—your business's financial roadmap. Don't worry, it's less about complicated accountancy and more about simple addition and subtraction.
We'll break it down into three core parts that even the most number-averse person can get their head around. Think of it as a basic rhythm: money comes in, money goes out, and what’s left is what you’ve got. That's it!
The Three Musketeers of Your Forecast
Every solid cash flow forecast, whether it's scribbled on a napkin or built in a fancy spreadsheet, relies on three key components. Getting these right is the foundation for everything else.
-
Cash In (The Fun Part): This is all the money you expect to receive. The key here is that it's not about the sales you make in a month, but the cash you actually collect. This could be customer payments, new loans, or even a cash injection from your own savings.
-
Cash Out (The Less Fun Part): This covers every single payment leaving your business account. We're talking about everything from the big ones like rent and payroll to the smaller stuff like your monthly software subscriptions or the milk for the office tea.
-
The Running Balance (Your Reality Check): This is the magic number. You start with your opening bank balance, add all the cash in, subtract all the cash out, and you get your closing balance for the period. That closing balance then becomes the opening balance for the next period. Simple!
To make this even easier, here's a quick breakdown of the typical items you'll want to track.
Essential Components of a Cash Flow Forecast
| Category | What It Is | Examples for a UK Small Business |
|---|---|---|
| Cash In | All actual money expected to land in your bank account during the period. | Customer invoice payments, cash sales, director's loans, grant funding, a new bank loan. |
| Cash Out | All payments you expect to make from your bank account. | Rent, salaries & NI contributions, supplier payments, VAT payments, corporation tax, software subscriptions, marketing costs. |
| Balance | The calculation that shows your net cash position at the end of the period. | Opening Bank Balance + Total Cash In – Total Cash Out = Closing Bank Balance. |
Getting a handle on these categories is the first big step. Now, let's look at how to fill them with realistic numbers.
Projecting Your Income Realistically
Now for the tricky bit: predicting the future. When forecasting your 'Cash In', it’s tempting to let optimism take over. You just know next quarter is going to be your best one yet! While that's a great mindset, your forecast needs to be grounded in reality.
Look at your historical sales data. If you've seen a steady 2% growth each quarter for the last year, it’s reasonable to project a similar increase. If February is always a slow month, don't suddenly predict a sales boom.
Be brutally honest about when customers pay, too. If your biggest client consistently pays 15 days late, you need to factor that delay into your forecast.
Top Tip: Don't forecast revenue based on when you send an invoice; forecast it based on when you genuinely expect the cash to hit your account. This single shift in thinking is a game-changer for forecast accuracy.
This realism is especially important for UK small businesses right now. Recent insights from the Intuit QuickBooks' Quarterly Small Business Insights Survey show that 57% of UK SMEs predicted rising costs, with 47% already facing cash flow difficulties. A grounded forecast isn't about being pessimistic; it's about being a smart, resilient business owner.
Estimating Your Outgoings
Forecasting your 'Cash Out' is usually a bit more straightforward because many of your costs are fixed or at least predictable.
- Fixed Costs: These are the easy ones. Rent, salaries, and insurance premiums are typically the same each month. Pop them into your forecast first.
- Variable Costs: These change depending on your sales activity, like raw materials, shipping costs, or contractor fees. Look at past data – what was your materials bill when you had a £10k sales month? Use that as your guide.
- One-Off Costs: These are the gremlins of cash flow! This is the stuff that can catch you out, like an annual corporation tax bill, a new laptop purchase, or a website redesign. Scan your calendar for the year ahead and pencil these in.
Building in a small buffer, maybe 5%, for unexpected costs is also a wise move. Think of it as a financial fire extinguisher—you hope you never need it, but you'll be incredibly glad it's there if you do.
Putting It All Together: A Practical Example
Let’s imagine you're a UK sole trader running a small graphic design business and you're forecasting for July.
You start the month with £3,000 in the bank. You know a client owes you £2,000 and usually pays mid-month. You also expect to complete a new project worth £1,500.
- Opening Balance: £3,000
- Cash In: £2,000 (invoice payment) + £1,500 (new project) = £3,500
For your outgoings, you have your fixed desk space rental of £250, software subscriptions totalling £100, and you plan to pay a freelance copywriter £500. You also need to put aside money for your tax bill.
- Cash Out: £250 (rent) + £100 (software) + £500 (freelancer) = £850
- Calculation: £3,000 (Opening) + £3,500 (In) – £850 (Out) = £5,650 (Closing Balance)
Your closing balance of £5,650 then becomes your opening balance for August. By repeating this process for the next 6-12 months, you've officially created a cash flow forecast! To streamline things, you can download a free cash flow forecasting template that does a lot of the heavy lifting for you. This turns those abstract numbers into a clear, actionable plan to guide your business decisions.
Finding Your Forecasting Rhythm
So you’ve put together your first forecast. Fantastic! But the big question now is, "How often do I need to look at this thing?"
The truth is, there's no one-size-fits-all answer. The right rhythm for forecasting is all about your business’s unique pulse. Think of it like this: you wouldn't check the weather for your summer holiday just once back in January. Your forecast needs the same regular attention, and how often depends entirely on how quickly cash moves in and out of your world.
Weekly vs Monthly Forecasting
A weekly forecast is your daily weather check. It’s detailed, immediate, and absolutely essential for businesses where cash moves fast. Imagine a bustling high-street café. Money from coffee sales comes in every day, but the supplier bills for milk and beans need paying weekly. For them, a monthly view is far too slow – they could hit a cash crunch in a matter of days, not weeks.
On the flip side, a monthly forecast is perfect for businesses with a more predictable and spaced-out cash cycle. A small consultancy working with clients on monthly retainers, or a landlord who collects rent once a month, doesn't need to track every single penny every day. A monthly overview gives them the clarity they need without getting bogged down in detail.
The Gold Standard: The Rolling Forecast
For most businesses, the ultimate goal should be the rolling forecast. It’s time to forget the old-school static annual forecast you create in January and then barely glance at for the next 11 months. A rolling forecast is a live, breathing, 12-month view of your finances that you constantly update.
It’s like the live traffic map on your phone. It doesn't just show the route you planned this morning; it updates in real-time with accidents and road closures, helping you find a better way to keep moving.
A rolling forecast does exactly that for your business. Every month (or quarter), you review your actual performance, tweak your future predictions based on what you’ve learned, and add a new period to the end. This keeps your financial view fresh, relevant, and helps you stay agile.
This adaptive approach is a game-changer, especially in the UK where 47% of SMEs report immediate cash flow concerns. A 12-month rolling forecast lets you get ahead of problems before they happen. For example, you might adjust your future income based on government data, which showed central government receipts hitting £86.4 billion in October 2025—a 7.3% increase year-on-year. You can dig deeper into these public sector finances and what they mean for the economy.
This simple decision tree can help you figure out where to start, based on your business type.
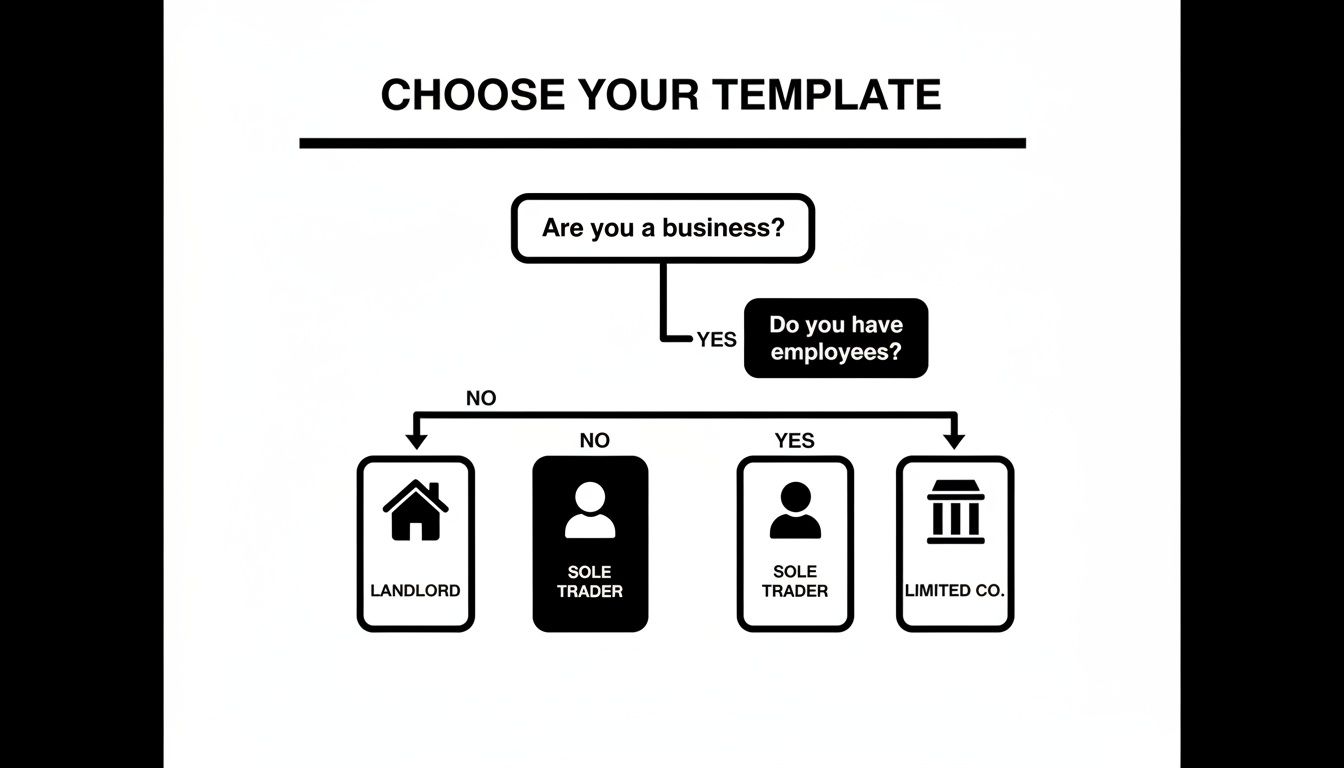
The key takeaway here is that your business structure—whether you're a sole trader, a limited company, or a landlord—shapes how complex your forecast needs to be.
When you find the right rhythm, your forecast stops being a dusty old map and becomes a trusted co-pilot. Experiment a little and see what feels right. The most important thing is to find a routine you can stick with, turning forecasting from a chore into a powerful business habit.
Stress-Testing Your Forecast with What-If Scenarios
So, you’ve built a solid forecast. High five! But a forecast based purely on everything going to plan is, let's be honest, just a wish list with numbers. Now it’s time to play devil’s advocate and throw a few imaginary spanners in the works.
This isn’t about being a pessimist; it’s about being a prepared realist. By stress-testing your numbers, you can spot potential cash gaps before they become real-life panic moments. It’s the difference between seeing a pothole from a distance and hitting it at full speed.
Introducing the Three Amigos of Forecasting
The best way to prepare for the unexpected is to create three different versions of your forecast. Think of them as different storylines for your business’s future. It’s a simple but incredibly powerful way to understand your financial resilience.
-
The Best Case (The "Sunshine and Rainbows" Scenario): This is your optimistic version. What happens if that huge new client signs on the dotted line, and everyone pays their invoices early? It’s fun to dream, but this version also shows you the maximum potential you can plan towards.
-
The Realistic Case (The "Most Likely" Scenario): This is the forecast you’ve already built. It's grounded in your historical data and sensible projections—the most probable path your business will take.
-
The Worst Case (The "Oh Dear" Scenario): Here’s where you get a little gloomy for a good cause. What if your biggest client pays 60 days late? What if your rent suddenly increases by 10%? This isn’t meant to scare you; it’s your financial fire drill.
By creating these three versions, you're not just guessing what might happen. You're building a strategic playbook that allows you to react quickly and confidently, no matter which scenario starts to unfold.
What-If Scenarios to Consider
To get your creative (and slightly cautious) juices flowing, here are a few classic "what-if" questions to ask yourself when building your best- and worst-case versions:
-
What if… a key client leaves or pays significantly late? Late payments are a huge headache. If a large invoice is delayed, you might need a plan B. Exploring options in advance, such as understanding what invoice factoring is, can give you a vital safety net.
-
What if… your sales drop by 20% for two consecutive months?
-
What if… a critical piece of equipment breaks and needs urgent replacement?
-
What if… a key supplier increases their prices without warning?
These aren't just hypotheticals. UK businesses crafting a cash flow forecast must also consider wider economic signals. The Bank of England’s May 2025 report, for example, projected unemployment could rise to 5%. You can learn more about how the latest Monetary Policy Report might impact your planning.
By modelling these scenarios, you can see exactly where and when a cash crunch might happen. This gives you precious time to create a contingency plan, turning a potential disaster into a manageable challenge.
Feeling a bit overwhelmed by the numbers? That’s completely normal. Having an expert pair of eyes can make all the difference. Get in touch with us at Artema, and we can help you build robust forecasts that prepare your business for whatever comes next.
Common Forecasting Mistakes and How to Avoid Them
Building your first cash flow forecast is a huge step forward for any business owner. But, a bit like baking your first sourdough loaf, it’s all too easy to make a few rookie mistakes. Don't worry, we’ve seen them all. Here are the most common blunders we come across and, more importantly, how you can sidestep them. The goal is to make your forecast a genuinely useful tool, not just a pretty spreadsheet.
One of the biggest traps is being wildly optimistic. We all want our businesses to smash it, but a forecast built on hope rather than history is just a fantasy. Remember that client who promised a huge project last year but then went quiet? It’s tempting to include them, but you can’t bank on that cash until the ink is dry on a contract.
Tip: Keep it real. Base your sales projections on your last 12 months of actual performance, not your biggest dreams. It's far better to be pleasantly surprised by extra cash than panicked by an unexpected shortfall.
Forgetting the Sneaky Costs
Another classic mistake is forgetting about those lumpy, one-off costs that only pop up once or twice a year. Think of them as the financial equivalent of standing on a piece of Lego in the dark – painful and completely unexpected if you're not prepared.
We're talking about things like:
- Annual insurance premiums that you pay in a single lump sum.
- Corporation tax bills that can take a huge bite out of your cash reserves.
- Accountancy fees for preparing your year-end accounts.
- Major equipment purchases or repairs that you know are on the horizon.
These expenses can easily derail your cash flow if you haven’t planned for them. The best thing to do is go through your calendar for the next year and pencil them into your forecast right now. You’ll thank yourself later.
Creating a 'Set It and Forget It' Forecast
Finally, perhaps the most dangerous mistake is treating your forecast like a historical artefact. You spend hours creating it, feel proud of your work, and then save it to a folder where it gathers digital dust. Your business is constantly changing, so your forecast needs to change with it.
It should be a living, breathing document. Make a habit of reviewing it monthly against your actual bank statements. Where were you right? Where were you wrong? This simple process makes each future forecast more accurate than the last. It turns your forecast from a static photo into a live video feed of your business's financial health.
Your Cash Flow Questions Answered
Feeling a bit more confident, but still have a few questions rattling around? You’re not the only one. Getting your head around how to build a cash flow forecast can sometimes feel like learning a new language. Let’s tackle some of the most common queries we hear from clients.
Think of this as the final polish on your new forecasting skills, making sure you can move forward with total clarity.
How Far Ahead Should I Forecast?
For most small businesses, a 12-month rolling forecast is the gold standard. It gives you a fantastic long-term view, allowing you to plan for the big things like seasonal lulls, big projects, or tax payments looming on the horizon.
That said, if your business has cash moving in and out very quickly (think a retail shop or a busy cafe), adding a shorter-term, more granular 13-week forecast can be a real lifesaver. It gives you a much tighter grip on your week-to-week cash position.
Should I Use a Spreadsheet or Software?
Honestly, both have their place! A simple spreadsheet is a brilliant way to start. It costs nothing and gives you complete control to really get a feel for how the numbers move.
As you grow, you might find that dedicated accounting software like Xero becomes a better fit. It can pull data straight from your bank feeds, which saves a huge amount of time and cuts down the risk of manual errors. At the end of the day, the best tool is the one you’ll actually use consistently.
A forecast is only useful if it's accurate and up-to-date. Don't let the search for the 'perfect' tool stop you from starting with a 'good enough' one today.
What’s the Biggest Mistake People Make?
By far, the most common slip-up is confusing profit with cash. You might have made a £10,000 sale (which looks great on the profit and loss report!), but until that invoice is actually paid, you don’t have £10,000 in the bank.
A cash flow forecast is purely about the actual money hitting and leaving your bank account. That’s the reality of your business's financial health. A crucial tip: always forecast based on when you realistically expect to be paid, not just the date you send the invoice.
Ready to turn your forecast into a powerful tool for growth, but want an expert to check your work? At Artema Ltd, we help business owners just like you build robust, reliable financial plans. Find out how our friendly team can support your business journey.