
Congratulations on getting your limited company up and running! Now for the important bit: paying yourself without handing a huge chunk of your hard-earned cash straight to HMRC. The smartest approach is usually a savvy combination of a small, regular salary, topped up with shareholder dividends.
Your Guide to Getting Paid as a Director
Welcome to the club! You've cleared the hurdles of setting up your business, and now it's time to enjoy the rewards. But when you own the company, you can't just dip into the bank account whenever you fancy a treat. The company's money is legally separate from your own, a crucial point many new directors miss.
Figuring out the best way to pay yourself can feel like a bit of a puzzle at first. But trust me, once you get the hang of it, it's much simpler than it seems.
Finding the Sweet Spot for Your Pay
The secret isn't just about taking one big salary. It’s about creating a tax-efficient blend that works for both you and your business. The goal is simple: structure your income to minimise your tax bill while keeping everything above board with HMRC.
This strategic approach usually involves a few key elements:
- A Modest Director's Salary: This is your foundation. By keeping it below certain thresholds, you can qualify for state benefits without paying much (or any) National Insurance.
- Shareholder Dividends: This is how you take a slice of the company's profits. Dividends are taxed at lower rates than salary, making them a fantastic way to boost your take-home pay.
- Claiming Expenses: Don't forget this one! Any legitimate business costs you've paid for personally can be reimbursed tax-free, which is another simple way to pull value from the company.
This visual guide breaks down the basic process of combining a salary with dividends to create a tax-efficient income stream.
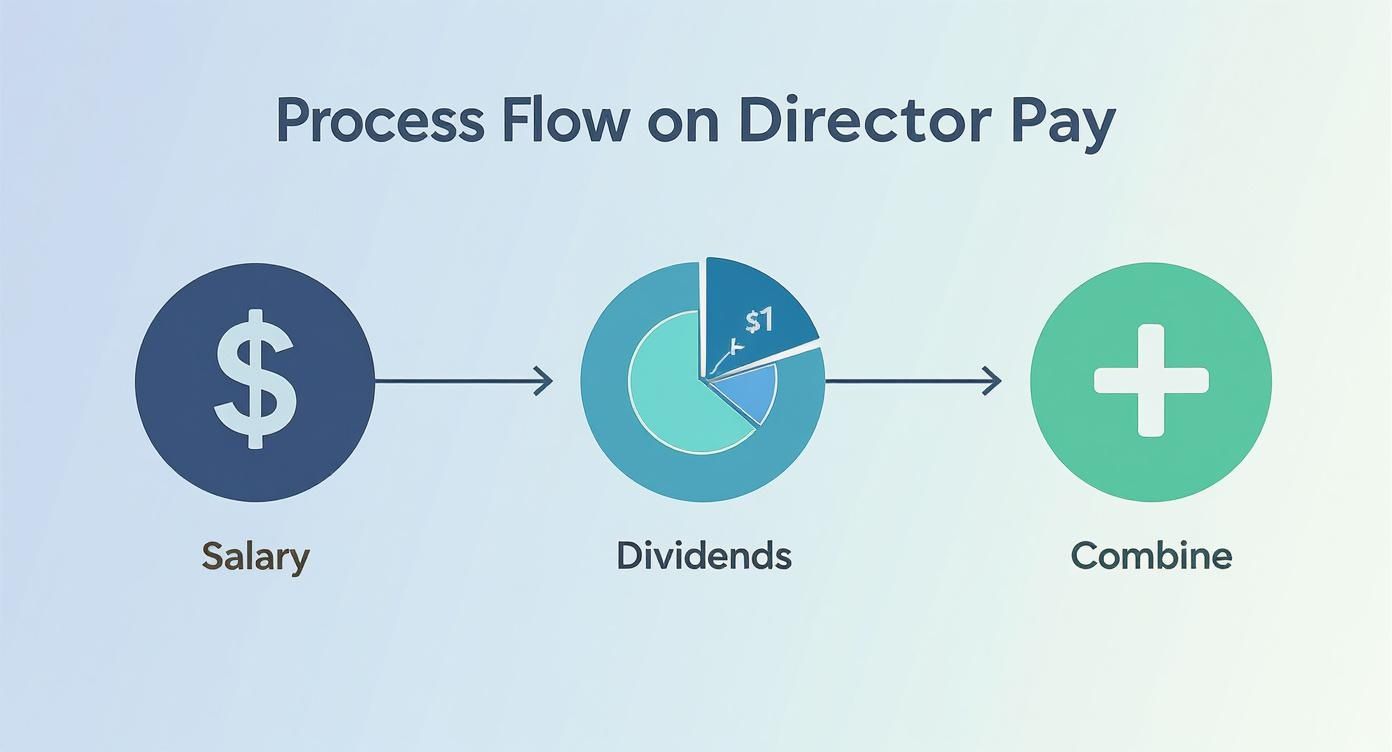
As the infographic shows, you start with a foundational salary and then layer on dividends to build a complete and efficient pay package. For a wider view on managing your finances, you might find these essential financial planning tips for freelancers useful, as many of the same principles apply.
Think of it like making the perfect cocktail. The salary is your reliable base spirit, and the dividends are the mixers you add to get the flavour just right. Too much of one, and the whole thing becomes unbalanced and expensive!
Consider this guide your financial roadmap. We'll walk you through everything, jargon-free, so you can confidently pay yourself what you're worth. Of course, getting the payroll side of things right is critical. Managing PAYE for your director's salary is a key step, and our experts can help simplify your payroll and CIS obligations. Let's get you paid.
Setting Up Your Tax-Efficient Director's Salary
Right, let’s talk about your director's salary. This isn't just about paying the bills; it's the solid foundation of your entire pay strategy. Think of it as the sensible, reliable part of your income plan before you get to the more exciting stuff, like dividends.
Many new directors fall into the trap of thinking a bigger salary is always better. It’s a common assumption—more salary equals more money, right? Well, not exactly. When it comes to how to pay yourself from a limited company, a smaller, consistent salary is often the cleverest first move you can make.
The goal here is to be smart and strategic. We want to align your salary perfectly with the UK's tax-free Personal Allowance and the thresholds for National Insurance. Get this right, and you unlock some fantastic benefits without giving a penny more than you need to HMRC.
Finding The Magic Number
So, what is this magic number? The sweet spot for a director's salary changes slightly with tax years, but the principle stays the same. You want to pay yourself enough to qualify for state benefits but not so much that you start triggering unnecessary tax and National Insurance payments for you or your company.
This approach is popular for a few key reasons:
- Qualify for State Pension: Paying yourself a salary above a certain level (the 'Lower Earnings Limit') means you're making 'qualifying years' for your State Pension, even if you don't actually pay any National Insurance. It’s like getting the credit without the cost.
- It’s a Business Expense: Your salary is a legitimate business expense. This means it gets deducted from your company's profit before Corporation Tax is calculated, which handily reduces your company's overall tax bill.
For the UK tax year 2025/26, the optimum salary for a limited company director has been identified as £12,570 per annum. This figure is brilliant because it lines up perfectly with the Personal Allowance, meaning you won’t pay a shred of income tax or employee National Insurance on it.
Optimal Salary vs High Salary Example
"But why not just pay myself a massive £50,000 salary and be done with it?" I hear you ask. It’s a fair question. Let's crunch some numbers in a simplified example to see why the low-salary, high-dividend model usually comes out on top.
| Metric | Optimal Salary (£12,570) | Higher Salary (£50,000) |
|---|---|---|
| Director's Income Tax | £0 | £7,486 |
| Director's National Insurance | £0 | £3,040 |
| Company's National Insurance | £0 | £5,183 |
| Total Tax & NI Leakage | £0 | £15,709 |
As you can see, the higher salary creates a huge tax and NI bill for both you and your company. The 'optimal' salary avoids this completely. You then top up your income with dividends, which are taxed at much lower rates.
Taking a huge salary is like trying to fill a leaky bucket—a big chunk of it spills out as tax before you even get to use it. A tax-efficient salary is a well-sealed bucket; you get to keep almost everything you put in.
This blended approach ensures you are rewarded for your hard work while operating in the most financially sensible way possible. Speaking of smart financial moves, a director's salary can also be used to make tax-efficient pension contributions. Find out more about how to optimise your employer pension contributions in our detailed guide.
Of course, setting up your director’s pay correctly involves more than just picking a number; it means being compliant with employment regulations. For comprehensive legal advice on establishing your director's salary and navigating related regulations, it is wise to consult with experts in employment law in Ontario or your local jurisdiction to ensure everything is above board.
By starting with a tax-efficient salary, you set yourself up for success. You minimise your tax burden, reduce your company's liabilities, and pave the way to take the rest of your earnings in a much smarter fashion. Now, let’s move on to the fun part—dividends.
Using Dividends to Top Up Your Income
So, you’ve set up your sensible, tax-efficient director's salary. It’s ticking along nicely, qualifying you for your State Pension and keeping the company’s tax bill down. But let's be honest, you didn't go into business just to get by. Now it's time for the good part—tapping into the profits you’ve worked so hard for.
This is where dividends come into play. Think of them as the reward for being a shareholder in your own successful venture. A dividend is simply your share of the company's profits after it has paid its Corporation Tax. It's the most common way directors top up that smaller salary to create a healthy personal income.
Crucially, unlike a salary, dividends are not a business expense. They are a distribution of profit after tax has been paid. This is a vital distinction and exactly why getting the paperwork right is so important.
Getting the Paperwork Right
You can’t just decide you fancy a dividend and move money from the business account to your personal one. That’s a one-way ticket to a headache from HMRC. To pay a dividend legally, your company must have enough retained profits. This means you look at all your income, subtract all your costs (including your salary and Corporation Tax), and whatever is left is the pot from which dividends can be paid.
For every dividend you declare, you need a paper trail. It sounds formal, but it’s actually quite straightforward. You need two key documents:
- Board Meeting Minutes: A record of the directors' meeting where the decision to pay a dividend was made. Even if you're the only director, you still need to minute your own meeting. It might feel a bit silly, but it’s a legal requirement.
- A Dividend Voucher: This is a simple certificate for each shareholder receiving the dividend. It shows the company name, the date, the shareholder's name, and the amount of the dividend paid.
Keeping this paperwork in order proves you're handling your company's finances correctly and separating your director duties from your shareholder rewards.
Understanding Dividend Tax
Here’s the good news: dividends are taxed more favourably than salaries. There’s no National Insurance to pay on them, which is a huge win for both you and your company. However, they aren't completely tax-free.
For the 2025/26 tax year, every taxpayer gets a £500 Dividend Allowance. This means your first £500 of dividend income is completely tax-free. Anything you take above this allowance is taxed, but the rates are lower than income tax.
The rate you pay depends on your overall income for the year (your salary + dividends + any other income).
- Basic Rate: 8.75%
- Higher Rate: 33.75%
- Additional Rate: 39.35%
To work out your tax band, you simply add all your income sources together. So, your £12,570 salary uses up your Personal Allowance, and your dividend income then starts stacking on top of that.
A Practical Dividend Example
Let's put this into practice. Imagine your company has had a great year. After paying your £12,570 salary and setting aside money for Corporation Tax, there’s a healthy profit left. You decide to pay yourself an additional £30,000 in dividends.
Here’s how the personal tax on that dividend would look:
- Dividend Allowance: The first £500 is tax-free.
- Remaining Dividend: You have £29,500 left to tax (£30,000 – £500).
- Tax Calculation: Your salary already used up your £12,570 Personal Allowance. Your total income is £12,570 + £30,000 = £42,570, which is comfortably within the basic rate tax band (up to £50,270).
- Tax Due: You’ll pay the basic rate of 8.75% on the remaining £29,500. So, your personal tax bill on this dividend is £2,581.25.
You are responsible for paying this tax yourself through your annual Self Assessment tax return. Many directors get into the habit of setting this money aside in a separate savings account so there are no nasty surprises when the tax bill arrives.
The key to managing how you pay yourself from a limited company is planning. Think of your salary as your weekly shop and dividends as your planned big purchases. You need to check the bank balance (company profits) before you head to the checkout.
Dividend Do's and Don'ts
Getting dividends wrong can lead to serious problems, so it’s vital to stick to the rules. An "illegal dividend" is one paid out when the company didn't have enough profit, and HMRC can demand it back, often with penalties.
-
DO check your company has sufficient retained profits before every single dividend payment.
-
DO complete board minutes and issue a dividend voucher for every payment, no matter how small.
-
DO set aside money from your dividends to cover your personal tax bill.
-
DON'T take money from the company and call it a dividend later. The paperwork must be done at the time.
-
DON'T pay out dividends if your company is struggling or might not be able to pay its bills.
-
DON'T forget to declare your dividend income on your Self Assessment tax return.
Using a salary-dividend mix is the most common and effective answer to the question of "how to pay yourself limited company". By understanding the rules and keeping your paperwork in order, you can reward yourself efficiently for all your hard work. If you're ever unsure, this is where a good accountant proves invaluable, ensuring you stay compliant and make the most of your profits.
Exploring Other Ways to Extract Company Value
While the classic salary-dividend combination is the bread and butter for most company directors, it's far from the only way to get value out of your business. Think of your company as a toolbox; the salary and dividend are your trusty hammer and screwdriver, but there are other, more specialist tools that can be incredibly useful in the right situation.
Let's be clear, this isn't about finding sneaky loopholes. These are perfectly legitimate, HMRC-approved ways to benefit from your company's money. Getting your head around these options can make a real difference to your overall financial picture and lead to much more productive chats with your accountant.
The Director's Loan Account
Ever needed a bit of cash for a short-term need but didn't want the paperwork of declaring a formal dividend? Welcome to the world of the Director's Loan Account. It's essentially a running tally of money you’ve borrowed from the company or, in some cases, lent to it.
Any money you take that isn't a salary, dividend, or an expense reimbursement is usually classed as a director's loan. It’s a wonderfully flexible way to borrow from your business, but it comes with some very strict rules. If you get it wrong, you could be facing a hefty tax charge that'll make your eyes water.
The biggest rule is this: if you borrow money and don't pay it back within nine months and one day of your company's year-end, the company gets hit with a special tax charge. This is a whopping 33.75% of whatever is left of the loan. While the company can eventually reclaim this tax once you repay the loan, it’s a cash flow headache you really want to avoid.
Think of a director's loan like borrowing a tenner from your mum. It's fine for a bit, but if you don't pay it back sharpish, there will be consequences (and probably some disapproving looks).
If you're thinking about going down this route, it pays to understand the full picture. For a deeper dive, learn more about borrowing from your company and keeping the tax cost down in our detailed guide.
Reclaiming Legitimate Business Expenses
This is one of the simplest, yet most frequently overlooked, ways to take money from your company completely tax-free. If you’ve paid for a genuine business-related cost with your own money, the company can and absolutely should pay you back.
This isn’t just for big-ticket items. It covers a whole host of day-to-day costs that are "wholly and exclusively" for business purposes.
- Home Office Costs: If you work from home, you can claim a flat rate allowance from HMRC without needing receipts. Alternatively, you can calculate a fair proportion of your actual household bills like heating and electricity.
- Mobile Phone Bills: Does your personal mobile double up as your work phone? The company can pay for a portion of the bill. To keep things clean, it’s often much simpler just to get a separate business contract in the company's name.
- Travel and Subsistence: Train tickets to meet a client, a hotel for a business conference, or even the mileage for using your personal car on business journeys can all be reclaimed.
Just keep your receipts, log everything properly, and get into the habit of putting in a monthly expense claim. It’s your money, after all!
Company Pension Contributions
Now we get to the real powerhouse of tax efficiency: company pension contributions. This is arguably the most effective way to extract profit from your company and invest directly in your future.
Here's how it works. When your limited company makes a payment directly into your personal pension, it's treated as an allowable business expense. This means the payment reduces your company’s profit, which in turn cuts its Corporation Tax bill.
The best part? Unlike a salary, there's no Income Tax or National Insurance to pay on the contribution. The money goes straight from your company's bank account to your pension pot, without HMRC taking a slice. It’s a fantastic way to build a serious retirement fund while getting full tax relief at your company’s Corporation Tax rate.
Other Benefits in Kind
Finally, your company can provide you with other non-cash perks, often called 'benefits in kind'. These could be things like private health insurance, a company car, or even a gym membership.
These aren't "free"—they usually attract some level of tax for both you and the company. However, they can sometimes be more cost-effective than paying for the same things yourself out of your post-tax income. It's all about weighing up the tax cost against the personal value of the benefit.
By exploring these different avenues, you can build a much more rounded and tax-efficient answer to the question "how do I pay myself from my limited company?". It's not just about what you take out today, but also about how you build wealth for tomorrow.
If you’re ready to create a truly smart pay strategy that goes beyond the basics, get in touch with our team at Artema. We can help you navigate all these options and build a plan that works for you.
A Real-World Pay Strategy in Action
Right, theory is one thing, but let’s see how this all clicks together in practice. It’s much easier to grasp when we follow the story of a business owner, a fictional consultant we’ll call Sophie.
Like so many directors, Sophie wants to make sure she’s drawing money from her limited company in the smartest way possible. Her consultancy is on track for a healthy £70,000 in pre-tax profit this year. As the sole director and shareholder, she has complete control over how she gets paid. Let's walk through her financial year.
Setting the Salary Foundation
First things first, Sophie gets herself on the company payroll. Following the classic tax-efficient model, she decides to pay herself a director's salary of £12,570. This is a clever move. It uses up her entire tax-free Personal Allowance, meaning she pays zero income tax and zero employee National Insurance on that amount.
Even better, this salary is a legitimate business expense. That means it’s deducted from her company’s profit before Corporation Tax is calculated.
Company Profit: £70,000
Director's Salary: – £12,570
Remaining Profit: £57,430
The company now works out its Corporation Tax on this lower profit figure, saving money right from the get-go.
Topping Up with Dividends
With her salary sorted and Corporation Tax accounted for, Sophie has a pot of post-tax profit ready to go. This is the money she can distribute to herself as dividends. She needs around £3,000 a month to cover her living costs, so she plans to take regular dividend payments throughout the year.
All told, she draws a total of £36,000 in dividends. Here’s a quick look at her personal tax position:
- Salary: £12,570 (no tax to pay, as it’s covered by her Personal Allowance).
- Dividends: £36,000.
- Total Income: £48,570.
The first £500 of her dividends is tax-free, thanks to the Dividend Allowance. The remaining £35,500 falls squarely into the basic rate tax band, where she’ll owe tax at 8.75%. This comes to £3,106.25. Sophie is savvy, so she tucks this money away in a separate savings account, ready for when her Self Assessment tax bill lands.
Adding the Extras
But Sophie doesn't stop there. She knows there are other tax-efficient tools she can use to make her money work even harder.
- Pension Contribution: She has her company pay £5,000 directly into her personal pension. This is another allowable business expense, reducing her Corporation Tax bill even further. Crucially, the money goes into her pension pot without her paying any income tax on it.
- Business Expenses: Over the year, Sophie claims £1,500 in legitimate business expenses that she paid for personally, like travel to client sites. The company reimburses her for this amount, completely tax-free.
Recent rule changes have made this kind of strategic thinking more important than ever. The government is always tweaking the balance between salary and dividends, and understanding your responsibilities as a director is key. You can find more official guidance on the government's website for employee directors.
By blending these different elements, Sophie has created a brilliant, tax-efficient pay package. She has a reliable income, she's building her pension for the future, and she's keeping her tax liabilities to an absolute minimum.
Sophie’s story is a clear blueprint for how to pay yourself from a limited company effectively. If you're ready to build your own success story, get in touch with the Artema team, and let’s put together a pay strategy that works perfectly for you.
Common Director Pay Mistakes to Avoid
Knowing the right way to pay yourself is one thing, but knowing what not to do is just as important. Getting it wrong can lead to serious headaches with HMRC, so let's walk through a few common pitfalls to sidestep.
One of the biggest blunders we see is declaring an 'illegal dividend'. This happens when you pay out a dividend without your company having enough post-tax profit to actually cover it. You can’t just pay yourself from whatever’s in the company bank account; the profit has to be there on paper first.
Forgetting the Paper Trail
Another classic error is forgetting the paperwork. Every single dividend payment, no matter how small, needs to be supported by board meeting minutes and a proper dividend voucher.
Without this paper trail, HMRC could reclassify the payment as a salary. That would land you with a hefty, unexpected bill for unpaid tax and National Insurance. It might feel a bit formal holding a "board meeting" with just yourself, but it's a non-negotiable legal step you can't afford to skip.
It's easy to see the huge pay packets of directors in big public companies and feel a disconnect. However, the strategies for owner-managed businesses are completely different. Your goal isn't market-rate remuneration; it's about tax efficiency.
Small business directors are almost always focused on minimising tax liabilities over simply maximising income. In fact, directors’ remuneration reports show that while top executives earn vast sums, many small company directors strategically set their salary at the £12,570 tax-free personal allowance for maximum efficiency. You can discover more insights about this strategic pay difference in the full BDO report.
Finally, don’t treat the company account like your personal piggy bank. Mixing business and personal spending is a recipe for disaster and makes your accounts a nightmare for anyone to unpick.
These pitfalls are precisely why having a good accountant is a game-changer. They aren’t just a cost; they are an investment in your financial peace of mind. Speak to our friendly team at Artema to ensure you're set up for success from day one.
Got Questions? We’ve Got Answers.
Still got a few things buzzing around your head? Don't worry, you're not the only one. Let's tackle some of the most common queries we hear from company directors about paying themselves.
Can I Pay Myself Only in Dividends and Skip the Salary?
Technically, you can, but it's rarely a smart move. Think of it like skipping the sensible main course and going straight for dessert.
Taking a small, tax-efficient salary is crucial because it helps you build up qualifying years for your State Pension. That’s a brilliant long-term benefit you get absolutely no credit for with dividends alone. For almost everyone, the salary-plus-dividend mix is the winning combination.
How Often Can I Take Dividends From My Company?
You can pay yourself dividends as often as you like—monthly, quarterly, or whenever you fancy a treat. There’s just one golden rule: your company must have enough post-tax profit to cover the payment each and every time.
Crucially, you need to complete the proper paperwork (board minutes and a dividend voucher) for every single payment. Staying consistent here is key to keeping HMRC happy and avoiding any nasty surprises down the line.
Getting the paperwork wrong is like forgetting to put the bins out—it seems minor at the time, but the consequences can get messy very quickly. A good accountant is like that friendly neighbour who reminds you which day it is.
Do I Really Need an Accountant for All This?
Honestly? Yes. While you could certainly try to DIY your payroll and dividends, tax rules are notoriously fiddly and seem to change with the seasons.
A good accountant acts as your financial co-pilot. They make sure you stay compliant, operate in the most tax-efficient way possible, and can sleep soundly at night. Think of their fee not as a cost, but as an investment in getting things right and saving you a potential fortune in mistakes.
Feeling clearer but want an expert to handle the details? The friendly team at Artema Ltd can build a perfect, tax-efficient pay strategy just for you. Get in touch with us today at https://www.artema.co.uk and let's get you paid properly.