
So, what on earth are management accounts? In a nutshell, they’re your business's financial health check. You pull together all your financial bits and bobs, make a few clever tweaks for things that haven't been billed yet, and then build your key reports – the Profit & Loss and the Balance Sheet.
Think of it as a real-time financial GPS for your business. Its whole job is to help you make smart decisions with up-to-date, accurate info. This isn't about boring paperwork for HMRC; it's about giving you a clear, honest look at what's really going on under the bonnet.
Why Management Accounts Are Your Business's Secret Weapon
Let's be honest, the term "management accounts" sounds a bit… stuffy. It probably brings to mind dusty ledgers and spreadsheets that could send you to sleep. But what if they’re actually the closest thing your business has to a crystal ball? Forget the jargon for a minute; these reports are your secret weapon for growth.
Trying to run a small company, manage a property portfolio, or grow as a sole trader without them is like driving from London to Edinburgh with a map from 1985. You might get there eventually, but you’ll almost certainly take a few wrong turns and run out of petrol somewhere near Birmingham.
A Clear View of Your Business Health
Management accounts are simply internal financial reports you prepare regularly—usually every month or quarter. Unlike the scary year-end accounts you send off to HMRC, these are for your eyes only. Their sole job is to give you an up-to-the-minute snapshot of how your business is really doing.
They're typically built around three core parts:
- The Profit & Loss (P&L) Statement: This is the big one. It tells you if you're actually making money by showing your income versus your expenses. Are you in the black or the red? This is where you find out.
- The Balance Sheet: Think of this as a financial selfie of your business on a single day. It lists everything you own (assets) and everything you owe (liabilities), giving you a clear picture of your net worth.
- The Cash Flow Forecast: You could argue this is the most important report for any small business. It tracks the actual cash moving in and out, making sure you have enough money in the bank to pay your bills, your staff, and most importantly, yourself.
From Numbers to Smart Decisions
The real magic happens when you start using these reports to make decisions. Are your marketing costs creeping up without a matching rise in sales? The P&L will shout about it. Is a major client consistently paying late and squeezing your cash flow? Your cash forecast will raise the alarm long before it becomes a full-blown crisis.
By looking at your management accounts each month, you stop reacting to problems and start predicting them. It's the difference between firefighting and cool, calm, strategic planning.
This guide is designed to make the whole process less painful. We'll walk you through each step, from gathering your data to presenting your findings in a way that actually makes sense. And no, you don't need an accounting degree, we promise.
Ready to take control of your financial future? Let’s dive in. And if you feel you need a co-pilot on this journey, don't hesitate to get in touch with us at Artema.
Organising Your Financial Puzzle Pieces
Before you can build a financial report that’s a thing of beauty, you need to find all the puzzle pieces. And let's be honest, some of them are probably hiding under the sofa.
Getting this data collection stage right is genuinely half the battle won. It turns a potentially chaotic task into a satisfyingly organised process, a bit like a chef getting all their ingredients ready before the cooking chaos begins. To prepare management accounts you can actually trust, you need a solid foundation of data.
Your Essential Data Gathering Checklist
The goal here is simple: gather every scrap of financial information for the period you're reviewing, whether it's the last month or the last quarter. Without this complete picture, your reports will have more holes than a block of Swiss cheese.
Start by pulling together the basics:
- Bank and Credit Card Statements: This is non-negotiable. Every single transaction from every business account needs to be accounted for.
- Sales Invoices: All the invoices you've sent out to customers, whether they've paid them yet or not. This is your income side of the story.
- Supplier Invoices and Receipts: Every bill you've received and every receipt for things you've paid for, from your big software subscription to that emergency pack of biscuits for the office.
- Payroll Information: Details of salaries paid, National Insurance contributions, and any pension payments.
This might sound like a lot of admin, but getting into a good routine makes it much easier. Keeping on top of your paperwork is a key part of how bookkeeping helps your business save time and money, preventing that mad panic at the end of each month.
A Little Tip for Xero Users
If you’re using accounting software like Xero, you have a huge head start. The bank feeds automatically pull in most of your transactions, which is a massive time-saver. However, automation isn't magic—it still needs a human touch.
Your main job in Xero is reconciliation. This just means matching every transaction from your bank feed to an invoice or receipt in the system. Your goal is to get that satisfying green tick that says your bank balance in Xero matches your actual bank balance. This is the only way to be 100% sure your data is accurate.
Think of an unreconciled transaction as a rogue puzzle piece from a different box. It just doesn't fit, and it will throw off the entire picture. Your job is to make sure every piece belongs and is placed correctly.
Don't Forget the Non-Financial Clues
Great management accounts tell a story, and sometimes numbers alone don't give the full plot. Adding a few key non-financial metrics can provide invaluable context.
Consider tracking things like:
- Customer Numbers: Did your new marketing campaign lead to a surge in new clients?
- Website Traffic: Is there a link between more visitors and higher sales?
- Project Hours (for service businesses): Are you spending more time on less profitable projects?
- Occupancy Rate (for landlords): How many of your properties were tenanted during the period?
These details help answer the "why" behind the numbers. A drop in profit might be worrying on its own, but if you can see it’s because you invested in a campaign that brought in 50 new long-term customers, the story changes completely. Gathering this extra info turns a simple financial report into a powerful business tool.
Diving into the Detail: Accruals and Adjustments
Okay, this is where we roll up our sleeves. You've gathered all the financial data from the month, but it's still just a pile of raw numbers – receipts, invoices, bank statements. The next step is what turns that raw data into genuine financial intelligence that tells you what’s really going on.
Don't worry, this isn't some dark art. It's simply about making a few clever tweaks called adjustments. These make sure the financial story you’re about to build is a true reflection of the month, not just a random snapshot.
Why Adjustments Are So Important
The whole point here is to correctly match your income and expenses to the period they actually belong to. If you skip this, your profit for one month might look fantastic, while the next looks dreadful, even if your business performance was perfectly steady. It’s all about getting an honest picture.
The two main players in this game are accruals and prepayments. They sound technical, but the ideas are actually quite simple.
-
Accruals: Think of these as expenses you've used but haven't been billed for yet. A classic example is your quarterly electricity bill. You used the power in January, but the invoice won't arrive until March. An accrual lets you account for January's share of that expected cost in January's accounts, avoiding a nasty surprise later.
-
Prepayments: This is the exact opposite. It's for things you've paid for upfront but haven't fully used yet. That annual insurance policy you paid for in January is a perfect example. It covers you for 12 months, so it wouldn't be fair to hit January's profits with the entire cost. A prepayment lets you spread that cost out, putting one-twelfth into each month.
Getting your head around these concepts is a massive step towards producing reliable reports. To dig deeper, our guide on what is accrual accounting breaks it all down even further.
The Non-Negotiable Bank Reconciliation
Before you go any further, there’s one job that is absolutely essential: the bank reconciliation. This is simply the process of making sure the balance in your accounting software (like Xero) perfectly matches the balance shown on your actual bank statement. I mean, down to the last penny.
If the numbers don't match, something is wrong. It could be a missed transaction, a duplicate entry, or a bank fee you overlooked. Finding and fixing these is vital for accuracy. An unreconciled bank account means your reports are being built on shaky ground.
Other Key Adjustments to Consider
Accruals and prepayments are the stars of the show, but a few other adjustments will make sure your management accounts are rock-solid.
Depreciation
If you bought a shiny new van or a powerful laptop for the business, you can't just expense the entire cost in the month you bought it. That asset has a useful life that stretches over several years. Depreciation is the fancy word for spreading the cost of that asset over its lifespan. For instance, a £30,000 van might be depreciated over five years, which would mean adding a £500 expense to your accounts each month.
Stock Adjustments
This is a critical one for any business holding physical stock, like a retailer or an e-commerce store. You must account for the value of the inventory you hold at the month's end. This usually involves counting your stock and then adjusting your books to reflect the correct value. This adjustment has a direct impact on your profit.
Putting these adjustments into practice is the foundation of a solid month-end routine. To master the process, it's worth exploring these month-end close best practices for improving both speed and accuracy. By taking the time to make these tweaks, you ensure the numbers you're about to put into your reports are a faithful reflection of your business's performance.
If this all feels a bit much, remember that help is at hand. Our team at Artema can handle these adjustments for you, ensuring your reports are spot-on every month. Reach out today for a friendly chat.
Building Your Core Financial Statements
Right, you’ve wrestled with the data, tidied up your transactions, and made all the necessary adjustments. Now for the satisfying part: creating the reports that actually tell you the story of your business.
This is where your hard work pays off, turning raw numbers into the two headline acts of management accounts: the Profit & Loss statement and the Balance Sheet.
Think of them as your business’s report card and a family photo. The first tells you how well you’ve performed over the last month, while the second gives you a snapshot of where everything stands at a single moment in time. Both are essential for understanding what’s really going on.
The Profit & Loss Statement: The Big Performance Review
The Profit & Loss (P&L) statement is usually the first report anyone looks at. Its job is simple: to show you whether you’ve made or lost money over a specific period. It does this by lining up all your income against all your expenses.
But a good P&L does more than just give you a single profit number at the bottom. It should be structured to reveal key insights along the way:
- Revenue (or Turnover): This is the top line, showing all the money you’ve earned from sales.
- Cost of Sales (or Cost of Goods Sold): These are the direct costs of making your sales. For a coffee shop, it’s the coffee beans and milk; for a landlord, it might be letting agent fees.
- Gross Profit: Simply your Revenue minus your Cost of Sales. It tells you how profitable your core business activity is before you account for your general running costs.
- Overheads (or Operating Expenses): These are all the other costs of keeping the lights on, like rent, salaries, marketing, and software subscriptions.
- Net Profit: This is the famous "bottom line." It’s what’s left after you subtract your overheads from your gross profit. This is the ultimate measure of your profitability for the period.
Understanding the difference between gross and net profit is vital. A healthy gross profit suggests your pricing is right, but if your net profit is tiny, it's a huge red flag that your overheads are eating up all your cash. For a deeper dive, check out our guide on how to read a profit and loss statement.
The Balance Sheet: A Financial Selfie
If the P&L is a video of your month’s trading, the Balance Sheet is a single, perfectly posed photograph. It shows your financial position on one specific day—usually the last day of the month. It doesn't track performance over time; it just answers the question, "What is the business worth right now?"
The entire Balance Sheet is built on one simple, unbreakable formula:
Assets = Liabilities + Equity
Let’s break that down without the jargon:
- Assets: Everything your business owns that has value. This includes cash in the bank, the value of your unsold stock, money owed to you by customers (debtors), and property or equipment.
- Liabilities: Everything your business owes to others. This includes bank loans, money you owe to suppliers (creditors), and looming tax bills.
- Equity: This is what's left over for the owners once you've paid off all your liabilities. It represents the net value of the business.
A healthy balance sheet shows that your assets are comfortably larger than your liabilities. It’s a powerful indicator of your financial stability. Before you can build these reports, though, you need to be sure your underlying numbers are solid.
This infographic is a great visual reminder of the crucial adjustment steps you must complete before putting these statements together.
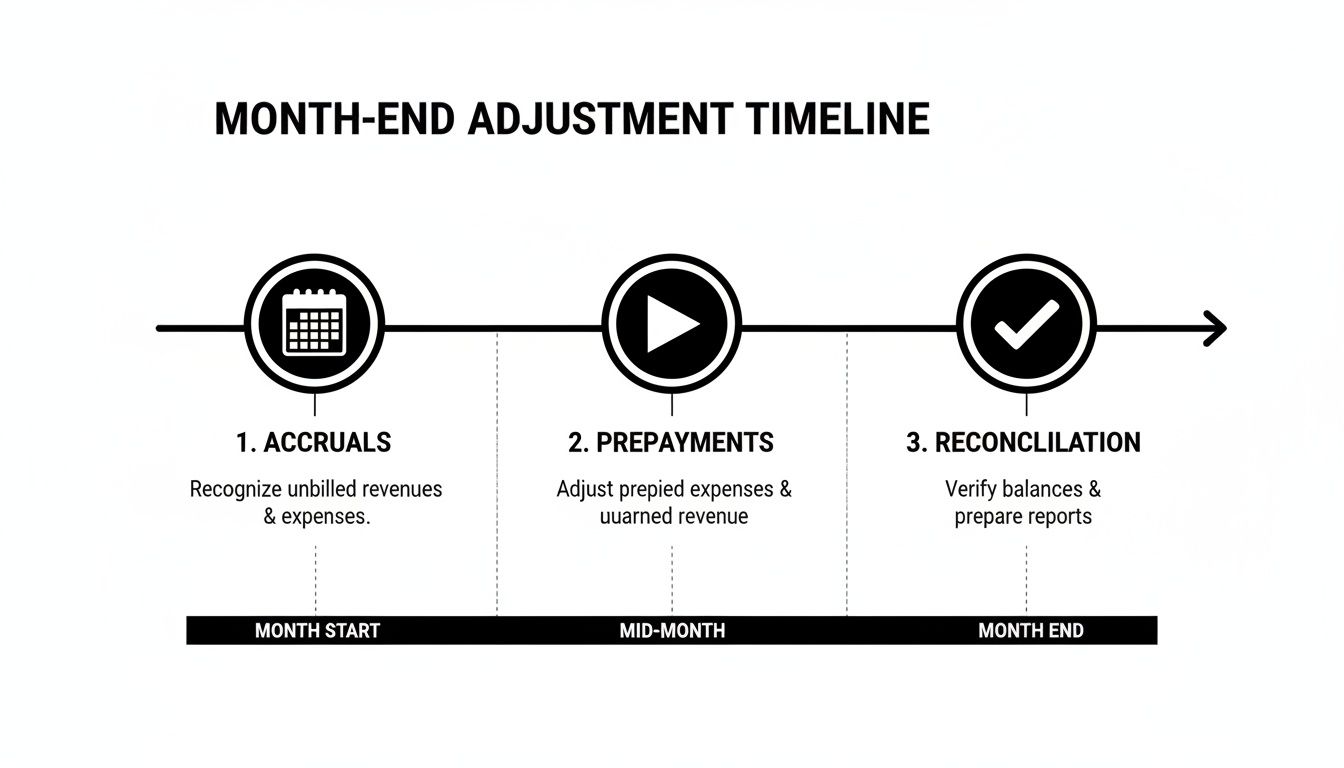
Following this flow from accruals and prepayments to a final reconciliation ensures the data feeding into your P&L and Balance Sheet is accurate and trustworthy.
Putting It All Together With a Solid Timetable
For any small business, a consistent routine is the key to staying on top of the numbers without it becoming a mammoth task. A simple weekly schedule can make all the difference and stop the month-end from becoming a mad dash.
Here’s a practical timetable you can adapt to fit your own business rhythm.
Your 7-Day Management Accounts Timetable
A structured weekly plan to keep your management accounts preparation on track and stress-free.
| Days | Key Tasks | Goal |
|---|---|---|
| Days 1-2 | Reconcile bank accounts & credit cards. Post all sales invoices & supplier bills. | Get all the core transactions for the period logged and matched up. |
| Days 3-4 | Post payroll journals. Calculate and post accruals for costs not yet billed. Adjust for any prepayments. | Account for the non-cash transactions and timing differences. |
| Day 5 | Review the draft P&L and Balance Sheet. Look for anything that seems odd or miscategorised. | A crucial sense-check before finalising the numbers. |
| Days 6-7 | Finalise the reports. Add commentary and compare against your budget. Share with your team. | Complete the accounts pack and turn the data into useful insights. |
Sticking to a schedule like this helps build a reliable process, meaning your reports are not only accurate but also delivered on time, every time.
Xero Tip: If you're using Xero, you're in luck. You can generate both the "Profit and Loss" and "Balance Sheet" reports with a few clicks from the Reporting menu. The key is to customise the date range to match your period (e.g., 1st to 31st January) and use the "compare with" feature to see how this month stacks up against the last.
Building these statements might seem daunting at first, but it’s the moment your financial data starts talking to you. It's the foundation for making genuinely smart business decisions.
Bringing Your Numbers to Life With Insights and KPIs
You’ve done the heavy lifting. The data is clean, the adjustments are in, and your reports are looking pristine. But let’s be brutally honest: for most people, a page full of numbers is about as exciting as watching paint dry. This is where you turn that dry report into a powerful tool for growth.
This is the moment you add the story and the meaning behind the figures. It’s the difference between being a number-cruncher and a savvy business owner. The goal now is to turn data into decisions by providing short, sharp insights that you and your team will actually look forward to reading.
Crafting a Simple, Powerful Commentary
Forget writing a novel. The best commentary is a simple one-pager that gets straight to the point. Nobody has the time, or the will to live, to read pages of dense analysis.
Your commentary should really just answer three simple questions:
- What went well? Did sales smash the target? Was the profit margin better than last month? Celebrate the wins and, more importantly, figure out why they happened so you can do it again.
- What didn't go so well? Were costs higher than you expected? Did a key client pay late, putting a squeeze on your cash? Be honest about the challenges.
- What are we doing about it next month? This is the most crucial part. It’s where you turn insights into action. Are you launching a new campaign to boost sales? Chasing down that late payment? This is what makes your accounts a forward-looking tool, not just a history lesson.
Think of your commentary as the executive summary of your business's month. If someone only read this single page, they should walk away knowing exactly where things stand and what the plan is.
To truly make the most of your financial data, it can be worth exploring how expert business intelligence consulting can help turn those raw numbers into strategic growth drivers.
Choosing KPIs That Actually Matter
Next up are Key Performance Indicators, or KPIs. It’s incredibly easy to get lost in a sea of metrics, tracking dozens of things that don't really move the needle. The trick is to pick a small handful—say, three to five—that are truly vital signs for your business's health.
What you track will be completely unique to you. A landlord's KPIs are worlds away from a tech startup's.
Here are a few real-world examples to get you thinking:
- For a Landlord: Rental Yield is king. It tells you the annual return on your property investment. You might also track the Occupancy Rate and Average Days Vacant.
- For a Small E-commerce Company: Customer Acquisition Cost (CAC) is crucial. How much does it cost to get a new customer? You’d also be watching Average Order Value (AOV) like a hawk.
- For a Sole Trader Consultant: Billable Hours is everything. What percentage of your time is spent on paid work? You’d also track your Day Rate and how much of your income comes from a single client.
The key here is relevance. Don't just track revenue because you think you should. Track the specific things that drive that revenue in your unique business.
Putting It Into Practice: A Landlord's Example
Let's imagine you're a landlord with a small portfolio of properties. Here’s how you could structure your simple one-page summary to be genuinely useful:
Monthly Commentary: January 2025
- What went well? We successfully let the flat at 23 Acacia Avenue after only five vacant days, well below our 14-day target. Gross rental income was £4,200, which is 100% of our potential for the month. High-five!
- What didn't go so well? We had an emergency plumbing repair at the Elm Street property costing £350, which was an unbudgeted expense. This pushed our maintenance costs 20% over budget. Ouch.
- What's the plan for February? We will review our maintenance budget to include a larger contingency going forward. We'll also start marketing the Maple Drive property a week earlier than planned to minimise any potential void period.
Key KPIs This Month
| KPI | Target | Actual | Notes |
|---|---|---|---|
| Gross Rental Yield | 5.5% | 5.8% | Performing above target due to strong rents. |
| Occupancy Rate | 98% | 100% | Fully occupied this month. |
| Debtor Days | < 5 days | 3 days | All rents collected promptly. Great job! |
This simple format gives a complete, actionable overview in minutes. When preparing management accounts, mastering how you track money owed to you is critical. For UK small business owners, effective debtor and creditor management is a key differentiator. Analysis shows that top accounting firms average 52 debtor days versus 88 for laggards, with the best performers keeping their entire cash cycle under 85 days while others struggle with over 135.
By adding this layer of insight, you're no longer just doing the accounts; you're using them to build a smarter, more resilient business.
Got Questions About Management Accounts? We’ve Got Answers
Stepping into management accounts can feel a bit like trying to assemble flat-pack furniture for the first time. You know the end result will be brilliant, but the instructions seem a little daunting at first glance. It’s completely normal to have a few questions.
So, let's clear the air. We’ve answered some of the most common queries we hear from business owners. Think of this as your practical, no-silly-questions-allowed guide.
How Often Should I Prepare Management Accounts?
For most small businesses, a monthly rhythm is the gold standard. It’s like a regular financial health check-up, helping you spot trends as they happen, fix small issues before they snowball, and generally keep your finger on the pulse of the business.
Now, if you’re a sole trader with fairly simple finances or a landlord with only one or two properties, a quarterly review might be all you need. The most important thing, though, is consistency. Sticking to a regular schedule, whatever that looks like for you, makes everything from VAT returns to your year-end accounts much less of a headache. No more nasty surprises hiding in the numbers!
What's the Difference Between Management and Statutory Accounts?
This is a classic question, but the answer is simpler than you might think. Imagine you’re cooking a big family meal.
Management accounts are like tasting the sauce as you go. You do it for yourself, right in the moment, to make sure everything’s on track. You can add a bit of salt, turn down the heat, or throw in some more herbs—all to make sure the final dish is perfect. They are for your eyes only, to help you make better decisions.
Statutory accounts, on the other hand, are the final, plated-up meal you present to your guests (in this case, Companies House and HMRC). They’re a formal, once-a-year requirement to show you’ve followed all the rules and paid the right amount of tax. One is for running the kitchen day-to-day; the other is for the official review.
Can I Prepare Management Accounts Myself Using Xero?
Absolutely! A tool like Xero is fantastic for this. Its reporting features can pull together your P&L and Balance Sheet in just a few clicks, doing a lot of the heavy lifting for you.
But the real value isn’t just in clicking the "run report" button. The skill is in knowing what adjustments to make before you run it—things like spotting the need for an accrual for a big bill you haven't received yet, or calculating depreciation on your new laptop. It’s also about interpreting what the numbers are actually telling you.
While you can certainly do it yourself, working with an accountant guarantees complete accuracy, saves you a huge amount of time, and gives you an expert second opinion on what those figures really mean for your business's future.
What Are the Most Important Things to Look For?
When your reports are ready, it’s easy to get lost in the sea of numbers. My advice? Don't try to analyse every single line. Instead, zoom in on the three areas that tell you almost everything you need to know:
- Profitability: Are we actually making more than we’re spending? Check your net profit and see how it compares to last month and the same time last year. Is it heading in the right direction?
- Cash Flow: Is there enough cash in the bank to cover next month's payroll, rent, and tax bills? Profit on paper is one thing, but actual cash is what keeps the lights on.
- Balance Sheet Health: How do our assets (what we own) compare to our liabilities (what we owe)? This gives you a brilliant snapshot of your business’s overall financial stability.
Keeping an eye on these three core elements over time is the key. It helps you understand where your business is heading and empowers you to make much smarter decisions.
Feeling ready to take control but want a trusted co-pilot? At Artema Ltd, we specialise in turning financial data into clear, actionable insights for sole traders, landlords, and small businesses. We handle the numbers, so you can focus on growth. Let's have a chat about how we can help.