
Ever wondered how you can get in on the ground floor of the next big thing before it becomes a household name? That's the whole idea behind a Venture Capital Trust, or VCT for short. It's like being in the "cool kids club" of investing, but with better tax breaks.
Investing in a VCT means you're buying shares in a specialised investment company. This company pools your money with others to back a portfolio of young, high-growth UK businesses. It’s your ticket to the exciting world of startups, but with the added kick of some seriously good tax reliefs designed to soften the risk and hopefully boost your returns.
What Are Venture Capital Trusts Anyway?
At its heart, a VCT is a company listed on the London Stock Exchange that you can invest in, just like any other share. Simple enough, right?
The real magic happens behind the scenes. Instead of buying into massive, established corporations, the VCT manager uses the pooled funds to build a hand-picked portfolio of small, ambitious, and unlisted UK companies. Think of it like being a dragon in the den, but without having to sit through a dozen pitches for questionable kitchen gadgets.
The government is a big fan of this setup. These small, innovative companies are the engine of the UK economy—they create jobs, develop new technologies, and drive growth. To encourage private investors to back these ventures, the government offers some seriously attractive tax breaks to make it all worthwhile.
Fuelling the UK's Innovators
This isn’t just some niche investment idea; it’s a powerful way to boost the UK economy. Since they were launched back in 1995, VCTs have funnelled over £12 billion into UK startups. They’ve helped create some of the country's most well-known success stories, including the likes of Depop and Zoopla.
The whole structure was designed to get private money flowing into small businesses by offering brilliant tax reliefs—like 30% upfront income tax relief—which helps cushion the inherent risk for investors.
A Venture Capital Trust is essentially a curated playlist of exciting, young UK companies with massive growth potential, all bundled into one investment. You're pooling your money with others to back the innovators and disruptors of tomorrow.
It's a win-win. Ambitious entrepreneurs get the cash they need to grow their businesses, and you get access to a diversified portfolio of high-potential companies that would be almost impossible to invest in on your own.
Understanding the Investment Landscape
So, where do VCTs fit into your broader financial plan? They certainly aren't your typical stocks and shares ISA. VCTs fall squarely into the category of 'alternative investments'. This simply means they operate outside the conventional world of stocks, bonds, and cash.
That classification is important because it highlights their unique risk-and-reward profile. For a bit more context on this corner of the market, it’s worth reading a guide on understanding alternative investments.
To give you a clearer picture, let's quickly break down the core features of a VCT and what they mean for you as an investor.
VCTs at a Glance: Key Features and Investor Profile
| Feature | What It Means For You |
|---|---|
| High-Growth Focus | Your money is directed towards small, private companies with the potential for rapid expansion and, hopefully, significant returns. |
| Diversification | Instead of putting all your eggs in one startup basket, your investment is spread across dozens of companies, which helps spread the risk. |
| Professional Management | A dedicated fund manager does all the heavy lifting—finding, vetting, and managing the investments within the portfolio. Phew! |
| Tax Efficiency | The generous tax reliefs are a central feature, designed specifically to compensate for the higher risks involved. |
This table should give you a good snapshot of what you're getting into. VCTs are not for everyone, but for the right investor, they offer a unique combination of high-growth potential and tax advantages.
Ready to dive deeper and see if this high-growth world is the right fit for your portfolio? Let's get into the juicy details of those tax benefits in the next section.
Understanding The Generous Tax Benefits of VCTs
Right, let’s get to the part that makes everyone sit up and pay attention. While the idea of backing the next big thing is exciting, the tax benefits are what truly make VCTs a compelling proposition.
Think of them as the government’s way of saying, "Thanks for taking a punt on our nation’s innovators; here’s a little something for your trouble."
And it’s not just a little something. These are some of the most generous tax reliefs available to UK investors, designed to sweeten the deal and cushion the higher risks involved. We’re going to break down the ‘big three’ tax reliefs without a shred of jargon.
The Headliner: The 30 Percent Upfront Income Tax Relief
This is the one that grabs all the headlines, and for good reason. When you invest in new VCT shares, you can claim back 30% of your investment amount against your income tax bill for that year. It's a direct reduction, not just a deduction from your taxable income.
So, if you invest £10,000 into a VCT, you can reduce your income tax liability by £3,000. If you go for a larger investment of, say, £50,000, that’s a £15,000 reduction. You can invest up to £200,000 each tax year and still get this relief, provided you have enough income tax to set it against. It’s a powerful way to make your money work harder from day one.
The Golden Rule: To keep this lovely tax relief, you must hold your VCT shares for at least five years. Sell before then, and you’ll have to repay it. It's the one condition you absolutely cannot forget.
To fully appreciate how this works, it helps to be clear on the basics. Many investors benefit from a deeper dive into understanding the difference between tax deductions and tax credits, as VCT relief acts like a credit, directly cutting your tax bill.
The Steady Bonus: Tax-Free Dividends
Here’s another fantastic perk. Any dividends paid out by your VCT are completely tax-free. That’s right, zero tax. They don't count towards your annual dividend allowance and you don't even need to declare them on your tax return.
This can be a real game-changer, especially for investors looking to generate a tax-efficient income stream. While dividends are never guaranteed (they depend on the success of the underlying companies), many established VCTs have a strong track record of paying them out.
Imagine your VCT portfolio pays a dividend yield of 5%. On a £100,000 investment, that’s £5,000 of income landing in your bank account each year, with the taxman not getting a single penny. It’s beautifully simple.
The Grand Finale: No Capital Gains Tax
Let's say the fund manager has done a brilliant job, the small companies in the portfolio have flourished, and your VCT shares have shot up in value. If you decide to sell them (after the five-year holding period, of course), any profit you make is entirely free from Capital Gains Tax (CGT).
In a world where CGT can take a significant bite out of your investment returns, this is a massive advantage. It means 100% of the growth is yours to keep.
Let’s put this all together with a quick example.
- Sarah's VCT Journey
- Sarah invests £20,000 into a new VCT share offer. She immediately claims £6,000 (30%) back on her income tax return.
- Over the next six years, the VCT pays an average dividend of 4% per year, giving her £800 annually, completely tax-free.
- After six years, the value of her shares has grown to £25,000. She sells them, making a £5,000 profit. This entire gain is exempt from Capital Gains Tax.
As you can see, the combined effect of these three tax reliefs is incredibly powerful. It's a structure designed to reward long-term investors who are willing to support the UK's growing businesses. For those interested in this area, exploring the nuances of EIS tax relief for tech businesses can provide a wider perspective on government-backed investment incentives.
The tax advantages are undeniably a huge draw, but it's vital to remember they exist to offset risk. Ready to explore what those risks are? Let's take an honest look in the next section.
The Risks and Realities of VCT Investing
Alright, let's pull up a chair and have an honest chat. We've gone over the dazzling tax breaks, and it's easy to get swept up in the excitement. But before you start picturing yourself on a yacht funded by startup success, we need to read the massive warning label that comes with investing in VCTs.
This is the "read the manual before flying the rocket" part of the guide. Investing in venture capital trusts is firmly in the high-risk, high-reward camp. Our goal isn't to scare you off, but to arm you with a clear, 360-degree view so you can make a decision with your eyes wide open.
Not All Heroes Wear Capes
The heart of any VCT is its portfolio of small, ambitious companies. The dream is that one of them becomes the next big thing, delivering incredible returns. The reality? Many startups simply don't make it. It’s just the nature of the beast.
For every success story you read about, there are several companies that will likely struggle or fail entirely. A good fund manager plans for this, banking on the winners to more than make up for the losers. But you have to be comfortable with the very real possibility that parts of your investment will go to zero.
Key Takeaway: A VCT's success hinges on a few star performers offsetting the inevitable failures in its portfolio. You are backing innovation, and innovation involves a lot of trial and, yes, error.
The Liquidity Labyrinth
Unlike shares in a FTSE 100 company, you can't just log into an app and sell your VCT shares in a few clicks. Cashing out is a different ball game entirely.
Because VCTs invest in private companies, their own shares are considered illiquid. This simply means there isn't a bustling market of buyers waiting to snap them up. To sell, you typically have two main routes:
- Secondary Market: Selling to another investor can be a slow process, and you might have to offer your shares at a significant discount to their value just to attract a buyer.
- VCT Buyback Schemes: Many VCTs offer to buy back their own shares, but this is always at their discretion and usually comes with a discount of around 5-10%.
Remember that five-year rule we talked about? It's there for a reason. You need to be prepared to lock your money away for at least that long, and quite possibly longer if you want to exit gracefully. This is absolutely not your emergency fund.
Market Mood Swings and Regulatory Shifts
The VCT market isn't immune to wider economic sentiment. Investor confidence can wax and wane, which affects how much new money is raised by the trusts. For instance, in the 2023 to 2024 tax year, VCTs raised £873 million—a 17% drop from the previous year. This shows just how much broader economic factors can influence the market. You can explore more about these trends in the latest government statistics on Venture Capital Trusts.
On top of that, the rules governing VCTs are set by the government. While they've been a staple of the UK investment scene for decades, there's always a chance that a future government could change the tax reliefs or investment criteria. This regulatory risk is small but ever-present.
The risks are real, but they are part of the package. By understanding them, you can decide if the potential rewards—and those tempting tax reliefs—make it a worthwhile venture for your portfolio.
If you’re considering how to balance these risks, our team at Artema can help you assess how an investment like a VCT might fit within your broader financial strategy. Let's chat about making informed decisions for your future.
How to Choose the Right VCT For Your Portfolio
Right, you’re sold on the concept, you understand the risks, and you've decided to invest in venture capital trusts. Brilliant. Now you face the next challenge: with dozens of VCTs all vying for your attention, how on earth do you pick a winner?
It’s a bit like choosing a new series to binge-watch. You wouldn't just pick the first one you see; you’d check the genre, look at the cast's track record, and maybe even read a few reviews. Choosing a VCT requires a similar approach to separate the blockbusters from the flops.
Generalist vs Specialist Funds
First things first, not all VCTs are created equal. They generally fall into two main categories, and knowing the difference is your starting point.
To help you decide, here’s a quick comparison of what makes each type tick.
Comparing VCT Types: Generalist vs Specialist
This table breaks down the key differences between generalist and specialist VCTs, which should help you figure out which one aligns better with your own risk appetite and investment goals.
| Feature | Generalist VCT | Specialist VCT |
|---|---|---|
| Investment Scope | Invests across a wide range of sectors (tech, healthcare, retail, etc.). A bit of everything! | Focuses on a single industry, such as renewable energy or fintech. All in on one theme. |
| Diversification | High. Spreads risk across multiple industries. | Low. Concentrated in one sector, making it more vulnerable to industry-specific downturns. |
| Risk Level | Generally lower risk due to diversification. | Higher risk but potentially higher reward if the chosen sector performs well. |
| Investor Profile | Suits investors looking for broad exposure to UK startups without specific industry knowledge. | Ideal for investors who have a strong belief in a particular sector's growth potential. |
Essentially, your choice comes down to your personal comfort level. Do you prefer a broader, more balanced approach, or are you happy to make a concentrated bet on a specific industry you believe in? There's no right or wrong answer; it's all about what aligns with your investment style.
Your VCT Selection Checklist
Once you've decided on the type of fund, it's time to dig into the specifics. You don't need to be a financial analyst, but there are a few key things you absolutely must check before you commit your hard-earned cash.
This decision tree gives a quick gut-check on whether you're ready for the VCT journey and its inherent risks.
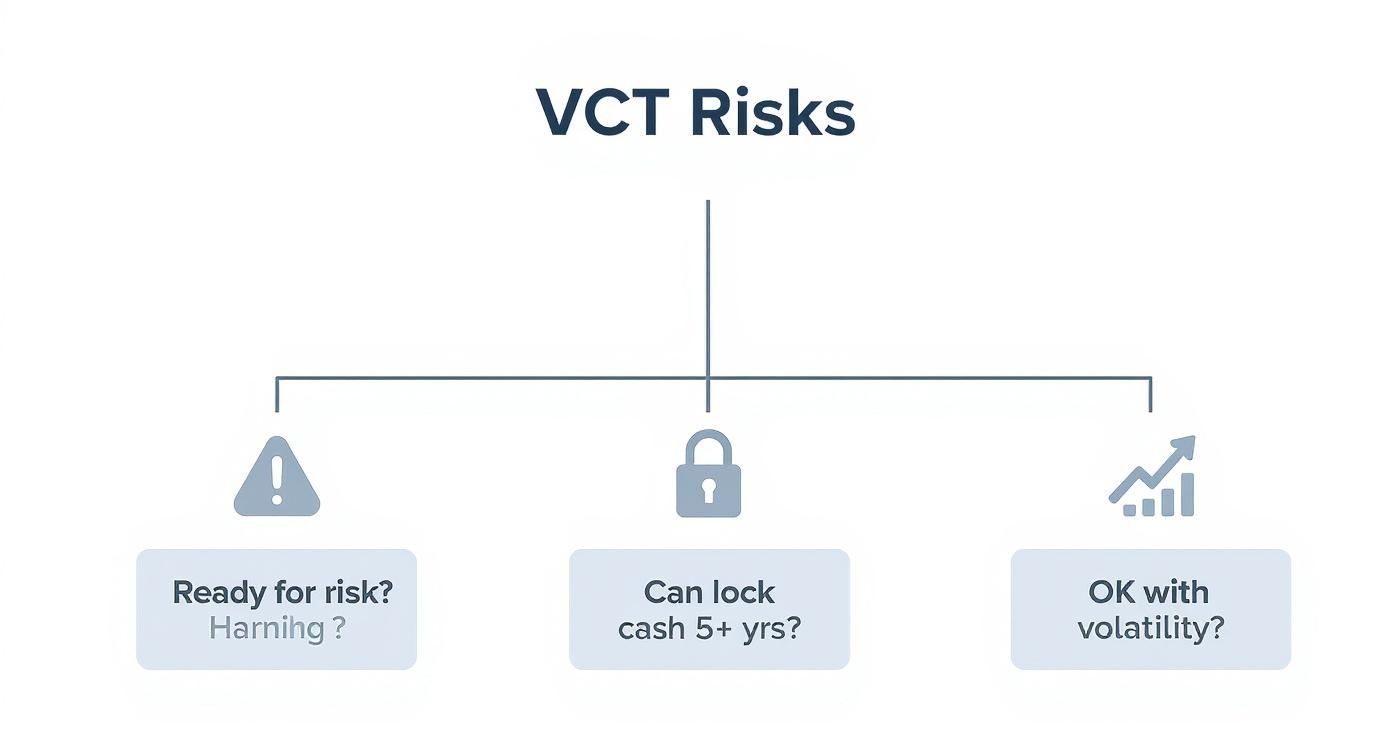
As the visual highlights, VCTs are for those who are comfortable with risk, a long-term commitment, and market ups and downs. If you've ticked those boxes, here's what to look at next.
The Fund Manager’s Track Record
This is arguably the most important factor. You’re not just investing in companies; you’re backing the judgement of the fund manager. You want to see a team with a long, consistent history of successfully picking and nurturing small businesses.
Ask yourself these questions:
- How long has the manager been running VCTs?
- What does their performance look like over the last five or ten years?
- Have they successfully navigated different economic cycles?
Seasoned pros who have been in the game for a while are generally a safer bet than newcomers.
The Investment Strategy and Dividend Policy
Every VCT should have a clear document explaining its investment strategy. This will tell you what kind of companies they back (e.g., early-stage, more established), what their growth targets are, and how they plan to deliver returns.
Also, check the dividend policy. Some VCTs aim to pay a regular, steady dividend, which is great for income seekers. Others focus purely on capital growth, reinvesting any profits to try and maximise the final share price. Make sure their goal matches yours.
Don't Forget the Fees
VCTs are not cheap to run. There are costs for finding deals, performing due diligence, and managing the portfolio companies. These fees will eat into your returns, so you need to know what they are.
Look for the Annual Management Charge (AMC) and any performance fees. While you shouldn’t just pick the cheapest, be wary of exceptionally high charges that aren't justified by stellar performance.
The good news is that strong performance can more than justify the costs. Historically, UK venture capital funds have delivered competitive long-term returns, though performance varies wildly between funds. Research shows that from 2002 to the end of 2023, UK VC funds achieved an average annual return of 11.2%, with the top-performing funds delivering much more.
Picking the right VCT is about matching the fund's strategy, risk profile, and management team with your own financial goals. It pays to do your homework.
Navigating these options can feel overwhelming, especially when trying to align them with your wider financial picture. If you're looking for guidance on building a robust portfolio, exploring expert wealth management in Bournemouth could provide the clarity you need. A professional can help you assess different VCT offers in the context of your overall financial plan.
Ultimately, choosing a VCT is a personal decision. Take your time, read the provider literature thoroughly, and don't be afraid to ask questions. Your future self will thank you for it.
Getting Your First VCT Investment Sorted: The Practical Steps
You’ve done the research, weighed the pros and cons, and you’re ready to take the plunge. Fantastic! But what now? This is where the theory ends and the practical, button-clicking part begins. Don’t worry, you won’t need a degree in finance to get this done.
Let’s walk through the actual process to invest in venture capital trusts, from finding an open offer to claiming that well-deserved tax relief.
Finding Your VCT and Making the Investment
First up, you need to find VCTs that are actually open for new investment. Most have a limited window each year, often running from autumn until the tax year wraps up on 5th April. There are three main ways you can go about it.
- Directly with the Fund Manager: You can go straight to the source and apply on the VCT manager’s website. This is often the most straightforward route if you know exactly which VCT you want.
- Through a Financial Adviser: If you’re feeling a bit overwhelmed, a financial adviser can recommend suitable VCTs based on your circumstances and handle the application for you. This is the best option for personalised advice.
- Via an Investment Platform: Many online platforms now offer access to VCTs. This can be a convenient way to keep all your investments in one place, but make sure you check their fees.
Once you’ve chosen your path, the process is pretty standard. You'll need to fill out an application form (online or paper), provide proof of your identity and address, and transfer the funds. It’s no more complicated than opening a new bank account.
The Timeline From Application to Tax Relief
Patience is a virtue, especially when dealing with paperwork. After you’ve sent off your application and money, a few things will happen in sequence. It's not instant, so don’t panic if you don’t hear back overnight.
First, your application will be processed and, if accepted, the VCT manager will allot your shares. This can take a few weeks, especially during the busy end-of-tax-year period.
Next, you will receive a share certificate and a tax certificate in the post. Guard these documents with your life—or at least file them somewhere very, very safe. You will absolutely need the tax certificate to claim your income tax relief.
Pro Tip: Don't be the person scrambling on 4th April. Popular VCT offers can and do sell out well before the tax year deadline. Aim to get your investment sorted by January or February to avoid disappointment and the last-minute rush. It's like booking a holiday—the early bird gets the best deals (and less stress).
Claiming Your 30 Percent Tax Relief
Now for the best part: getting your money back from HMRC. That lovely 30% income tax relief doesn't happen automatically; you have to claim it.
You do this via your annual Self-Assessment tax return. On the 'Additional Information' pages, you'll find a section for 'Other tax reliefs'. Here, you'll enter the total amount you’ve invested into VCTs for that tax year. Your tax certificate will have all the details you need.
Once you submit your tax return, HMRC will process the claim. They will either adjust your tax code for the following year (meaning you pay less tax each month) or issue you a direct repayment if you’ve already overpaid. Either way, that 30% comes right back to you.
And that’s it! You’re officially a VCT investor, backing Britain's next generation of innovative companies. Following these practical steps demystifies the process, making it an accessible journey for informed investors. If you're looking for guidance on how this fits into your overall tax planning, our team at Artema is here to help you make sense of it all.
Common Questions About Investing in VCTs
Right, let's round things off with a few common questions that always seem to pop up when people first look into Venture Capital Trusts. Think of this as a handy FAQ to clear up those final lingering thoughts before you take the next step.
What's the Minimum I Can Invest?
This is a classic "how long is a piece of string?" question, as the minimum investment really does vary between different VCTs. The good news is, you don't need to be a millionaire to get started.
Generally, you'll find that most VCTs set their minimum investment level somewhere between £3,000 and £6,000. It’s always clearly stated in the offer document, so you’ll know exactly what the entry point is before committing any money.
Can I Put a VCT Inside My ISA?
A very sensible question, but the answer is a straightforward no. VCTs and ISAs are two completely separate tax-efficient wrappers, each with their own unique set of rules and benefits. You can't hold VCT shares within an ISA.
Think of them as different tools for different jobs. While you can't combine them, they can work brilliantly alongside each other as part of a wider investment strategy. For more on this, you can learn about choosing the right savings product with our guide comparing different types of ISAs.
What Happens After the Five-Year Holding Period?
Congratulations, you’ve made it past the five-year mark! You've now officially secured your 30% income tax relief. So, what now? You have a few options on the table.
- Hold On: You can simply continue to hold your shares. Many investors do this to keep receiving those lovely tax-free dividends for years to come.
- Sell Up: You can sell your shares and any profit you've made is completely free of Capital Gains Tax. As we've covered, this usually involves selling on the secondary market or through a VCT’s own buyback scheme.
The five-year rule is the most important milestone. Once you pass it, you gain full flexibility over your investment without having to worry about repaying that initial tax relief.
Do I Have to Be a High-Net-Worth Individual?
Absolutely not. While VCTs are higher-risk and often appeal to more experienced investors, there are no formal wealth requirements to invest in them. The key thing is that you understand and are comfortable with the risks involved.
You must be okay with the possibility of losing your capital and be prepared to lock your money away for at least five years. If you tick those boxes, VCTs are accessible to any UK taxpayer looking for growth potential and tax efficiency.
The journey to invest in venture capital trusts might seem complex at first, but once you break it down, it's a manageable and potentially rewarding path for the right kind of investor.
Navigating the world of VCTs, tax reliefs, and long-term financial planning can be a lot to handle on your own. At Artema Ltd, we specialise in helping investors like you make sense of it all. Let's talk about how we can support your financial goals.