
So, you're wondering: is property the best investment you can make? The honest answer is a bit like asking if a dog is the best pet—it really depends on whether you're ready for the commitment, the muddy paws, and the occasional chewed-up slipper. For many, property feels solid and dependable; you can see it, touch it, and it has a great track record for building wealth. But it’s no golden ticket and definitely demands more hands-on effort than just clicking a button on a stock app.
So, Is Property the Best Investment for You?
You want to know if putting your hard-earned cash into bricks and mortar is the smartest move. It’s a huge question, and there’s no simple yes or no. For a lot of people, the idea of owning a physical thing is incredibly appealing. Unlike stocks that can feel a bit like Monopoly money on a screen, a property is real—it provides a home for a family or a base for a business.
This feeling of security is a massive draw. You can collect rent, which gives you a steady income, and hopefully watch its value climb over the years. But let's not get carried away. It’s not all passive income and watching the money roll in from a beach somewhere in Spain.
A Quick Reality Check
Property investment is an active sport. It comes with chunky upfront costs like stamp duty, legal fees, and survey costs, and that's before you've even found a deposit. Then you’ve got the ongoing fun—leaky taps, broken boilers, and finding tenants who won't turn your lovely flat into a scene from a rockumentary. It can quickly turn into a part-time job you never signed up for.
Investing in property is often compared to planting a tree. It takes a big effort upfront and needs regular care, but with a bit of luck and patience, it can grow into something substantial that provides shelter and value for years to come.
This guide ditches the confusing financial jargon to compare property head-to-head with stocks, bonds, and cash. We'll explore the real costs, potential rewards, and hidden risks to help you decide. A key part of answering "Is property the best investment for you?" is understanding the crucial tax deductions for real estate investors, which can seriously boost your returns.
An Overview of Your Options
Before we dive deep, let's set the stage with a quick look at the main contenders for your money. This table gives a simple snapshot of where your cash could go.
Quick Look: Property vs Other Investments
| Investment Type | What You Own | Typical Return Source | Effort Level |
|---|---|---|---|
| Property | A physical building or land | Rental income & capital growth | High |
| Stocks & Shares | A tiny piece of a company | Dividends & share price growth | Low to Medium |
| Bonds | A loan to a government or company | Fixed interest payments | Low |
| Cash | Money in a savings account or ISA | Interest earned | Very Low |
The table above is a starting point. As you can see, property stands out for its hands-on, get-stuck-in nature.
The UK real estate market continues to be a major player. In the third quarter of 2025 alone, commercial real estate investment in the UK totalled a whopping £9.8 billion. On top of that, market experts project that UK property returns are expected to average around 8% annually over the next five years, which stacks up nicely against other assets.
Our goal here is to give you a clear framework to decide if property is the champion investment for your financial journey. Ready to find out? Let’s get started.
Understanding Your Main Investment Options
Before we can properly weigh up property against other assets, we need a clear picture of the main contenders for your capital. Every investor's situation is different, so getting to know the personality of each option is the first step in deciding where property fits into your own financial plan.
First, we have Property. This is the classic bricks-and-mortar investment – the tangible asset you can see and touch, whether that’s a two-bed flat in Manchester or a commercial unit in Bristol. For many UK investors, its physical nature provides a real sense of security. It feels, well, real.
Then there are Stocks & Shares. When you buy shares, you're owning tiny pieces of big companies like Tesco, BP, or Apple. Their value can climb impressively, but they're also prone to mood swings based on market news, making them one of the more exciting (and sometimes terrifying) options.
The Steady Contenders
Next up are Bonds. In simple terms, buying a bond means you're lending money to a government or a big corporation. In return, they promise to pay you back with regular interest. Bonds don’t usually offer the dramatic growth of stocks, but their reliability makes them a popular choice for more cautious folks.
Finally, there’s good old Cash held in a savings account or an ISA. Think of cash as the sensible shoes of your financial wardrobe. It’s safe, accessible, and always there when you need it. However, its main job is to keep your money safe, not to make it grow, and its value can get nibbled away by inflation over time.
A great financial plan isn't about picking a single 'winner'. It's about building a balanced team where different investments work together to help you score your goals.
How Has Property Performed Recently?
So, where does property sit in all this? While it's often seen as a slow-and-steady asset, its recent performance shows it can still pack a punch. In the 12 months leading up to February 2025, for example, UK real estate produced a total return of 8.1%.
Crucially, this figure was heavily driven by rental income, not just soaring house prices. The residential sector was a particularly strong performer, posting an 8.8% total return thanks to rental growth that comfortably outpaced inflation. This highlights an important point: even if house prices are a bit flat, the income from tenants can make property a very compelling investment. You can read a more detailed analysis in this UK real estate market outlook for Q2 2025.
Now that we've introduced the key players, you have a better sense of the investment field. But knowing what they are is just the start. The real test is how they stack up against each other.
Ready to see how they compare on everything from risk and return to costs and tax? Let’s get into the nitty-gritty. And if you need a hand figuring out how these options could work for you, our friendly team at Artema is here to help you make sense of the numbers.
Comparing Property vs Stocks and Other Assets
Alright, time for the main event: the investment smackdown! Pitting property against stocks, bonds, and cash isn't about finding a single winner for everyone. It's about understanding where each one shines and how they fit your personal goals. Answering "is property the best investment?" means seeing how it performs on the factors that truly matter.
Let's start with historical returns. Over the long haul, both property and stocks have proven to be powerful wealth-building engines, typically leaving bonds and cash in their dust. Property generates returns through rental income and its value going up, while stocks give you dividends and share price growth.
Historically, both deliver strong results, but they behave very differently depending on the economic climate. Property often provides a more predictable, steady income stream through rent, which can be a real comfort blanket during turbulent times.
The Volatility Factor: Who Gives You a Good Night's Sleep?
Next up is volatility—just a fancy word for how much an investment's value bounces around. This is where property and stocks really show their different personalities. Stock markets can be drama queens, with prices swinging wildly based on daily news, economic reports, or even a single tweet.
Property, on the other hand, is generally far less dramatic. House prices don't typically crash overnight. This slower pace provides a psychological comfort that many investors appreciate, stopping them from panic-selling during market wobbles.
While stocks offer the thrill of a rollercoaster, property offers the comfort of a scenic train journey. Your choice depends on what kind of ride you're looking for.
This chart shows the kind of steady returns property can deliver, even in a changing market.
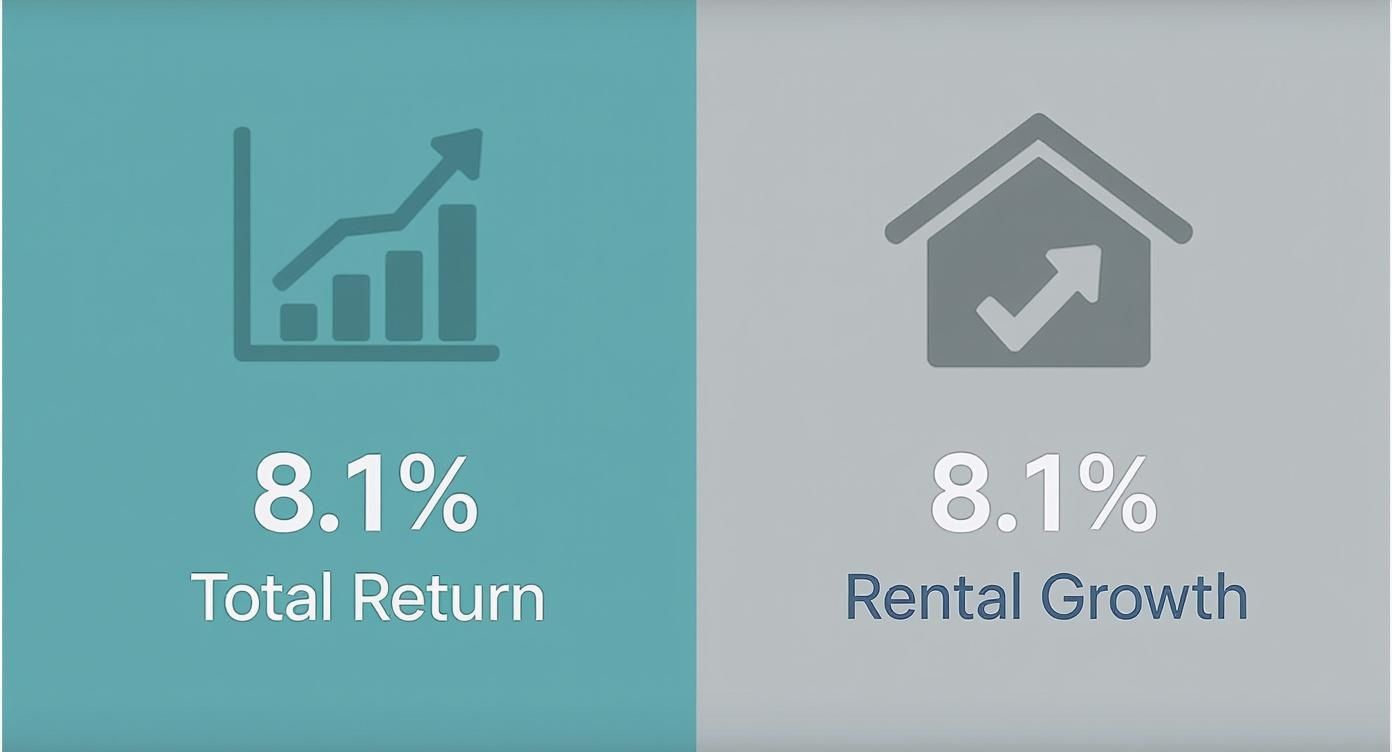
The data shows a healthy 8.1% total return, driven by both property value growth and strong, consistent rental income. That’s the kind of dependable performance many people are looking for.
Liquidity: How Fast Can You Get Your Cash Back?
Let's talk about liquidity—how quickly you can turn your asset into cash. If stocks are a speedboat, property is more like an oil tanker. You can sell your shares with a few clicks and have the money in your bank account within days.
Selling a property, however, is a marathon, not a sprint. It involves estate agents, solicitors, endless viewings, and a chain of buyers that can collapse at any moment. This lack of liquidity is one of property’s biggest drawbacks; if you need money in a hurry, you're pretty much stuck.
Leverage: The Superpower of Property Investment
Here’s where property has a unique superpower: leverage. This is the ability to use borrowed money (a mortgage) to buy a much bigger asset. With a relatively small deposit, say £25,000, you could get a mortgage to buy a £250,000 property.
If that property's value increases by 10% to £275,000, your initial investment has effectively doubled your equity to £50,000 (minus costs). You simply can't do this with stocks unless you get into very risky territory. Leverage can seriously supercharge your returns, but be warned—it also magnifies your losses if the market turns against you.
Costs of Entry and Ongoing Fees
Getting into the property game isn't cheap. The upfront costs can be eye-watering and include:
- Stamp Duty: A tax paid on property purchases in the UK.
- Solicitor Fees: For all the legal paperwork.
- Survey Costs: To make sure the building isn't about to fall down.
- Mortgage Arrangement Fees: Charged by the lender for the privilege of lending to you.
In contrast, buying stocks is far simpler and cheaper. You can start with as little as £1, and platform fees are usually a tiny percentage of your investment. Property also comes with ongoing costs like maintenance, insurance, and letting agent fees that stock investors don't have to worry about.
A Quick Word on UK Tax Implications
Finally, let’s touch on tax, because the taxman always wants his share. When you sell an investment for a profit, you’re liable for Capital Gains Tax (CGT). The rules and rates can differ significantly between property and other assets.
For property investors, getting your head around the tax side is vital, especially for buy-to-let landlords. If you sell a second home or rental property, the profit will be subject to CGT. It’s a complex area, and knowing your obligations is key. You can learn more by checking out this helpful guide on what the Capital Gain Tax rate is and how it applies to you. Proper tax planning can make a huge difference to your final returns.
Investment Smackdown: Property vs Stocks vs Bonds vs Cash
To make sense of it all, here's a side-by-side look at how these four main investments stack up against each other.
| Feature | Property | Stocks & Shares | Bonds | Cash |
|---|---|---|---|---|
| Potential Return | High. Driven by rental income and capital appreciation. | High. Potential for significant growth through share price increases and dividends. | Low to Moderate. Fixed interest payments (coupon). | Very Low. Interest from savings accounts, often below inflation. |
| Risk Level | Moderate. Less volatile than stocks, but market downturns and tenant issues exist. | High. Market can be very volatile; prices can swing dramatically in the short term. | Low. Generally safer, especially government bonds, but not risk-free. | Very Low. Your capital is generally safe (e.g., FSCS protection). |
| Liquidity | Very Low. Selling can take months and is a complex, costly process. | High. Can be bought and sold within days, sometimes instantly. | Moderate. Can be sold, but might not be as quick or easy as stocks. | Very High. Instantly accessible. |
| Leverage | High. Mortgages allow you to control a large asset with a small deposit. | Low. Possible via margin trading, but this is very high-risk and not for beginners. | None. You can't borrow to buy bonds in the same way. | None. You can't leverage cash. |
| Entry Costs | High. Stamp duty, legal fees, surveys, and a large deposit are required. | Very Low. Can start investing with just a few pounds. | Low. Can be bought through funds with low minimum investments. | None. No cost to open a savings account. |
| Ongoing Costs | Moderate to High. Maintenance, insurance, letting fees, and mortgage interest. | Low. Platform fees and fund management charges. | Low. Typically just fund management fees. | None. No ongoing fees. |
| Tax (UK) | Complex. Income Tax on rent, CGT on sale, Stamp Duty on purchase. | Simpler. CGT on gains, tax on dividends (can be sheltered in an ISA). | Simpler. Interest is taxed as income, gains may be subject to CGT. | Simple. Interest is taxed as income (Personal Savings Allowance applies). |
This table lays bare the trade-offs. Property offers stability and the power of leverage, but at the cost of high entry fees and being hard to sell quickly. Stocks provide high growth potential and easy access, but you need the stomach for the ups and downs. It's never about which is 'best', but which is best for you.
Navigating the Risks of Different Investments
Every investment hero has a weakness, a sort of financial kryptonite. Believing any investment is a guaranteed win is the fastest way to lose your shirt. Understanding the potential pitfalls isn't about being pessimistic; it's about being smart and prepared.
Think of it as checking the weather before you leave the house—it helps you avoid getting soaked on your journey to financial growth. Let’s walk through some real-world risks you need to know about.
The Tangible Troubles of Property
With property, the risks feel very real because they often involve a physical problem. For landlords, a surprise boiler explosion in the dead of winter isn't just an inconvenience; it's an emergency repair bill that can gobble up months of profit in one go.
Then there's the human element. A dream tenant who pays on time is a joy, but you might also get one who decides paying rent is optional. This can lead to long, expensive eviction processes, leaving you out of pocket for months. On top of that, consider these factors:
- Market Downturns: An economic dip can pull house prices down with it, potentially leaving you in negative equity if you need to sell unexpectedly.
- Interest Rate Hikes: If you're on a variable-rate mortgage, a rise in interest rates means your monthly payments could jump, squeezing your cash flow.
- Void Periods: An empty property means no rent is coming in, but you're still on the hook for the mortgage, insurance, and council tax.
It's also crucial to remember that property performance isn't the same everywhere in the UK. Location is everything. Recent analysis shows homeowners in the East Midlands saw average inflation-adjusted gains of over 24% between 2011 and 2025. In stark contrast, during the 2021-2025 period, London property owners faced average inflation-adjusted losses of 13.42%. You can explore more about these regional differences in this detailed Sky News report.
The Digital Dangers of Stocks and Bonds
Shifting to stocks, the biggest risk is market volatility. Your portfolio’s value can plummet overnight due to a global event, a political announcement, or a big company having a bad day. One moment you feel like a financial genius; the next, you’re nervously checking your phone every five minutes.
While property moves like a tortoise, the stock market is a hare—capable of incredible sprints and sudden, heart-stopping tumbles.
"The stock market is a device for transferring money from the impatient to the patient." – Warren Buffett
This quote perfectly captures the psychological challenge. The biggest risk is often your own reaction—panicking and selling at the bottom of a downturn, which turns a temporary paper loss into a very real one.
Bonds, often seen as the safer cousins of stocks, have their own issues. Their main enemies are interest rate changes and inflation. If interest rates rise, newly issued bonds will offer better returns, making your existing, lower-rate bonds less attractive. At the same time, inflation can quietly eat away at your fixed returns, meaning the money you eventually get back buys less than it did before.
Preparing for the Unexpected
So, how do you handle these risks without hiding your money under the mattress? The first step is to accept they exist. For property investors, this means having a healthy emergency fund for repairs and planning for empty periods. Getting the tax side right is also essential. You might find our comprehensive guide on navigating buy-to-let taxes particularly useful for creating a resilient strategy.
For stock market investors, diversification is your best friend—don't put all your eggs in one basket. Spreading your money across different companies and industries helps soften the blow if one area performs poorly. Most importantly, invest for the long term and resist the urge to panic-sell. Every investment has its challenges, but with a clear understanding of the risks, you can build a strategy that stands strong, come rain or shine.
Finding the Right Investment for Your Personality
Deciding if property is the best investment isn’t just about the numbers; it’s also about knowing yourself. Your personality, lifestyle, and how you handle stress play a massive part in choosing something that won't give you sleepless nights. Let's find out if you and property are a match made in heaven or a disaster waiting to happen.
Think of it this way: investments are a bit like pets. Some people are perfectly happy with a low-maintenance goldfish, while others thrive on the chaos of training a boisterous puppy. There’s no right or wrong answer, only what’s right for you.
So, where do you fit in? Let's explore a few investor profiles to see which one sounds familiar.
The Property Investor Profiles
Property tends to attract certain types of people. If any of these sound like you, bricks and mortar might just be your thing.
-
The Hands-On Hero: Do you enjoy a good project? Do you own a toolbox and actually know how to use it? If the idea of fixing a leaky tap or dealing with tenants doesn't fill you with dread, property could be a great fit. This type of investor enjoys being actively involved and seeing the direct results of their efforts.
-
The Long-Term Legacy Builder: Are you playing the long game? If your goal is to build a stable, tangible asset to pass down to future generations, property is a classic choice. You're not fussed about quick wins; you value stability and are comfortable with your money being tied up for decades.
Property is brilliant for those who are in it for the long haul, comfortable with their money not being easily accessible, and keen to use leverage to build their wealth.
Who Might Be Better Suited to Other Assets?
On the flip side, property investment can feel like a ball and chain for other personality types. If these descriptions hit a little closer to home, you might find more joy (and less stress) with stocks and shares.
-
The Set-and-Forget Strategist: Does the thought of a late-night call about a broken boiler make you want to run for the hills? If you prefer a low-effort investment that you can check on occasionally without getting your hands dirty, a stock portfolio is likely more your speed. You can invest your money and let the market do its thing.
-
The Flexible Freedom-Seeker: Do you value having quick access to your cash? If you might need to pull your money out for a new business idea or a dream trip, property’s lack of liquidity will drive you nuts. The ability to sell stocks and have the funds in days offers a level of freedom property simply can't match.
Choosing an investment is like choosing a holiday. Some people love the predictability of an all-inclusive resort, while others crave the adventure of backpacking. Neither is 'better'—they just suit different people.
This isn’t about judging good or bad investors; it’s about honest self-assessment. Answering "is property the best investment?" starts with understanding your own financial personality and life goals.
Ready to take the next step? It's time to build a plan.
Making Your Decision and Taking Action
Feeling a bit clearer on your options? After comparing the contenders, weighing up the risks, and getting to know your investor personality, it’s time to shift from thinking to doing. It’s easy to get stuck in "analysis paralysis," endlessly reading articles without ever taking that first step. Think of this as your friendly nudge to actually make a plan.
The big question, "is property the best investment?" can only really be answered by you. It all boils down to your personal situation. To get to the heart of it, ask yourself some honest questions.
Your Personal Investment Checklist
Grab a pen (or open a new note on your phone) and jot down your answers to these. Don't overthink it; your first, honest response is usually the most telling.
- What’s your real appetite for risk? Are you genuinely okay with the ups and downs of the stock market for potentially higher gains, or does the very thought of a market dip make you feel a bit queasy?
- What’s your timeframe? Are you investing for a retirement that’s 30 years away, or are you hoping to use this money in five years?
- How much cash can you actually access? Property demands a hefty deposit, whereas you can start buying stocks for less than the price of a Friday night takeaway.
- How hands-on do you want to be? Do you fancy yourself as a landlord, dealing with tenants and repairs, or would you rather your investment quietly took care of itself?
Your answers will start to point you in a clear direction. There’s no single perfect investment out there, only the investment that's perfect for you.
Creating Your Action Plan
Based on your checklist, you probably have a gut feeling about which path suits you best. Now, let’s turn that feeling into a concrete plan.
If you’re leaning towards property:
Your homework starts now. Begin by researching promising UK locations, digging into rental yields and local demand. At the same time, get your own finances in order and chat with a mortgage advisor to see what you can realistically borrow. It’s also a great idea to explore the different strategies involved; our guide to buy-to-let solutions can give you a much clearer picture of what's involved.
If you’re leaning towards stocks:
Your first step is much simpler. Look into opening a Stocks and Shares ISA to make the most of your tax-free allowance. You can start with a small, regular investment into a low-cost index fund that simply tracks the market. It’s a brilliant way to dip your toe in the water without taking a huge plunge.
The best time to start investing was yesterday. The second-best time is today. Don't wait for the 'perfect' moment, because it doesn't exist.
Knowing When to Call for Backup
Let’s be honest, this stuff can get complicated, fast. While DIY investing is certainly possible, there are times when you really need to bring in the pros.
You should seriously consider talking to a financial advisor or an accountant if you’re dealing with a large sum of money, have complex tax affairs, or just feel completely out of your depth. They can help you build a sound strategy that's secure, tax-efficient, and perfectly aligned with your personal goals. Think of them as your financial co-pilot, there to help you navigate the journey with confidence.
Your Property Investing Questions, Answered
We’ve covered a lot of ground, but you’ve probably still got a few questions buzzing around. Let’s tackle some of the most common ones we hear from aspiring landlords and investors. Think of it as a final chat before you decide which investment league you want to play in.
Getting clear on these points is a great final step in figuring out if property really is the right fit for your circumstances.
Is Now a Good Time to Buy Property in the UK?
Ah, the million-pound question (sometimes literally). If you're waiting for a flashing neon sign that says "BUY NOW!", you could be waiting a very long time. The truth is, there's rarely a 'perfect' moment. The market is always moving, interest rates go up and down, and the economic news changes by the day.
Instead of trying to time the market, it’s far better to focus on your own financial readiness. A better question is, "Is now a good time for me to buy?" If you have a stable income, a solid deposit saved up, and a long-term mindset, then just about any time can be a good time. Property is a marathon, not a sprint.
How Much Money Do I Actually Need to Get Started?
Let's bust a myth: you don't need to be a millionaire, but you do need more than just spare change. The biggest hurdle is the deposit, which for a buy-to-let mortgage in the UK is typically 15-25% of the property’s value. So, for a £200,000 property, you’d need a deposit between £30,000 and £50,000.
But wait, there's more! You must budget for the extra costs that sneak up on you. These include:
- Stamp Duty: A significant tax on property purchases.
- Solicitor Fees: For all the legal heavy lifting.
- Survey and Mortgage Fees: To check the property is sound and to get your loan approved.
- Initial Refurbishment Costs: A pot of money to get it ready for tenants.
A good rule of thumb is to have an extra 5-10% of the property price set aside just for these fees.
What Are the Biggest Hidden Costs of Being a Landlord?
Once you own the property, the costs don't just stop. The most common surprises for new landlords are what I call the "three Vs": Voids, Vandals, and Vanishing tenants.
A void period is when the property is empty between tenants. That means zero rental income, but you still have to pay the mortgage and bills. You also need a healthy emergency fund for unexpected repairs – that boiler will almost certainly break on the coldest day of the year. It’s practically landlord law.
The most successful property investors aren't just buyers; they're business owners who plan for costs, manage risks, and focus on providing a quality home for their tenants.
Getting your head around these realities is crucial. It’s not about being put off, but about being properly prepared. Factoring these costs into your plan from day one is what helps ensure your investment remains profitable and as stress-free as it can be.
Still have questions? Deciding if property is the right investment for you is a major decision, and you don't have to make it alone. At Artema Ltd, we help landlords and investors make sense of the numbers, from tax planning to cash flow forecasting. Get in touch with us today to see how we can help you build a solid financial foundation for your investment journey.