
Being a landlord is a brilliant juggling act. You're constantly spinning plates—managing tenants, coordinating repairs, and wading through what feels like endless paperwork. But there's one ball you absolutely cannot afford to drop: the tax man's.
The good news? With a bit of know-how, you can handle your taxes confidently, legally shrink your bill, and keep more of your hard-earned cash in your pocket. So grab a cuppa, and let's make tax less taxing.
Navigating Landlord Taxes Without the Headache
Let’s be honest, the moment someone mentions "HMRC" or "Self Assessment," it’s easy to feel a sudden urge to go and reorganise your sock drawer. But getting to grips with your landlord tax responsibilities doesn’t have to be a chore.
Think of this guide as your friendly co-pilot, here to steer you through the essentials without the jargon that makes your eyes glaze over. We're starting from square one, building a solid foundation before we get into the really juicy tax-saving tactics.
What We'll Cover Together
This guide is your roadmap for a stress-free journey through the world of property tax. We'll explore everything you need to know, breaking it down into simple, bite-sized chunks. Here’s a sneak peek at what’s on the agenda:
- What's Taxable? We’ll demystify what HMRC actually considers income, from the obvious—your monthly rent—to the less common bits and bobs.
- Allowable Expenses: This is the secret weapon in every smart landlord's toolkit. We'll uncover all the everyday costs you can subtract from your income to lower your tax bill. (This is the fun part!)
- The Big Rules: The tax landscape is always shifting. We'll get you up to speed on major updates, including those pesky changes to mortgage interest relief.
- Taming the Paperwork Beast: We'll show you how to stay organised without needing a warehouse for all your receipts.
A crucial aspect of managing landlord finances effectively involves understanding and implementing various property tax savings strategies. Knowing what you can and cannot claim is the first step towards optimising your tax position.
Ultimately, being informed is your best defence against tax-season stress. By the end of this guide, you won't just understand the rules; you'll know how to make them work for you.
Feeling a bit overwhelmed already? Don't be. We're here to help you feel confident and in control. If you’d rather have an expert handle it from the start, get in touch with Artema today for a friendly, no-jargon chat about your needs.
Uncovering Your Allowable Expense Treasure Trove
Now for the fun part—slashing your tax bill. Think of this section as a treasure hunt for ‘allowable expenses’. These are simply the day-to-day running costs of your rental property that you can subtract from your income, which in turn lowers the amount of profit HMRC can tax you on.
Let's put it this way. Imagine your rental property is a small business, like a corner shop. You wouldn’t expect the shop owner to pay tax on the cost of the crisps and chocolate they buy to sell, would you? The same principle applies here. The money you spend just to keep your property ticking over isn't profit, so you shouldn't be taxed on it.
This is where keeping good records really pays off, turning routine costs into valuable tax deductions. The more legitimate expenses you claim, the less tax you pay. It’s as simple as that.
This image breaks down how your taxable profit is actually calculated.
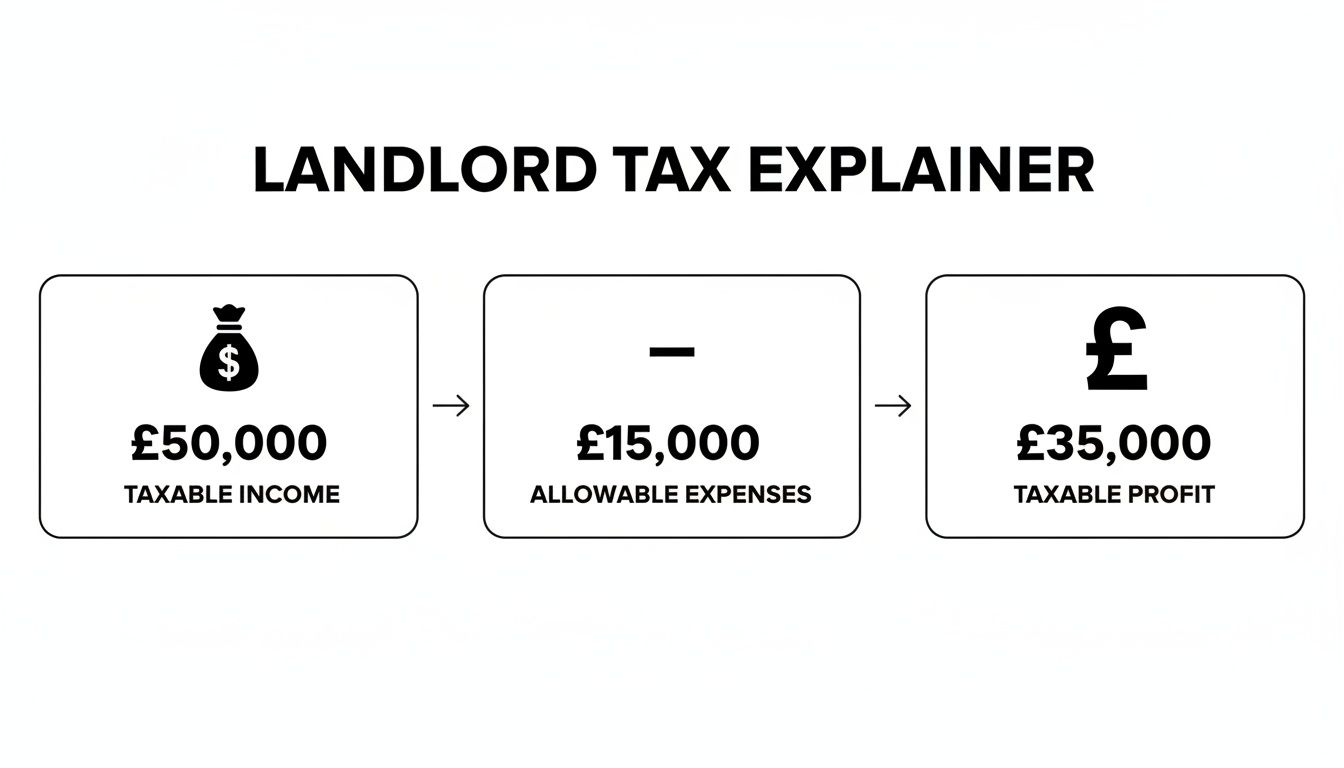
As you can see, every pound you claim as an allowable expense directly shrinks your taxable profit, putting money straight back where it belongs—in your pocket.
Spotting Your Everyday Deductions
So, what exactly can you claim? The list is probably longer than you imagine. The key phrase from HMRC is that the costs must be incurred 'wholly and exclusively' for the purpose of your property rental business. In other words, you can't claim for your weekly shop just because you bought a lightbulb for the tenant.
To help you get started, here's a quick-reference table of common costs you can use to chop down that tax bill.
Common Allowable Expenses for UK Landlords
| Expense Category | Examples | Pro Tip |
|---|---|---|
| Professional Fees | Letting agent fees, property management fees, accountant fees, costs for tenancy agreements. | Keep invoices for all professional services. These are some of the easiest expenses to prove. No arguments here! |
| Insurance | Landlord building insurance, contents insurance, public liability cover. | Premiums are fully deductible. Don't forget to claim for any specific landlord policies you hold. |
| Maintenance & Repairs | Fixing a leaky tap, mending a fence, replacing a broken window, repainting a room between tenancies. | This is for repairs, not improvements. A brand new kitchen is an improvement (capital), but fixing a broken cupboard door is a repair (revenue). |
| Running Costs | Utility bills (gas, electric, water) during void periods, council tax, ground rent. | Service charges are also included here, but the accounting can be fiddly. Best to get that right. |
| Office & Travel | Stationery, postage, phone calls related to the property, mileage for visiting the property for inspections. | Keep a mileage log! HMRC's approved mileage rates make this an easy win. |
| Advertising | Costs to advertise for new tenants, whether online on platforms like Rightmove or in a local paper. | Any direct cost you incur to find a tenant is generally allowable. |
This isn't an exhaustive list, but it covers the main expenses that nearly every landlord will bump into. Just remember to keep your receipts and invoices organised!
Digging Deeper for More Savings
Beyond the obvious, there are other costs you might be overlooking. These smaller expenses can add up significantly over a full tax year.
For instance, service charges can be a complex area. We've written a whole guide to help you navigate the rules on accounting for service charges. It's well worth a read to ensure you're claiming correctly.
It’s easy to see why HMRC data for the 2023–24 tax year showed 2.86 million landlords declaring rental income. With the average property income per landlord rising by around 15% over the past five years to £19,400, the tax implications are huge. For a higher-rate taxpayer, that could mean a tax bill of over £7,700 before any reliefs. Yikes! This makes tracking every single expense more important than ever.
To really get to grips with what you can and can't claim, have a look at these essential rental property tax deductions. It’s a great resource for spotting those often-missed savings.
Feeling like you might be leaving money on the table? We can help you make sure you claim every single allowable expense you're entitled to.
Getting to Grips with Key Tax Reliefs and Rule Changes
The world of landlord tax isn’t set in stone; it’s more like a living thing that HMRC occasionally decides to redesign. Over the last few years, a few key rule changes have really shaken things up for property investors, and ignoring them is not an option.
Think of it as learning the new rules to your favourite board game. The goal is still the same—to run a successful rental business—but how you get there has changed. Let’s tackle the big ones head-on, so you can adapt your strategy and keep playing to win.
The Big One: The Mortgage Interest Relief Shake-Up
Once upon a time, in a land of tax-deductible glory, landlords could simply subtract their full mortgage interest from their rental income before calculating their tax bill. For higher-rate taxpayers, this was a massive benefit.
But those days are over. The old rules were phased out and have now been fully replaced by a less generous system.
Instead of deducting the interest as a straightforward expense, you now get a tax credit equivalent to 20% of your annual mortgage interest. This might sound like a subtle tweak, but its impact is huge, especially for those in the higher tax brackets.
Key Takeaway: You now get a flat 20% tax credit on your mortgage interest, no matter if you're a basic, higher, or additional rate taxpayer. This means higher-rate taxpayers get significantly less relief than they used to. Ouch.
Let's walk through a quick example. Meet Landlord Larry, a 40% taxpayer with £12,000 in rental income and £5,000 in mortgage interest costs for the year.
- Under the old rules: Larry would deduct the £5,000 interest from his income, paying 40% tax on the remaining £7,000. His tax would be £2,800.
- Under the new rules: Larry pays 40% tax on his full rental income (£12,000), which comes to £4,800. He then gets a tax credit of 20% on his interest (£5,000 x 20% = £1,000). His final tax bill is £4,800 – £1,000 = £3,800.
That's an extra £1,000 in tax Larry has to find each year. This change was part of a broader government strategy that has fundamentally altered the financial landscape for buy-to-let landlords. As research from the Joseph Rowntree Foundation highlights, the introduction of a 3% Stamp Duty Land Tax (SDLT) surcharge and this move to a flat 20% tax credit have made debt-heavy property strategies far less tax-efficient. You can explore their full analysis on how tax reform is rebalancing the housing market.
Replacing Domestic Items: A Relief for Wear and Tear
Now for some better news! When the trusty fridge you provided finally gives up the ghost, or the mattress has seen better days, there's a relief for that. It’s called the Replacement of Domestic Items Relief.
This relief lets you claim the cost of replacing a 'like-for-like' domestic item in your rental property. This covers things like:
- Moveable furniture (sofas, beds, tables)
- Furnishings (curtains, carpets)
- Household appliances (fridges, washing machines)
- Kitchenware (crockery, utensils)
You can claim the cost of the new item, minus any money you got for the old one (if you managed to sell its sad, broken carcass). The crucial point is you can't claim for the initial purchase, only its replacement. And if you upgrade to a gold-plated, diamond-encrusted smart fridge, you can only claim for the cost of what a similar, modern equivalent would have been.
A Quick Word on Furnished Holiday Lettings
Finally, it's worth knowing that Furnished Holiday Lettings (FHLs) play by a different set of rules entirely. For tax purposes, HMRC treats them more like a trading business than a standard property investment. This gives them access to certain tax advantages that regular buy-to-lets don't get.
The rules for qualifying as an FHL are super strict, so this is definitely an area where getting professional landlord tax advice is a smart move.
Understanding these reliefs and rule changes is the difference between surviving and thriving as a landlord. If you're looking at your numbers and wondering how these changes impact you, get in touch with Artema. We can help you review your strategy and make sure you're in the strongest possible position.
Preparing for Capital Gains Tax When You Sell
So far, we’ve covered the day-to-day tax realities of being a landlord. But what happens when you decide to sell your rental property? That’s when you’ll meet a new player on the tax field: Capital Gains Tax (CGT).
Don't let the name put you off. In simple terms, CGT is just the tax you pay on the profit you make when an asset you own increases in value. For landlords, this means you're taxed on the difference between what you originally paid for the property and what you sell it for.

It’s crucial to remember this isn't a tax on the total sale price, but only on the ‘gain’ you’ve made. Selling a property can trigger a significant tax bill, but with some clever planning, you can soften the blow and make sure your investment pays off as handsomely as possible.
Calculating Your Capital Gain
Working out your gain might sound complex, but the basic formula is actually pretty straightforward. It’s the selling price minus the original purchase price and any hefty costs you incurred along the way.
You can deduct certain allowable costs from your gain, which helps to reduce your taxable amount. These include:
- Buying and Selling Costs: Think stamp duty, solicitor's fees, and estate agent fees.
- Capital Improvements: This covers major work that genuinely boosted the property's value, like adding an extension or a swanky new kitchen (not just routine repairs).
For example, say you bought a property for £150,000 and later sold it for £250,000. Your initial gain is £100,000. But if you spent £5,000 on fees and £15,000 on a loft conversion, your taxable gain would drop to £80,000. Phew.
Understanding CGT Rates and Reliefs
The amount of CGT you actually pay hinges on your income tax bracket. For residential property, basic-rate taxpayers pay 18%, while higher-rate taxpayers pay a steeper 24%. Everyone also gets an annual CGT allowance—a set amount of gain you can make each year, completely tax-free.
One of the most valuable reliefs available is Private Residence Relief (PRR). If the property was your main home at any point, that period (plus the final nine months of ownership) is exempt from CGT. This can slash your final bill dramatically.
The rise in property values has made CGT a central issue for landlords. Research from Positive Money reveals that landlords in England gained over £400 billion in wealth from house price rises between 1990 and 2022. A landlord selling in 2023 after buying in the early 90s could see an average gain of £240,634, potentially triggering a huge tax bill. Read the full research on how rising property values impact landlords to understand the scale of these gains.
Smart Strategies for Managing Your CGT Bill
Facing a hefty CGT bill can feel like a penalty for a successful investment, but there are smart ways to plan ahead. Timing, as they say, is everything.
- Use Your Allowance: If you're selling multiple properties, think about staggering the sales over different tax years to use multiple annual allowances.
- Transfer to a Spouse: You can transfer assets to a spouse or civil partner without triggering CGT. This allows you to use both of your annual allowances when you eventually sell. Double the fun!
- Time the Sale: If your income fluctuates, selling in a year when you're in a lower income tax bracket could cut your CGT rate from a painful 24% down to 18%.
It’s also critical to be aware of the reporting deadlines. You must report and pay any CGT due on UK residential property sales within 60 days of completion. For more detail, you can explore our complete guide on the 60-day rule for Capital Gains Tax.
CGT planning requires real foresight and a solid grasp of the rules. If selling is on your horizon, getting expert advice is the best way to protect your profit. Contact Artema for a consultation, and we can model different scenarios to help you find the most tax-efficient path forward.
Taming the Paperwork Beast with Smart Record-Keeping
If there’s one universal truth for landlords, it’s that paperwork multiplies when you’re not looking. One minute you have a neat folder; the next, a beast made of invoices, bank statements, and till receipts is taking over your office. Taming this beast isn’t just about being tidy—it's the absolute foundation of a stress-free tax season.
Excellent record-keeping is your secret weapon for claiming every single penny you're entitled to. Without it, you’re essentially guessing, and that can be a very expensive game to play with HMRC.
The Shoebox of Doom vs. Digital Freedom
For years, the 'shoebox method' was the unofficial accounting system for many landlords. This involved chucking every crumpled receipt into a box and hoping for the best come January. Spoiler alert: this is a recipe for disaster, missed expenses, and a massive headache.
Thankfully, we now have a much smarter way to manage things. Digital tools and accounting software have completely changed the game, turning chaos into clarity. Think of it as upgrading from a paper map to a satnav—both might get you there, but one is infinitely easier and more reliable.
Good records are more than just a legal requirement; they are your live dashboard for making smart financial decisions about your property. They show you what's working, what's not, and where every pound is going.
Modern accounting software, like the Xero platform we champion at Artema, automates most of this heavy lifting. It connects to your bank, helps categorise your spending, and gives you a real-time view of your property's financial health. It’s your digital filing cabinet that actually does the filing for you. Magic!
Why Digital Record-Keeping is a No-Brainer
Switching to a digital system isn't just about convenience; it’s about being prepared for what’s coming down the track. Here’s why it’s really the only way forward for serious landlords:
- Instant Access: Find any invoice or receipt in seconds, rather than digging through a mountain of paper.
- Real-Time Profitability: See exactly how much profit your property is making at any given moment, not just once a year.
- Claim Everything You're Owed: Digital systems make it simple to track every allowable expense, from a major repair right down to a box of screws.
- Future-Proofing Your Business: With HMRC’s big push towards digital tax, getting organised now is essential. For more on this, have a read of our guide on what Making Tax Digital for landlords means for you.
By embracing digital tools, you can finally slay the paperwork dragon and turn your financial data into a powerful asset.
Ready to trade your shoebox for a streamlined, stress-free system? Get in touch with Artema, and we can show you how our Xero integration can make your record-keeping effortless.
Why an Expert Co-Pilot Makes Tax Season Easier
Of course, you can absolutely file your own tax return. Many landlords start out doing exactly that, armed with a calculator, a strong coffee, and a can-do attitude. But as your portfolio grows or your finances get a little more complex, that DIY approach can quickly feel like you’re trying to fly a jumbo jet after only skimming the instruction manual.
This is where having an expert co-pilot changes everything. Instead of trying to navigate through turbulence all on your own, you’ve got a seasoned professional right there with you, handling the complex controls and pointing out the smoothest route forward. At Artema, that’s precisely what we do—we become your expert partner, dedicated to saving you time, money, and a whole lot of stress.
From Paperwork Panic to Automated Peace of Mind
Remember that mountain of paperwork we talked about? One of the biggest wins of working with an expert is taming that beast for good. We get your finances properly organised using powerful, modern tools that make sense of the chaos.
At Artema, we use accounting software like Xero to build a seamless system just for you. This isn't just about making a fancy spreadsheet; it's about giving you a live, up-to-the-minute picture of your property's financial health.
- Effortless Expense Tracking: No more sifting through shoeboxes for receipts. Every transaction is categorised automatically, making sure you never miss a single allowable expense.
- Real-Time Clarity: You can see your income, expenses, and profit at a glance, whenever you want.
- Simplified Tax Filing: When it's time to file, all the information is already there, neatly organised and ready to go.
This integrated approach puts your record-keeping on autopilot, freeing you up to focus on what you do best—being a great landlord.
Proactive Planning Prevents Nasty Surprises
Have you ever got to the end of January only to be hit with a tax bill that was much, much bigger than you expected? That sinking feeling in your stomach is exactly what professional landlord tax advice helps you avoid. Our work goes far beyond simply filing your return once a year.
We believe in proactive financial management. By carrying out regular quarterly reviews, we can spot potential issues and opportunities long before they become problems.
A tax return reports on the past, but great tax advice shapes your future. By looking ahead, we can help you make strategic decisions that legally minimise your tax liability throughout the year, not just at the deadline.
This means no more nasty surprises. You’ll always know exactly where you stand with HMRC, which allows for better budgeting and far greater peace of mind.
Whether you're thinking about selling a property and need to plan for Capital Gains Tax, or you’re weighing up whether to set up a company for your growing portfolio, we’re here to model the outcomes and guide you through it.
If you’re ready to trade tax-season stress for year-round confidence, get in touch with Artema today. Let us be your expert co-pilot and make your journey as a landlord a whole lot smoother.
Landlord Tax FAQs
We’ve navigated the maze of allowable expenses and stared down Capital Gains Tax. But sometimes, you just need a quick, straight answer. This is your rapid-fire round for those niggling tax questions that keep you up at night.
We’ve pulled together the most common queries we get from landlords. Let's clear up these tricky details once and for all.
Do I Need to File a Tax Return if My Profit Is Small?
This is a big one, and the short answer is: probably, yes. If your total income from property rental nudges over £1,000 in a tax year, HMRC needs to know about it.
Here’s a simple breakdown:
- Income under £1,000: You can use the property income allowance. No need to report it. Hooray!
- Income between £1,000 and £2,500: You’ll need to get in touch with HMRC to sort out how you'll pay tax.
- Income over £2,500: You must register for Self Assessment and get a tax return filed.
That £1,000 allowance is a handy alternative to claiming your actual expenses, especially if they’re very low. But it's always smart to keep good records anyway, just in case things change.
Can I Claim for Renovations or Just Repairs?
Ah, the classic landlord mix-up. Getting this wrong can be a costly mistake, as HMRC draws a very clear line between a 'repair' and an 'improvement'.
A repair is all about bringing something back to its original state – think fixing a leaky tap or replacing a storm-damaged fence panel. These are day-to-day 'revenue' expenses, and you can deduct them from your rental income in the same year.
An improvement, or renovation, is a significant upgrade. We're talking about building an extension, completely refitting a kitchen, or adding a new bathroom.
Think of it like this: repainting a wall is a repair. Knocking that wall down to create an open-plan living space is an improvement.
These bigger jobs are 'capital' expenditure. You can't claim them against your rental income, but don't lose the receipts! You add them to the property's cost base, which will reduce your Capital Gains Tax bill when you eventually sell up.
What Happens if I Miss the Self Assessment Deadline?
Missing the 31st January online filing deadline is one mistake you really want to avoid. The penalties from HMRC are automatic and unforgiving. You’ll be hit with an instant £100 fine – even if you don’t owe a penny in tax. Ouch.
If your return is more than three months late, daily penalties of £10 kick in, up to a maximum of £900. The costs just keep spiralling from there, and you’ll also be charged interest on any unpaid tax. It’s an expensive headache that’s easily avoided with a bit of planning.
Feeling overwhelmed by the rules? You're not alone. The world of property tax is complex, but you don't have to navigate it by yourself. At Artema Ltd, we provide clear, practical landlord tax advice to help you stay compliant, save money, and focus on what you do best.
If you’re ready to trade tax stress for financial clarity, get in touch with us today.