
Thinking about swapping your sole trader status for a shiny new limited company? If so, the big reason is probably the same for everyone: tax. Or, more specifically, paying less of it!
Operating as a limited company isn't just about sounding official; it unlocks some seriously smart ways to keep more of your hard-earned cash where it belongs – with you. For a growing business, it’s often one of the best financial moves you can make.
Your Guide to Limited Company Tax Perks
If you're currently a sole trader, you've probably winced at your tax bill more than once. Every pound of profit you make above your personal allowance gets a double whammy of Income Tax and National Insurance. It’s simple, sure, but as your income climbs, the taxman’s slice of your pie gets bigger and bigger.
Switching to a limited company completely changes the game.
The best way to think of it is like this: being a sole trader is the "pay-as-you-go" of business life. A limited company is the premium monthly contract, loaded with perks and benefits that give you far more control over your finances.
Why the Structure Matters
At the heart of it all is one crucial difference: a limited company is a separate legal entity from you, the owner. It’s its own ‘person’ in the eyes of the law. This creates a clean line between your money and the business’s money, and it’s this separation that unlocks a whole new world of limited company tax benefits.
Suddenly, you can use strategies that just weren't on the table before, like:
- Paying the much lower Corporation Tax rates on your profits.
- Cleverly paying yourself with a mix of a small salary and tax-friendly dividends.
- Claiming a much wider range of business expenses (more on that later!).
- Making super-efficient pension contributions directly from the business before any tax is deducted.
To give you a clearer picture, let's put the two structures head-to-head.
Sole Trader vs Limited Company Tax At a Glance
This table breaks down the main tax differences between the two most common ways to run a small business in the UK.
| Feature | Sole Trader | Limited Company |
|---|---|---|
| How Profits are Taxed | Profits are your personal income. You pay Income Tax and National Insurance on everything. | The company pays Corporation Tax on its profits. You are then taxed personally on the money you take out. |
| Tax Rates | Income Tax (20%, 40%, 45%) plus Class 2 & 4 National Insurance. | Corporation Tax (19% or 25%). Dividend tax rates (8.75%, 33.75%, 39.35%) apply to withdrawals. |
| Paying Yourself | You just take money from the business (drawings). Simple, but not always tax-efficient. | You typically pay yourself a small, tax-smart salary and take the rest as dividends. |
| Liability | Unlimited personal liability. Your personal assets (like your house!) are at risk if the business struggles. | Limited liability. Your personal assets are protected because the company is its own legal 'person'. |
Seeing it laid out like this really shows the strategic advantages a limited company can offer.
This guide will walk you through each of these perks one by one. We'll ditch the jargon to show you exactly how this switch can boost your bank balance. For those exploring more advanced tax planning, understanding the nuances of UAE offshore company formation for tax benefits can also unlock significant opportunities.
How Lower Corporation Tax Rates Boost Your Bottom Line
The first, and arguably biggest, perk you’ll notice is how your profits are taxed. As a sole trader, every penny of profit is treated as your personal income, which means it gets hit with Income Tax and National Insurance. The more you earn, the more HMRC takes.
A limited company completely changes this.
Imagine your business profit is a freshly baked pizza. As a sole trader, the taxman gets a hefty slice—sometimes a very large one—straight away. But as a limited company, they take a smaller, more predictable slice first. This leaves a much bigger pizza for you to decide what to do with. That smaller, business-level slice is called Corporation Tax.
Understanding the Corporation Tax Advantage
Instead of your profits being taxed at personal Income Tax rates that can climb as high as 45%, your company pays Corporation Tax at a much friendlier flat rate. This single difference is the foundation of so many of the tax efficiencies that come with running a limited company.
For smaller companies, the savings can be substantial. One of the main tax benefits is that profits up to £50,000 are currently taxed at just 19%. That’s a massive drop from the higher rates that successful sole traders often find themselves paying.
This means your business holds onto more of its earnings, giving you vital cash flow to reinvest, grow, or simply build a cushion for a rainy day (or a sunny holiday!).
The core idea is simple: the business pays its own, lower tax first. This leaves more profit inside the company, giving you complete control over how and when you take that money out for yourself.
A Practical Example of Tax Savings
Let’s put this into perspective with a simple scenario.
Imagine your business makes a profit of £45,000 in a year.
- As a Sole Trader: After your personal allowance, a large chunk of this profit would be subject to 20% Income Tax plus Class 4 National Insurance. Your total tax bill would add up quickly.
- As a Limited Company: Your company would pay Corporation Tax at 19% on the full £45,000 profit. This results in a tax bill of just £8,550, leaving much more money inside the business to work with.
The difference is immediately clear. The lower initial tax bite gives you breathing room and flexibility that a sole trader simply doesn't have. Of course, tax rules love to change, and you can stay informed by reading about the highlights of recent government announcements like the Spring Budget 2023.
Feeling a bit more confident about how this works? The next step is getting clever about how you take that remaining profit out of the company.
Mastering the Salary and Dividend Mix
Once your company has paid its Corporation Tax, leaving a healthy profit in the pot, the next big question is: how do you get that money into your own pocket? This is where you can get really strategic, and it’s one of the biggest tax benefits of running a limited company. As a director, you're in the driving seat.
Think of it like mixing the perfect financial cocktail. Instead of taking one big gulp of salary (which gets hit hard by tax), you create a much more sophisticated and tax-friendly blend.
The recipe is surprisingly simple: a small measure of salary, topped up with a generous pour of dividends. Getting this combination right is the key to maximising what you actually take home.
The Smart Way to Pay Yourself
So, what’s the logic behind this magic mix? It’s all about playing by HMRC’s rules in the smartest way possible.
-
A Low Salary: You pay yourself a small salary, typically just enough to keep your National Insurance contributions ticking over. This qualifies you for state benefits like the State Pension down the line. Crucially, this salary is a business expense, which reduces your company's Corporation Tax bill. It’s a classic win-win.
-
Tax-Efficient Dividends: The rest of your income comes from dividends. A dividend is simply your share of the company's profits after Corporation Tax has been paid. Think of it as a reward for being a shareholder in your own successful business!
The real beauty of dividends is that they are taxed differently—and far more gently—than a salary.
By blending a low salary with dividends, you can slash your personal tax bill. For many, this strategy alone makes forming a limited company worthwhile, putting thousands of pounds back into their pocket each year.
This visual shows just how much better the tax outcome can be when you operate as a limited company compared to being a sole trader.
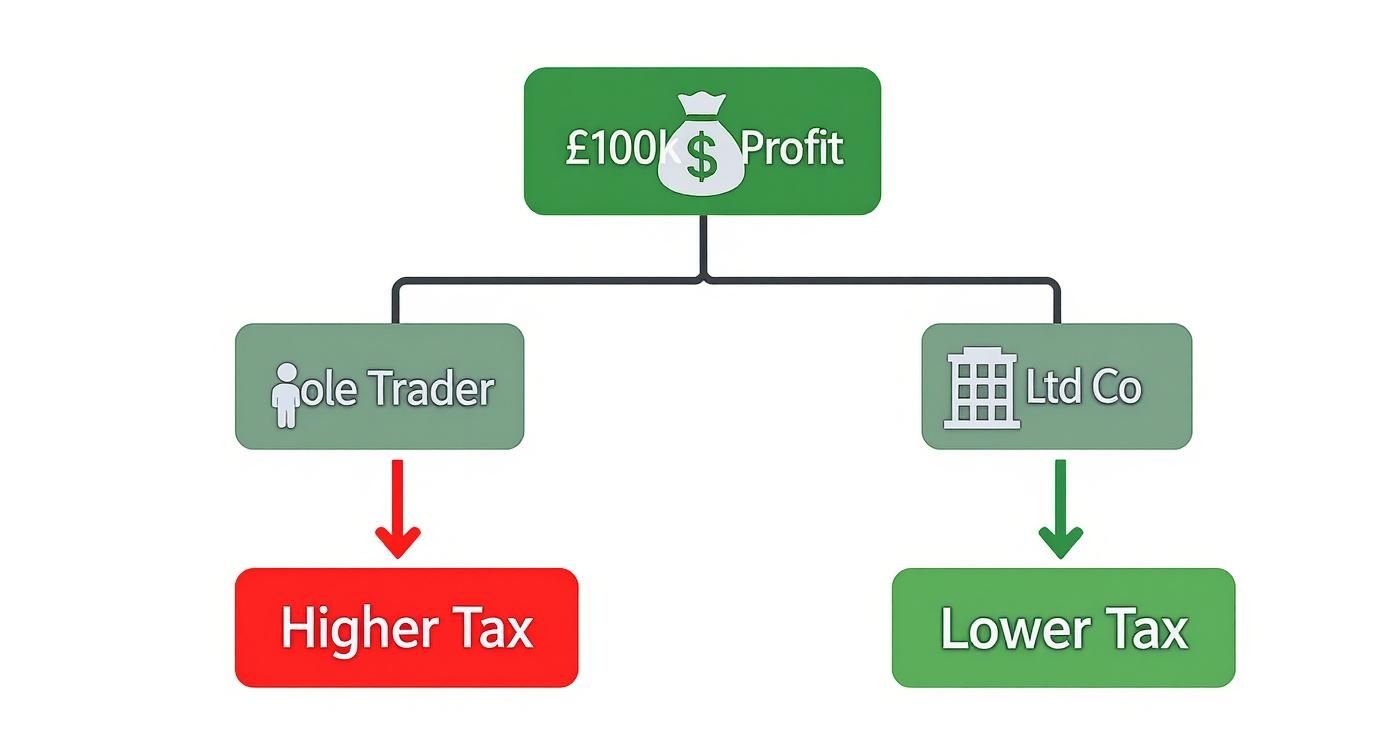
The takeaway is crystal clear: the structure you choose for your business has a direct impact on how much tax you pay on the exact same amount of profit.
Why Dividends Are Your Best Friend
Another huge advantage of the limited company route is the flexibility in how you take out profits. Dividend tax rates are much lower than income tax rates, and crucially, they don't attract any National Insurance Contributions (NICs). In the 2025-26 tax year, the basic rate for dividends is just 8.75%—a massive saving compared to the 20% income tax plus NICs you’d pay on a salary.
You also have control over when you declare dividends, helping you manage your total income to stay within lower tax bands. You can find out more about how you can benefit from the sole trader vs limited company structure on Pensionbee.com.
Let’s look at a quick comparison to see the real-world impact.
Scenario A: Director takes a £50,000 salary
- Employee's National Insurance applies.
- Employer's National Insurance applies (this is an extra cost to the company!).
- Higher rate Income Tax will likely apply to a portion of the earnings.
Scenario B: Director takes a £9,000 salary and £41,000 in dividends
- The salary is low enough to avoid most National Insurance.
- The dividends are taxed at the much lower dividend tax rates.
- The overall tax paid by both the director and the company is substantially lower.
The difference in take-home pay between these two scenarios can easily run into thousands of pounds. Getting this mix right is essential, and it’s a chat every director should have with their accountant to create their own perfect financial cocktail.
Maximising Your Allowable Business Expenses
If getting the salary and dividend mix right is the art of tax planning, then claiming your business expenses is the science. This is one of the most direct and satisfying ways to see the tax benefits of a limited company in action.
Every single legitimate expense you claim reduces your company’s profit, which, in turn, lowers your Corporation Tax bill. It’s that simple.
Think of it like this: for every £100 you spend on a genuine business cost, you’re not just getting something your business needs—you’re also getting a tax discount on that purchase. This is where being organised with your receipts literally pays off.
So many business owners claim the obvious things, like software and stationery, but the real savings are often hiding in the expenses you might not have even considered.
What Can You Actually Claim?
HMRC has a golden rule for expenses: they must be “wholly and exclusively” for business purposes. This phrase can sound a bit scary, but it’s actually more straightforward than you might think. If you bought something purely to help your business make a profit, it’s almost certainly a claimable expense.
Here are just a few of the common expenses you should definitely be tracking:
- Office Costs: This covers everything from rent and business rates to stationery, postage, and the company phone bill.
- Travel and Mileage: Any journeys to meet clients, visit suppliers, or attend conferences are claimable. You can claim for fuel (using approved mileage rates), train tickets, and even hotels for overnight stays.
- Training and Development: Courses that directly improve your skills or knowledge for your business are allowable. Want to become a pro at digital marketing? That course is an expense.
- Professional Fees: Your accountant's fees are a classic example. Any legal fees or professional subscriptions (like to a trade body) also fall into this category.
The key is to shift your mindset. Don't think of it as "spending money"; think of it as "investing in tax-deductible assets and services". Every receipt is a potential tax saving waiting to be claimed.
Going Beyond the Obvious
The benefits of a limited company really come to life when you dig into the full range of allowable expenses. Unlike sole traders, companies can often claim for a wider variety of costs, from business travel to professional fees, all of which directly cut down your taxable profit.
Let's say your company makes a £100,000 profit but you've correctly claimed £20,000 in expenses. You only pay Corporation Tax on the remaining £80,000. The difference is substantial.
This even extends to things like certain types of staff entertainment. While entertaining clients is a bit trickier from a tax perspective, treating your team can often be done in a tax-efficient way. Have a look at our guide on entertaining staff and customers tax-efficiently to understand the rules.
Keeping detailed records is your superpower here. Use good accounting software, keep your receipts organised, and if you’re ever unsure whether an expense qualifies, just ask your accountant. It's our job to help you claim everything you're entitled to, making sure you never leave money on HMRC’s table.
Using Pensions to Supercharge Your Tax Savings
Here’s a strategy that looks after both your future self and your business today. Making pension contributions directly from your limited company is one of the most powerful and often overlooked limited company tax benefits out there. It’s a genuine win-win that feels a bit like financial magic.
The whole concept is brilliantly simple. Your company pays into your personal pension pot before it works out its final profit. HMRC treats this contribution as a business expense, just like your software or office rent. This directly lowers your company’s profit, which in turn slashes your Corporation Tax bill.
It's a fantastic way to plan for your retirement while making some serious immediate tax savings.
The Double-Dip Benefit
Think of it as getting two tax breaks for the price of one. Not only does the business get tax relief on the contribution, but the money also lands in your pension fund without you having to pay a penny of personal Income Tax or National Insurance on it.
If you were to pay yourself that money as a salary first and then put it into a pension, you’d lose a decent chunk to tax along the way. This direct-from-company method is just far more efficient.
By paying into your pension from the business, you are effectively moving pre-tax profit from the company's bank account directly into your retirement savings. The full amount gets to work for your future, completely untouched by personal taxes.
A Quick Calculation
Let's imagine you want to add £10,000 to your pension.
- Paying Personally: If you took this as a dividend, you'd first have to pay Corporation Tax on the company profit, and then dividend tax on what you withdraw. To get £10,000 into your pension, you’d need to have earned significantly more in company profit to begin with.
- Paying from the Company: Your company simply pays the £10,000 straight into your pension scheme. That £10,000 is then deducted from your profits, saving you £1,900 in Corporation Tax (at the 19% rate).
The difference is huge. This approach helps you build a much healthier pension pot, much faster, all while cutting your immediate tax bill. For a deeper dive, you can learn more about the rules surrounding employer pension contributions in our detailed guide.
To really get the most out of your long-term financial growth, it's vital to understand the various types of tax-advantaged retirement accounts available. An accountant can help you build this into your wider tax strategy.
Ready to Save More Tax? Here Are Your Next Steps
Feeling fired up about the tax-saving power of a limited company? You should be! We've covered some serious ground, from the brilliant basics of lower Corporation Tax to the clever salary and dividend mix that puts more cash in your pocket.
You've seen how every legitimate business expense becomes a tool to lower your tax bill. We also explored how pension contributions are a fantastic way to save for your future while cutting your company's tax today. It’s a lot to take in, but these are the core limited company tax benefits that make the structure so appealing.
So, When Should You Make the Switch?
There isn't a magic number, but a good rule of thumb is to start seriously thinking about it once your annual profits are consistently pushing past the £30,000-£40,000 mark. At this level, the tax savings often start to comfortably outweigh the extra admin involved.
While this guide gives you a fantastic head start, think of it as your learner's permit. The next step is to get behind the wheel with a qualified instructor—an accountant.
This is where professional advice becomes priceless. An expert can look at your specific business and personal circumstances to create a tax strategy that fits you perfectly. They make sure you're not just saving tax, but doing it legally, confidently, and without the headaches.
Ready to stop leaving money on the table? Get in touch with us at Artema today, and let's build a tax plan that lets you keep more of your hard-earned money.
Your Limited Company Tax Questions Answered
We’ve covered a lot of ground, but you probably still have a few questions buzzing around. That’s completely normal! Here are some straightforward answers to the most common queries we hear about the tax benefits of a limited company.
Is It Expensive to Set Up and Run a Limited Company?
Setting up a limited company is surprisingly cheap; the one-time registration fee with Companies House is minimal. Think less than the price of a fancy dinner out. The ongoing costs, however, are higher than being a sole trader.
You’ll need to budget for accountancy fees to handle your annual accounts and Corporation Tax return. While these are all tax-deductible expenses (a perk in itself!), they are a new cost to factor in. For most businesses hitting a certain profit level, the annual tax savings easily cover these fees with plenty to spare.
When Is the Right Time to Become a Limited Company?
There isn’t a single magic number that works for everyone, but a common benchmark is when your annual profits consistently start to climb above the £30,000-£40,000 mark. At this point, the financial advantages from lower Corporation Tax and the salary-dividend strategy really begin to pull ahead.
Think of it less as a hard rule and more as a financial signpost. When your tax bill as a sole trader starts to make you wince, it’s probably time to have the conversation about switching.
Other triggers can also signal it's the right time. You might need the legal protection of limited liability for a new contract, or you might want to present a more professional image to attract bigger clients.
Can I Claim Expenses for Working from Home?
Yes, absolutely! This is one of the great practical limited company tax benefits. As a director, you can claim for a portion of your household running costs if you work from home. HMRC gives you a couple of ways to do this.
You can either:
- Use the simple flat-rate allowance, which is a set amount per week and requires no fiddly calculations.
- Calculate a proportion of your actual household bills (like electricity, heating, and internet) based on how much of your home you use for business, and for how long.
An accountant can quickly help you work out which method will save you the most money.
Navigating these questions is the first step towards a smarter tax strategy. If you're ready to get personalised answers and unlock the full potential of your business, the team at Artema Ltd is here to help. Visit us at Artema to book a consultation and start saving.