
Let's be honest, the phrase 'Making Tax Digital' probably sounds about as much fun as a surprise boiler breakdown on a bank holiday. The good news is, it's nowhere near as scary or complicated as it sounds.
In a nutshell, Making Tax Digital (MTD) for landlords simply means you'll need to keep digital records of your finances. You'll then use special, HMRC-approved software to send them a quick update on your rental income and expenses every quarter. It’s time to say a final, triumphant farewell to that shoebox stuffed with faded receipts and hello to a slicker, smarter way of managing your tax.
What on Earth Is Making Tax Digital for Landlords?
If you've heard the term ‘Making Tax Digital’ and felt a slight sense of dread, you’re definitely not alone. It sounds like something cooked up in a committee meeting to make our lives more difficult, but the reality is surprisingly straightforward and, dare we say it, even helpful.
Think of it as HMRC finally joining the 21st century, swapping its dusty old filing cabinets for a shiny new digital system. The whole idea is to make tax admin more accurate and a lot less painful for everyone. For landlords, this means the big, scary annual Self Assessment is on its way out, replaced by smaller, more regular updates.
So, what does this actually change for you, the person juggling tenancy agreements and leaky taps?
- Digital Records Are a Must: Instead of stuffing receipts into a drawer to be sorted "later," you'll need to log all your rental income and expenses using MTD-compatible software.
- Quarterly Updates, Not Panic Filing: That big January tax return rush is being replaced. You’ll now send a summary of your income and expenses to HMRC every three months.
- One Final Sign-Off: At the end of the tax year, you'll review everything, make any final tweaks, and submit what's called a Final Declaration to confirm it's all correct.
Essentially, MTD is about shifting from one huge, stressful deadline to smaller, more manageable updates throughout the year. Easy peasy.
MTD for Landlords Key Changes at a Glance
To make it even clearer, let's compare the old way of doing things with the new MTD requirements.
| Tax Task | The Old Way (Annual Self Assessment) | The New Way (MTD for ITSA) |
|---|---|---|
| Record Keeping | A glorious mess of spreadsheets, paper receipts, and bank statements. | Fully digital records using MTD-compatible software. |
| Submissions to HMRC | One annual Self Assessment tax return. | Four quarterly updates plus one final end-of-period summary. |
| Deadline Pressure | One massive deadline each year (31st January). | Five smaller deadlines spread throughout the year. |
| Tax Visibility | You'd often only know your final tax bill at the end of the year. Gulp. | A running estimate of your tax bill is visible all year. Phew! |
As you can see, the main change is the frequency and method of reporting, moving towards a continuous, real-time process.
Why This Isn't as Scary as It Sounds
The thought of more frequent submissions might make you groan, but there's a definite silver lining here. This new process gives you a much clearer, real-time picture of your finances. You'll know exactly where you stand with your tax bill as you go, rather than getting a nasty surprise in January.
The core idea behind MTD is simple: to help you get your tax right the first time. By keeping digital records, you reduce the chances of errors, and quarterly updates mean no more year-end guesswork.
With the right software, snapping a photo of a receipt from B&Q or logging a rent payment can be done in seconds. The goal is to build simple digital habits that make tax feel less like a chore.
Staying on top of regulations is part of being a landlord, and you can find more practical advice by reading the latest articles for landlords. Ultimately, this change is less about creating more work and more about creating a smarter, more efficient workflow for you and your property business.
Does MTD Actually Apply to Your Properties?
Alright, let's get straight to the big question you’re probably asking yourself: "Is this whole MTD thing actually my problem?" It’s a fair point. Before you start having nightmares about digital receipts, let's figure out if you even need to join the party.
The good news is, it all comes down to a simple number: your total annual income.
HMRC isn’t expecting every landlord in the country to jump on board at once. Instead, they're rolling it out in phases based on your qualifying income. This is your total gross income from your property portfolio plus any self-employment income you might have, all before you deduct any expenses. Don't worry, income from your day job (PAYE) or pensions doesn’t count here.
Checking the Income Threshold
So, how do you know if you're on the list? It's all about your income for the tax year. Think of it as a guest list for a rather exclusive, tax-themed event.
Let’s take Sarah, a landlord with two flats in Manchester. Her total rental income is £35,000 a year, and she has no other self-employment gigs. For now, she can relax.
But what about David? He has a small property portfolio bringing in £25,000 a year, but he also runs a freelance photography business that earns him another £30,000. His total qualifying income is £55,000, which means he's definitely on the MTD guest list.
The key takeaway is this: you must add up all your gross rental income and any self-employment turnover. If that combined figure crosses the threshold for a specific year, then MTD for landlords is officially on your radar.
The rules are being introduced gradually. Initially, landlords with an annual qualifying income of more than £50,000 will need to comply with MTD for Income Tax from April 2026.
This threshold then drops to £30,000 from April 2027, bringing more landlords into the fold. Getting these dates locked in your calendar is absolutely crucial for proper planning.
It's so important to get a clear picture of your obligations, especially when it comes to managing the financial side of your properties. For a deeper dive into the specifics, check out our helpful guide on buy-to-let tax.
By adding up your income sources, you can see exactly where you stand. Knowing your timeline removes all the guesswork and lets you prepare without any last-minute panic. If you're still unsure about your numbers or how to calculate them, now is the perfect time to chat with an accountant who can give you clarity.
Choosing Your MTD Software Sidekick
So, you’ve realised Making Tax Digital is on the horizon. The next job is finding the right digital tool to help you deal with it. Think of it as choosing your co-pilot—this software will be your trusted partner in the fight against paperwork and tax-time chaos.
But with a bewildering number of options out there, from big names like Xero and QuickBooks to specialist platforms built just for landlords, it's easy to feel overwhelmed. You can quickly get lost in a sea of monthly subscriptions and feature lists. Don’t panic; we’re here to help you navigate it.
First, let’s be clear on what ‘MTD-compatible’ actually means. It’s simply software that can connect directly to HMRC's systems to send your quarterly updates. This isn't just a fancy spreadsheet; it's a secure digital bridge between your records and the tax office.
Must-Have Features to Make Your Life Easier
When you're looking at different software, don't get distracted by flashy features you’ll never use. Focus on the core functions that will genuinely save you time and stress. These are the non-negotiables that make a real difference for landlords.
- Automated Bank Feeds: This is a game-changer. Linking your dedicated property bank account directly to the software means rental income and expenses are automatically pulled in. It’s the difference between spending hours on manual data entry and letting the software do the heavy lifting for you.
- Receipt Scanning: Picture this: you buy a new smoke alarm at Wickes, take a quick photo of the receipt with your phone, and it’s instantly logged and categorised in your accounts. No more faded bits of paper cluttering up your wallet.
- Landlord-Specific Categories: General accounting software is fine, but tools designed for landlords often come pre-loaded with relevant expense categories like 'repairs', 'letting agent fees', and 'landlord insurance'. This makes sorting your spending an absolute breeze.
It's also worth getting familiar with the various key property management software features available, as many of these can support your digital record-keeping and make MTD compliance that much easier.
What About Spreadsheet Lovers?
Are you someone who lives and breathes Excel? The thought of abandoning your perfectly crafted spreadsheets might bring a tear to your eye. Well, dry those tears, because there’s an option for you, too.
Bridging software is a special tool designed to connect your existing spreadsheets directly to HMRC. You can keep your records exactly as you always have, and the software simply acts as a secure messenger to submit the required figures.
This can be a fantastic, cost-effective option for landlords with a very simple portfolio. The catch? You'll miss out on time-saving features like bank feeds and receipt scanning, which are often the main benefits of moving to dedicated software.
Ultimately, choosing your MTD software is about finding what works for you and your property business. Take some time to explore the options, sign up for a few free trials, and see which one feels like the best fit. Your future, more relaxed self will thank you for it.
A Practical Guide to Digital Record Keeping
So, you’ve picked your software sidekick. Fantastic! Now comes the part where we turn good intentions into simple, repeatable habits. Let's be honest, the thought of ‘digital record keeping’ sounds about as thrilling as watching paint dry, but getting this right is the key to making MTD a walk in the park.
Forget complex accounting theories. We’re talking about simple actions that take seconds.
That receipt for a new boiler? Instead of shoving it in your glove compartment, snap a photo with your software's app. Tenant just paid their rent? Your software, with its magical bank feed, should pick it up automatically. Your job is just to give it a nod of approval.
This isn’t about becoming a master accountant overnight. It's about building small, consistent habits that prevent that dreaded year-end avalanche of paperwork.
Getting Your Categories Straight
One of the biggest wins of using digital software is getting your expenses categorised correctly from the very start. This is where many landlords trip up, but getting it right not only keeps HMRC happy but also gives you a crystal-clear view of where your money is actually going.
The main distinction to get your head around is repairs vs. improvements.
- Repairs: Think of these as 'like-for-like' replacements. If a tenant breaks a window and you replace it with a similar one, that’s a repair. It's a fully deductible expense.
- Improvements: This is when you upgrade something. Replacing a tired old kitchen with a brand-new, high-spec one is an improvement. This isn't an immediate expense but is factored into your Capital Gains calculations when you eventually sell the property.
Getting this right in your software means you're not just complying with MTD; you're also maximising your legitimate tax deductions.
Here's a glimpse of what a typical expense entry might look like in a system like Xero.
The clean interface allows you to quickly log what was spent, who it was paid to, and most importantly, which expense category it belongs to. This keeps your records pristine from day one.
Pro Tips for Pristine Digital Books
Ready to take your record keeping from messy to magnificent? Here are a few tricks of the trade that will make your quarterly submissions ridiculously easy and give you a powerful overview of your portfolio’s financial health.
Think of your digital records as a financial fitness tracker for your property business. The more accurately you log your activity, the clearer your path to a healthy bottom line becomes.
A great starting point is to set up recurring entries for regular costs like landlord insurance or letting agent fees. This puts a chunk of your admin on autopilot.
Another fantastic habit to get into is reconciling your bank account within the software every week. It sounds tedious, but it really only takes about five minutes and catches any discrepancies before they snowball into a proper headache.
These simple habits are the foundation of a stress-free MTD journey. If you need support getting set up, exploring cloud-based accounting services can provide the expert guidance to get you started on the right foot. It’s all about working smarter, not harder.
Conquering Your First Quarterly Submission
Right, you’re all set up with digital records. Now for the part that might feel a bit daunting: the quarterly submission. If your first thought is, "Four tax returns a year? No thank you!", then just take a deep breath. It's absolutely not that.
Think of it less like a tax return and more like a quick, regular check-in with HMRC. Every three months, your software will pull together a simple summary of the rental income and expenses you've been diligently logging. With just a few clicks, you send this snapshot over to the tax office.
And that's pretty much it. No more frantic last-minute searches for lost receipts, no complex calculations—just a simple, straightforward update. The heavy lifting is done by your software, which tots up the numbers and gets them ready to go.
What’s in the Update and What’s Not
It’s really important to understand that these quarterly updates are purely summaries of your income and outgoings. They don’t include any of the complex tax adjustments, allowances, or reliefs. All of that is handled later on.
So, what are you actually sending over to HMRC?
- Total Rental Income: A simple total of all the rent you've received in that three-month window.
- Total Allowable Expenses: A summary of your spending, neatly categorised (all thanks to your brilliant record-keeping!).
Essentially, you’re just keeping HMRC in the loop throughout the tax year. One of the biggest perks of this system is that it gives you a running estimate of your tax bill, which is a fantastic way to avoid any nasty surprises come January. It’s all about making your financial planning smoother.
This simple workflow shows just how straightforward it is to get your data ready for submission.
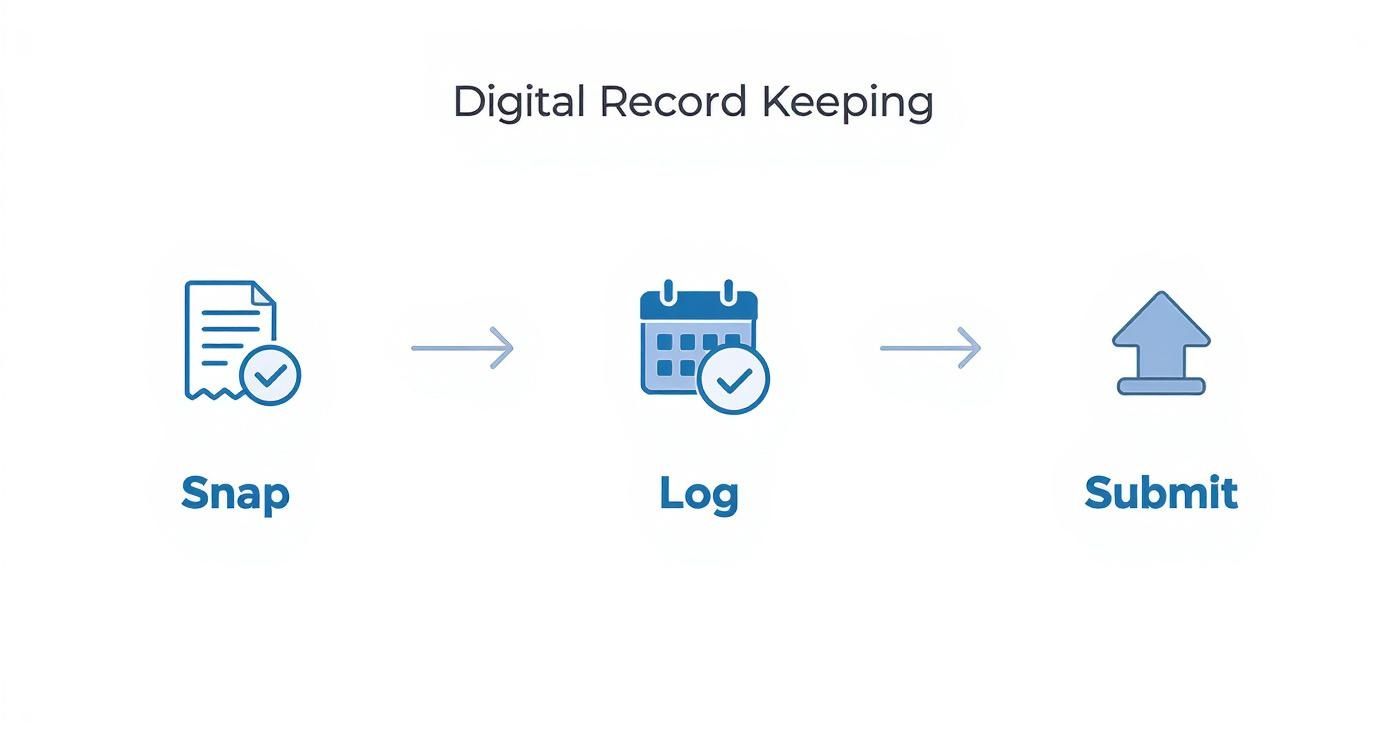
This graphic breaks it down perfectly: just three simple stages that turn your day-to-day admin into compliant tax updates.
The Big Finale: The EOPS and Final Declaration
After you’ve done your four quarterly updates, there are two final steps to wrap up the tax year. Don’t worry, these are also much simpler than the old annual tax return scramble.
The End of Period Statement (EOPS) is where you finalise your business income for the year, making any last-minute accounting adjustments. The Final Declaration is where you bring in all your other personal income (like from a PAYE job) and claim any reliefs to get your final tax liability.
The deadlines for these are much more generous than the old system, giving you until 31st January of the following year to get everything sorted. The key is to stay on top of the dates. For instance, landlords with a qualifying income over £50,000 during the 2024-2025 tax year will need to start this process from 6 April 2026. You can read more about how the MTD deadlines affect landlord finances on Landlord Studio.
Feeling more confident? You should be. This new process is designed to make life easier, not harder. If you’re ready to get ahead of the curve and ensure your accounting is MTD-ready, get in touch with us at Artema. We can help you get set up and make your first submission a breeze.
Common Landlord MTD Questions Answered
Diving into something new like Making Tax Digital for landlords is bound to stir up a few questions. If your head is spinning with "what ifs" and "how does that work?", you're definitely not alone. We've gathered some of the most common queries we hear from landlords and cut through the jargon to give you clear, straightforward answers.
Let's clear up some of that confusion.
What If a Letting Agent Manages My Properties?
This is a classic question, and an important one. Even if you have a fantastic agent collecting rent and handling the day-to-day, the responsibility for MTD compliance is ultimately yours.
Think of your agent as a brilliant source of information. They provide the monthly statements, but it’s still down to you (or your accountant) to make sure that data gets into your MTD software and is correctly submitted to HMRC.
A great tip here is to ask your agent for their statements in a digital format, like a CSV file. This can make uploading everything into your software an absolute doddle, saving you from hours of manual data entry.
Do I Still Need an Accountant If I Use Software?
While the latest software can do a lot of the heavy lifting, logging every transaction with ease, a good accountant is still worth their weight in gold. They provide strategic tax advice that software simply can't – like spotting allowable expenses you might have missed and making sure your final tax position is as efficient as possible.
Many landlords we work with find that software handles the routine tasks, freeing up their accountant to provide high-value advice that saves them significant money in the long run. It’s a real dream-team partnership.
So, while you might not need an accountant for the button-clicking, their expertise can be a massive financial advantage.
What Happens If I Make a Mistake?
First off, don't panic! The quarterly updates aren't set in stone. We all make mistakes—like that time you thought you could fix the boiler yourself. If you realise you've forgotten an expense or entered a figure incorrectly, you can simply correct it in your next quarterly submission.
The legally binding figures are only confirmed when you submit your End of Period Statement (EOPS) and Final Declaration after the tax year has finished. This new system actually gives you far more flexibility to make adjustments along the way.
Does MTD Apply If My Properties Are in a Limited Company?
Here’s a clear-cut one for you: No, it doesn't. MTD for Income Tax Self Assessment (ITSA) is specifically for individuals who report property income on their personal tax return.
If your portfolio is held within a limited company, you fall under Corporation Tax rules. Your company might have its own MTD obligations for VAT, but it is not part of the MTD for ITSA regime this guide covers.
Feeling more prepared to tackle Making Tax Digital? Getting the right advice from the start makes all the difference. At Artema Ltd, we specialise in helping landlords navigate these changes with ease. Get in touch with us today to see how we can make your transition to MTD completely stress-free.