
Ever heard the phrase "quarterly tax returns" and felt a shiver run down your spine? Don't worry, you're not alone. It’s one of those business buzzwords that sounds way scarier than it actually is. The good news is, for most UK businesses, there isn't one single, scary, all-encompassing quarterly tax return.
Instead, think of it as a nice, predictable rhythm of reporting for specific taxes that just happens to be every three months. The most common one by a country mile is VAT.
So, What Are UK Quarterly Tax Returns, Really?
Let's clear the air. When people in the UK talk about quarterly tax returns, they're usually referring to a regular check-in with HMRC, not some massive final exam. It's less like a terrifying dissertation and more like a series of smaller, totally manageable assignments throughout the year.
This whole approach is designed to stop you from getting one giant tax headache at the end of the financial year. By breaking your reporting into four easy-to-handle chunks, you can stay on top of your finances without the last-minute panic. It’s a system built to make life easier for both you and the tax office.
The Big Picture: A Rhythm, Not A Single Return
The most important thing to grasp is that "quarterly tax returns" is just a catch-all term. It describes the frequency of reporting, not a specific form you have to fill out every three months.
The main players in this quarterly club are:
- Value Added Tax (VAT): This is the big one. If your business is VAT-registered, you'll almost certainly be filing a return every three months.
- Construction Industry Scheme (CIS): While contractors technically file monthly returns, the financial rhythm often feels quarterly as they juggle payments and deductions.
- Corporation Tax: This is less common for small businesses, but some very large companies pay their Corporation Tax in quarterly instalments. It’s like the VIP section of the quarterly tax world.
This quarterly system is the absolute backbone of the UK's tax collection, especially for VAT. To give you an idea of scale, in the 2023/24 financial year, total VAT receipts hit a mind-boggling £169 billion. The vast majority of that treasure chest was collected through these regular quarterly filings. You can see the full breakdown in HMRC’s official tax receipt statistics.
Who Needs to Bother With Quarterly Reporting?
So, who's actually on the guest list for this quarterly tax party? It’s not for everyone. This handy table gives you a quick summary.
| Business Type / Situation | Common Quarterly Obligation | Key Action |
|---|---|---|
| VAT-Registered Businesses | VAT Returns | File returns and pay any VAT due every 3 months. |
| Large Companies | Corporation Tax Instalments | Pay Corporation Tax in 4 chunks if your profits are over £1.5 million. |
| Construction Contractors | CIS Returns (Monthly) | Manage deductions and payments, often reviewed quarterly for cash flow. |
| Sole Traders (below VAT threshold) | None (Typically) | Phew! You can focus on the annual Self Assessment tax return. |
In short, if you run a VAT-registered business, this guide is your new best friend. If you're a sole trader flying under the VAT threshold, you can relax—your main focus is still your annual Self Assessment.
The goal is to swap tax anxiety for clarity. Managing quarterly obligations isn't some dark art; it's a normal and totally achievable part of running a successful business in the UK.
Ready to find out what's involved? Let's dive into the specifics of the main types of quarterly reporting.
Decoding The Main Quarterly Returns: VAT and CIS
When you hear someone mention "quarterly tax returns" in the UK, your mind should immediately jump to two main players: Value Added Tax (VAT) and the Construction Industry Scheme (CIS). While other financial deadlines pop up, these are the big ones that most small businesses will bump into.
Think of them as the most regular coffee dates you'll have with HMRC. Get to grips with them, and everything else starts to make a lot more sense.
Getting to Grips with VAT
VAT is the undisputed superstar of the quarterly reporting show. If your business turnover is creeping up towards the £90,000 per year threshold, you'll need to register. Once you're in the club, you'll almost certainly be filing VAT returns every quarter.
So, how does it actually work in practice?
- You become a tax collector for HMRC: You add VAT to your sales invoices and collect this extra cash from your customers on behalf of the government.
- You get to reclaim VAT: The good news! You can also claim back the VAT you've paid out on your own business expenses and purchases.
- You pay HMRC the difference: Your quarterly VAT return is a simple bit of maths. You take the VAT you've collected from sales, subtract the VAT you've reclaimed on your costs, and pay the rest to HMRC. Easy-peasy.
This three-month cycle is incredibly common. In fact, something like 95% of VAT payments are made by businesses submitting these quarterly returns. It’s a rhythm designed to match the typical accounting periods of most UK companies.
For limited companies, your quarterly prep should also factor in your future Corporation Tax bill. Getting a quick estimate with a handy Corporation Tax Calculator can really help with your financial planning and avoid any nasty surprises.
Demystifying the Construction Industry Scheme (CIS)
Now for the second piece of the puzzle: the Construction Industry Scheme (CIS). If you work in construction, this one’s for you. It isn't a separate tax, but a clever system to collect tax from subcontractors throughout the year.
Imagine you're a main contractor and you hire a self-employed electrician. Under CIS rules, you'd snip off a percentage of their payment and send it straight to HMRC. This acts as an advance payment towards the electrician's eventual tax bill.
The whole point of CIS is to reduce tax dodging in the construction sector by making sure tax is paid at the source. It keeps the cash flowing to the Treasury and stops anyone from "forgetting" to settle up later on.
Subcontractors then report these deductions on their own tax returns to show they've already paid a bit of tax. While contractors file CIS returns monthly, the financial management for both parties often lines up with a quarterly review. It's vital to know your role to stay compliant and keep your cash flow healthy.
On a related note, you might also be interested in our guide on the VAT Flat Rate Scheme, which can simplify VAT for certain businesses.
Navigating Key Deadlines and Penalties (Without Freaking Out)
Nothing quite gets the heart racing like a looming tax deadline. But when it comes to your quarterly tax returns in the UK, staying ahead of the dates is simpler than you might think. Let’s calmly walk through the key deadlines so you never have to break a sweat.
Try to think of them not as a threat, but as a predictable rhythm for your business year. This infographic shows the typical journey of a quarterly return, from making sales to hitting that sweet 'submit' button.
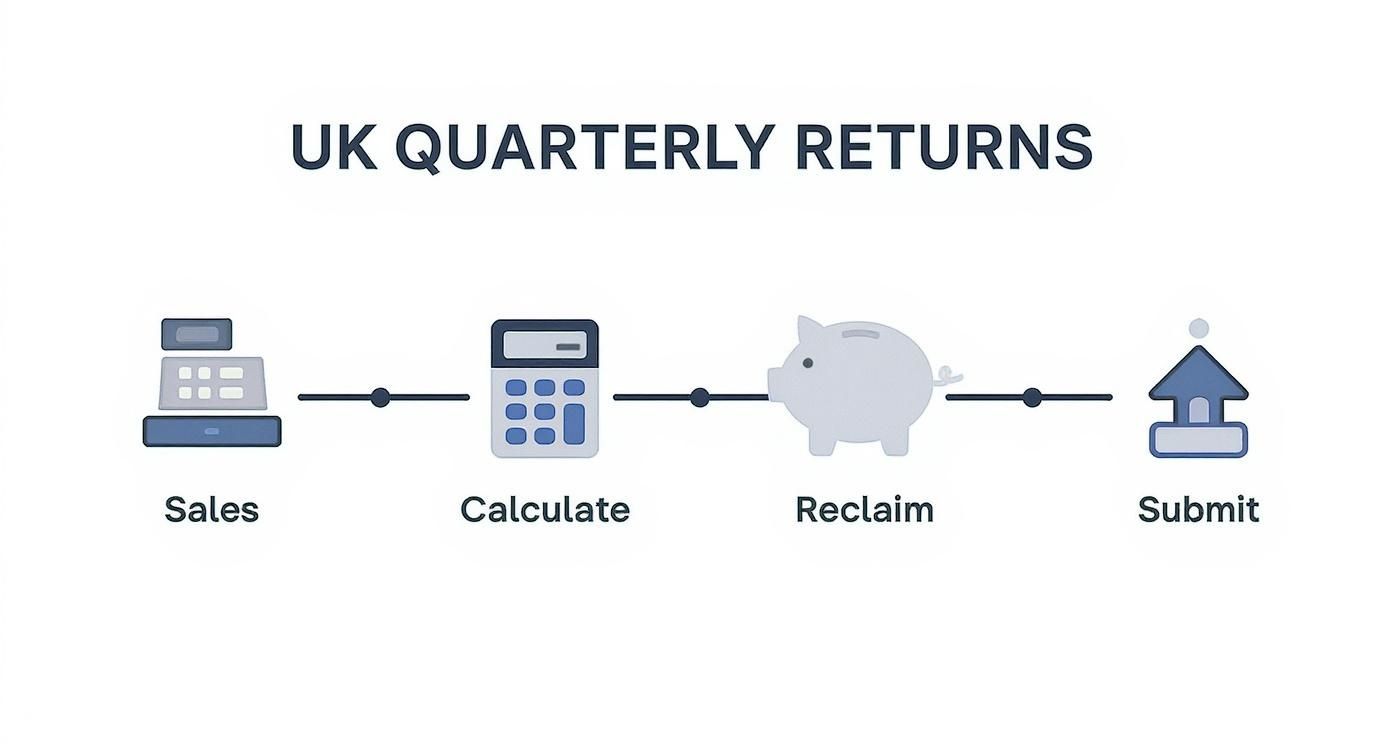
This handy timeline breaks the process down into four simple stages, showing that each step is a manageable part of a larger, logical cycle.
VAT Return Deadlines
For VAT, the rule is wonderfully straightforward. Your deadline to both file your return and pay what you owe is usually one month and seven days after the end of your three-month accounting period. It's a generous window, but one that can sneak up on you if you’re not organised.
Let’s say your VAT quarter ends on 31st March. Your deadline would be 7th May. Easy, right?
To help you visualise this, here’s what a typical year of VAT deadlines looks like.
Typical Quarterly VAT Deadlines
| VAT Quarter Period | Deadline for Return & Payment |
|---|---|
| 1 Jan – 31 Mar | 7 May |
| 1 Apr – 30 Jun | 7 August |
| 1 Jul – 30 Sep | 7 November |
| 1 Oct – 31 Dec | 7 February (of the next year) |
Of course, your own dates will depend on when you first registered for VAT, but the pattern of 'one month and seven days' always applies.
HMRC isn't trying to catch you out. The deadlines are consistent and predictable, designed to give you plenty of time to get your figures in order without a last-minute panic.
CIS Return Deadlines
For those in the construction industry, the rhythm is a little different. CIS returns are actually filed monthly. Contractors must file their return and pay any deductions by the 19th of every month. This deadline stretches to the 22nd if you pay electronically.
While the filing itself is monthly, many contractors we work with still manage their cash flow and financial reviews on a quarterly basis to align everything with their wider business planning.
What Happens If You’re Late? (The Not-So-Scary Part)
So, what if life gets in the way and you miss a deadline? First off, don’t panic. HMRC has moved away from instant fines for the odd late submission. Instead, they now use a penalty point system for VAT, which is actually quite fair.
Think of it like getting points on a driving licence.
- You get one penalty point for each late VAT return.
- Once you reach a certain threshold (it's four points for quarterly filers), you’ll get a £200 penalty.
- You’ll then get another £200 penalty for every late submission after that.
The key takeaway? A single slip-up won't automatically cost you. The system is designed to penalise persistent lateness, not genuine one-off mistakes. Better yet, your points can expire after a period of good behaviour, giving you a chance to wipe the slate clean.
Your Quarterly Tax Return Survival Kit
Alright, let’s get rid of the tax-time panic for good. Being prepared is the secret to a stress-free tax season, turning what feels like a massive headache into a simple, repeatable process. This is your practical, step-by-step checklist to make quarterly reporting feel almost routine.
Think of this as your pre-flight check before hitting 'submit'. By getting organised, you can finally say goodbye to that dreaded shoebox overflowing with faded receipts.
Tame The Paperwork Monster
First things first: your records. This isn't about creating a filing system worthy of a librarian; it's just about making sure you can find what you need, when you need it. The goal is to go from frantic searching to easy finding.
A great place to start is to go digital. Use your phone to snap pictures of receipts the moment you get them. Loads of accounting apps let you upload them directly, saving them from getting lost in a coat pocket or the car's glovebox forever.
The secret to stress-free tax returns isn't being an accounting genius. It's simply being organised enough to have the right information at your fingertips when the deadline rolls around.
This small habit makes a huge difference. Instead of that mad scramble at the end of the quarter, you’ll have a neat digital trail of all your expenses, ready and waiting.
Your Practical Checklist For Success
Ready to make your next quarterly tax return your smoothest one yet? Follow these simple steps throughout the quarter.
- Reconcile Your Bank Accounts Weekly: Don't let this pile up. Spend just 15 minutes each week matching your bank transactions to your invoices and receipts. It catches errors early and stops the job from becoming a monster.
- Keep Digital Copies of Everything: Ditch the paper. Scan or photograph all your invoices, receipts, and bank statements and store them securely in the cloud. No more hunting for that one crucial receipt!
- Use MTD-Compatible Software: This is a real game-changer. Modern accounting software does most of the heavy lifting for your quarterly tax returns in the UK. It can pull data from your bank, help categorise expenses, and calculate what you owe automatically.
Making sure your software is compliant is critical. You can find more details in our guide that explains if your accounts system is compliant with MTD for VAT.
As part of your survival kit, knowing what expenses you can claim is vital. For property investors, in particular, getting this right can make a big difference. For a deeper dive, this guide on UK rental property tax deductions is an excellent resource.
By following this checklist, you're not just preparing for a tax return; you're building a stronger, more organised business. If you need a hand setting up these systems, our friendly team is here to help you get everything running smoothly.
How Quarterly Reviews Can Boost Your Business
Let's be honest, the thought of quarterly tax prep doesn't exactly fill most of us with joy. But what if we stopped seeing it as a chore and started treating it as a secret weapon for business growth?
When you shift your mindset, reviewing your numbers every three months becomes a chance to spot trends, get a firm grip on your cash flow, and make smarter decisions. It’s your scheduled moment to pull yourself out of the day-to-day chaos and look at the bigger picture.
From Tax Hassle to Growth Tool
Think about it. Are your new services actually making money? Are your costs slowly creeping up? This is your chance to find out.
A regular review transforms the "hassle" of preparing your quarterly tax returns in the UK into a sharp business tool. It gives you the clarity to see what’s working and what isn’t, allowing you to tweak your strategy before a minor issue snowballs into a major problem.
Staying on top of your finances isn’t just for HMRC—it’s for you. Each quarterly review is a chance to check your business’s pulse and make sure it’s healthy, strong, and heading in the right direction.
This proactive approach means you're no longer flying blind. Instead of waiting until the end of the year to see how you did, you get four clear opportunities to steer the ship and make sure you hit your goals.
Asking the Right Questions
A great quarterly review is all about asking clever questions. Your financial data holds all the answers, you just need to know where to look.
Here are a few key areas to focus on:
- Profitability Check: Which products or services are your superstars? And are there any that are secretly costing you more than they’re worth?
- Cash Flow Analysis: Where is your money actually going? Understanding this helps you predict future cash flow and avoid any tight spots down the line.
- Goal Tracking: How are you progressing towards your annual targets? A quarterly check-in tells you if you’re on track or need to pick up the pace a bit.
Of course, having a bit of structure helps. To get you started, we've put together a free guide and checklist. You can find out more by checking out our quarterly business review template, designed to walk you through the process.
Ultimately, by treating each quarter as a mini-review, you turn a mandatory task into a real strategic advantage. It’s one of the simplest ways to build a smarter, more successful business.
A Few Lingering Questions?
Even the best guides can leave you with one or two niggling questions. That’s perfectly normal! Let's clear up a few of the most common queries we get about quarterly tax returns.
Think of this as the friendly FAQ section you wish came with every piece of flat-pack furniture—straightforward answers, no confusing diagrams.
Can I Change My VAT Quarters?
Yes, you absolutely can! When you first register for VAT, HMRC gives you your quarterly periods, but these dates aren't set in stone. You can ask to have them changed to line up better with your business's natural rhythm.
For instance, if your business has a massive sales push that ends in February, it would make sense for your VAT quarter to end then too. It’s a small change that can seriously simplify your life.
Do I Still Have to File a Return if I Owe Nothing?
This is a big one: yes, you do. Even if you have no VAT to pay or reclaim for a quarter, you must still submit what's known as a 'nil return' by the deadline.
Don't be tempted to skip it just because no money is changing hands. HMRC treats a late nil return exactly the same as any other late submission. You can still get a penalty point, so make sure it gets filed on time.
What if I Spot a Mistake on an Old Return?
First off, don't panic. HMRC knows that honest mistakes happen. If you’ve found an error on a past quarterly return, you can usually just correct it on your next one, as long as the mistake is below a certain threshold (which is typically £10,000).
For anything bigger, you’ll need to formally let HMRC know. The key is to be upfront and fix the error as soon as you find it. They are always far more understanding when you own up to a mistake.
Let Us Handle The Numbers For You
Feeling a bit dizzy after all that? You’re not alone. While managing your quarterly tax returns is certainly achievable, it's also a whole other job on top of running your business.
Why not hand over the number-crunching and get your time back? Imagine a world where you don’t have to worry about missing a deadline or making a costly mistake. Our expert team can take the entire burden of quarterly filings off your shoulders, making sure everything is submitted correctly and on time, every time.
We’re here to give you more than just compliant accounts; we’re here to give you peace of mind. Let us wrestle with the receipts and spreadsheets so you can get back to focusing on what you do best. It’s like having a financial superhero on your side, but without the cape (we checked, it’s a trip hazard). Discover the relief that comes from professional support and get back to growing your business.
Ready to make your tax life a whole lot easier? Get in touch with Artema Ltd today for a friendly, no-obligation chat. Book your consultation now and let’s get started.