
Let's be honest, the phrase "Self Assessment deadline" can strike fear into the hearts of even the most seasoned business owner. It sounds a bit like a final exam you forgot to study for, doesn't it? That sudden, cold feeling of "Oh no, did I miss something?" is a familiar horror for many.
The good news is that the deadlines are actually pretty straightforward, and with a little prep, you can avoid the mad January scramble. For the last tax year, you need to file your online return and settle your tax bill by midnight on 31st January. Phew, that wasn't so bad, was it?
Your No-Panic Guide to Self Assessment Deadlines
When you're dealing with Self Assessment, you’re essentially juggling two key dates: the deadline to file your tax return and the deadline to pay what you owe. Mixing these up is a common slip-up that can lead to unnecessary stress and, worse, penalties from HMRC.
Think of it like borrowing a library book—there’s a date you have to return it by, and then a date by which you need to pay any fines. Simple when you put it like that!
The most important thing to know is that your choice of filing method—online or traditional paper form—completely changes the timeline. While you technically can still send your return via Royal Mail (carrier pigeon is sadly no longer an option), the deadline for that is much, much earlier.
Key Dates for Your Diary
Nearly everyone files online these days, and for good reason. It gives you a crucial extra three months to get all your paperwork sorted. To make it crystal clear, let's look at the core dates you need to circle on your calendar for the tax year that ended on 5th April.
Key Self Assessment Deadlines at a Glance
For a quick overview, here's a simple table breaking down the main deadlines. It helps to see them side-by-side so you know exactly what’s due, and when.
| Action Required | Paper Return Deadline | Online Return Deadline | Final Payment Deadline |
|---|---|---|---|
| Submit Your Return | 31st October | 31st January | N/A |
| Pay Your Tax Bill | N/A | N/A | 31st January |
As you can see, 31st January is the big one. It's the final deadline for filing your return online and for paying any tax you owe from the previous tax year. Missing this single date can cause a world of pain.
The key takeaway? Filing online doesn't just simplify the process; it buys you valuable time. If you haven’t already, making the switch to digital is one of the smartest moves you can make for a stress-free tax season.
Feeling a bit overwhelmed by these dates? Don't worry, that's completely normal. At Artema, we turn tax-time dread into a simple, straightforward process. Get in touch today and let us handle the deadlines for you.
Do You Actually Need to File a Tax Return?
Ever find yourself staring at your laptop, wondering, "Does this whole Self Assessment thing even apply to me?" You're definitely not alone. It’s a common question, and the answer isn't always as straightforward as being a sole trader or a limited company director.
Many people get caught out because they assume tax returns are just for the self-employed. But HMRC’s net is much wider than that. Forgetting this can mean sailing past a crucial self assessment return date you never even knew you had.
Who Needs to Register for Self Assessment?
Beyond the more obvious candidates, a surprising number of situations will require you to get friendly with HMRC and file a tax return. If any of these sound familiar, it’s probably time to pay close attention.
You’ll almost certainly need to send a return if you have untaxed income from any of the following:
- Renting out a property: Becoming a landlord, even by accident, means you need to declare your rental income. This applies whether you're letting out a second home or just renting a spare room.
- A 'side hustle' or casual work: Did you make more than £1,000 from a passion project, freelance gigs, or selling things online? That’s your trading allowance, and anything you earn above it needs to be declared.
- Tips and commission: If you're in an industry where you get tips that aren't taxed through your main PAYE job, you'll need to report them.
- Income from savings or investments: This can include dividends or interest that isn’t already taxed before it hits your account.
- Selling valuable assets: Made a profit from selling shares, a second property, or other big-ticket items? You might need to report it for Capital Gains Tax.
Other Common Scenarios
It’s not just about extra income streams, either. Your employment status or total earnings can also pull you into the Self Assessment system.
For example, you'll need to file if you're a high earner with an income over £100,000. The same goes if you or your partner claimed Child Benefit and one of you had an income over £50,000. For a more detailed look at your specific situation, check out our guide explaining Self Assessment tax returns: https://www.artema.co.uk/useful-stuff/self-assessment-tax-returns-explained/
The golden rule is simple: if you've received income that hasn't been taxed before it lands in your bank account, you almost certainly need to tell HMRC about it. Ignoring it and hoping for the best is a risky game that rarely pays off.
For those with specific income streams, like short-term rentals, understanding what you can claim is vital when figuring out your filing duties. While UK rules apply here, you can see the kinds of things tax authorities consider by looking at these U.S. Short Term Rental Tax Deductions. The key is to be proactive and work out what you owe well before any deadlines loom.
Understanding Your Key Dates and Payments
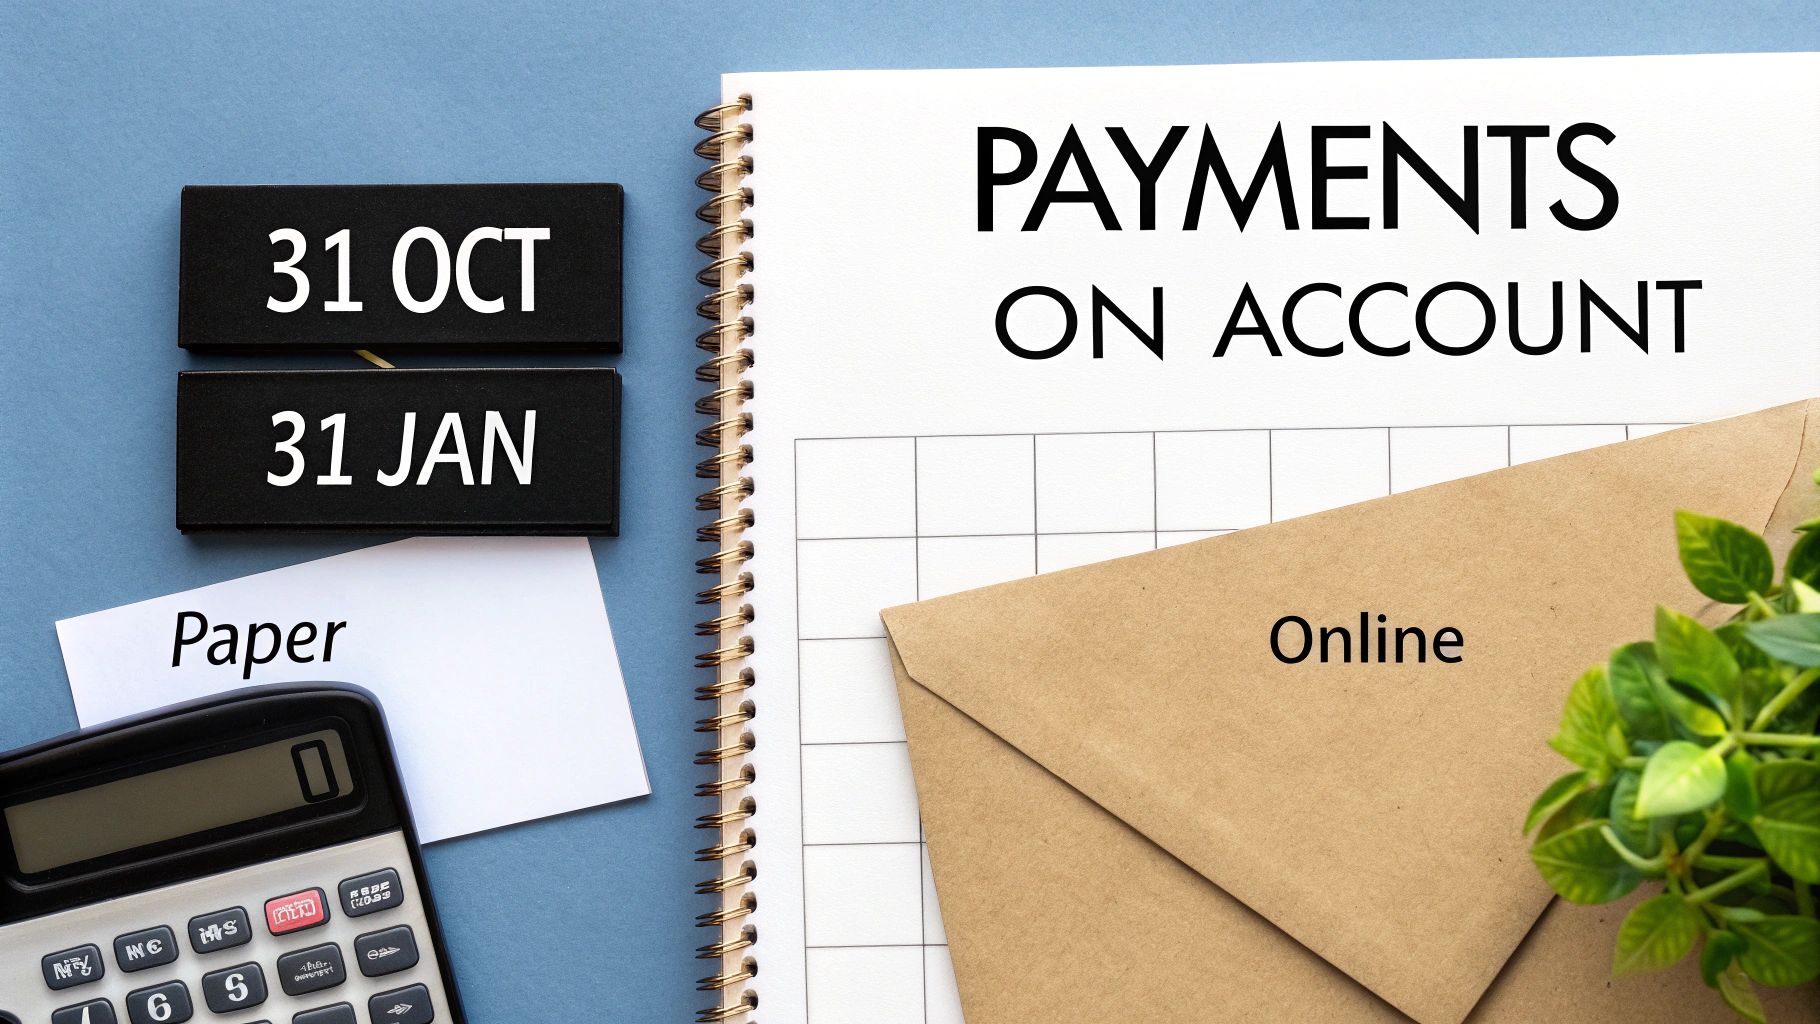
When it comes to your tax return, not all deadlines are created equal. The most important self assessment return date for you boils down to a simple choice: are you filing online or going old-school with pen and paper?
Think of it like sending a message. You could post a letter, or you could send an email. Both get there in the end, but one is a lot quicker and gives you much more breathing room.
Paper vs Online: The Great Deadline Divide
If you’re set on filing a paper tax return, you’ll need to be on the ball. Your deadline is midnight on 31st October. This date sneaks up surprisingly fast, usually when you’re more worried about Halloween costumes than tax codes.
On the flip side, filing online grants you a generous extension until midnight on 31st January. Those extra three months are a lifesaver, giving you proper time to pull together your documents, check your numbers, and sidestep that last-minute scramble.
It’s no wonder that the vast majority have gone digital. For the 2022 to 2023 tax year, a record 11.5 million people filed on time, with a massive 97.11% choosing to do it online. It's clear proof that the extra time and sheer convenience of online filing are just too good to ignore.
Demystifying Payments on Account
Just when you think you’ve got the main deadlines figured out, HMRC introduces something called 'Payments on Account'. It sounds scarier than it is, promise!
Imagine you're paying for a big holiday in instalments. Instead of one huge payment that makes your bank account wince, you pay a bit now and the rest later. That’s pretty much how Payments on Account work for your tax bill.
In simple terms, Payments on Account are advance payments towards your next tax bill. HMRC asks you to pay twice a year to spread the cost, helping you avoid a nasty financial shock in January.
You’ll typically need to make these payments if your last Self Assessment tax bill was over £1,000 and less than 80% of your income was taxed at source (like through a PAYE salary).
There are two dates you absolutely must have circled in your calendar:
- 31st January: This is when your first payment is due, along with any tax you still owe from the previous year.
- 31st July: Your second payment for the current tax year is due.
Each payment is usually 50% of your previous year's tax bill. For a deeper look at how it all adds up, check out our guide to self-employed Payments on Account. Getting your head around this system is crucial for managing your cash flow and keeping HMRC happy.
If this all sounds like a hassle you could do without, we’re here to help. Get in touch with Artema, and we'll make sure you never miss a deadline again.
What Happens If You Miss the Deadline?
So, the deadline flew by. Before you start hiding from the postman or considering a new life in a remote, non-extradition country, take a deep breath. Missing a Self Assessment return date isn’t ideal, but it’s a fixable problem. The goal now is to act calmly, understand the consequences, and get back on track without letting the situation spiral.
Think of HMRC like a strict but fair librarian. If you don't return your book on time, there's a small, predictable fine. If you ignore the reminders for months, those fines get much bigger. It’s the same with your tax return; HMRC has a clear, escalating penalty system designed to nudge you into action.
The Penalty Timetable Explained
The moment the 31st January deadline passes, an automatic penalty kicks in. This isn't personal; it's simply the system doing its job. The penalty structure is designed to get progressively more serious the longer you delay.
Here’s a simple breakdown of how the costs can stack up for late filing:
- One day late: You get an instant £100 penalty. This applies even if you have no tax to pay or have already paid your bill. It’s purely for the late submission.
- Three months late: After three months, HMRC starts charging a daily penalty of £10 per day, for up to 90 days. This can quickly add up to another £900.
- Six months late: At this point, you’ll face a further penalty of 5% of the tax you owe or £300, whichever is higher.
- Twelve months late: Another penalty of 5% of your tax liability or £300 (again, whichever is higher) is added. In the most serious cases, the penalty could be up to 100% of the tax due.
On top of these filing penalties, HMRC also charges interest on any unpaid tax, so it’s always in your best interest to pay as quickly as possible, even if you can't file yet.
What Is a Reasonable Excuse?
Now for a bit of good news. HMRC isn't completely heartless. They understand that sometimes, life just gets in the way. If you have a 'reasonable excuse' for missing the deadline, you may be able to appeal a penalty.
A reasonable excuse is something unexpected or outside your control that stopped you from meeting your tax obligations. Think serious illness, a family bereavement, or your computer exploding just before the deadline.
However, HMRC is very clear on what doesn't count. Forgetting, being too busy, your dog eating your receipts, or blaming your accountant are unlikely to get your penalty overturned. Honesty and prompt action are your best friends here.
If you find yourself in a difficult spot, it’s worth exploring your options. For more guidance, see our advice on how to come clean with HMRC without the panic. The key is to communicate clearly and provide evidence to support your claim.
Navigating penalties and appeals can be stressful. If you’re facing this situation, don’t go it alone. Reach out to the team at Artema. We can help you understand your position and communicate with HMRC effectively to minimise the damage and get you back in good standing.
Your Simple Timeline for a Stress-Free Tax Return
Leaving your tax return until the last minute is the financial equivalent of that mad trolley dash on Christmas Eve. It’s chaotic, stressful, and you’re almost guaranteed to forget something important. But what if you could swap that last-minute panic for a calm, organised approach?
Think of this simple timeline as your roadmap to a much more relaxed tax season. By breaking the whole process down into smaller, manageable steps, you can get your Self Assessment return sorted well before the deadline day rush.
Your Year-Round Action Plan
Getting ahead of your tax return isn’t about doing everything at once. It’s about tackling small tasks throughout the year, starting right after the previous tax year ends on 5th April.
- April – June (The Fresh Start): A new tax year has begun! This is the perfect time to get your record-keeping system in order. Create a dedicated folder for receipts, start logging your mileage, and make sure your bookkeeping software is ready to go.
- July – September (The Mid-Year Check-In): Don't wait until January to start digging out your documents. Begin gathering everything you’ll need now—P60s, bank statements, dividend vouchers, and records of any other income. If it's your first time filing, you need to register for Self Assessment by 5th October at the very latest.
- October – December (The Early Bird Advantage): Why not just file it now? Submitting your return early is a superpower. You'll find out exactly what you owe months in advance, giving you plenty of time to budget for the payment. Plus, if you’re due a refund, you’ll get it that much sooner!
This timeline shows just how quickly those late filing penalties can stack up, turning a small oversight into a much bigger problem.
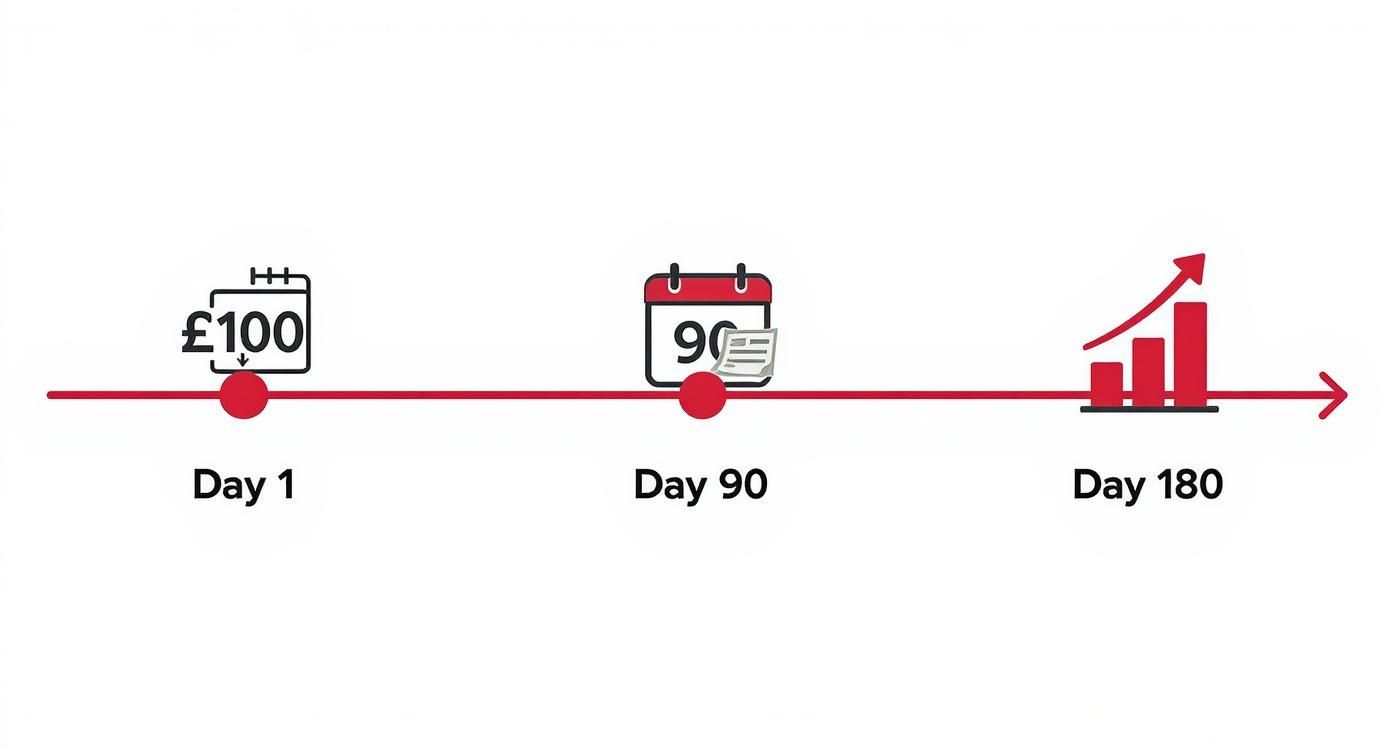
As you can see, putting off your submission leads to escalating costs, starting with an immediate fine and growing with daily charges. It’s a costly habit to get into.
The Final Push
- January (Deadline Month): If you haven't filed yet, now is the time. Don't be one of the deadline day crowd! On 31st January 2024, an incredible 778,068 returns were filed on the very last day, with thousands hitting 'submit' in the final hour before midnight. You can explore the deadline day statistics to see just how common the last-minute rush is.
- 31st January at Midnight: This is it—the final online filing and payment deadline. You need to submit your return and pay what you owe to avoid those automatic penalties.
Following this timeline turns a daunting annual task into a series of simple, bitesize steps. When you treat your Self Assessment as a year-long process rather than a one-day panic, you stay in complete control and keep your stress levels to an absolute minimum.
Feeling like this is still a bit much to handle on your own? Let us take the timeline off your hands. Contact Artema today and we’ll manage the entire process for you, ensuring a stress-free and timely submission, every single year.
Let an Expert Handle the Deadlines for You
Feeling a bit dizzy after all those dates, penalties, and timelines? It’s completely understandable. Keeping track of every self assessment return date can feel a bit like spinning plates – stressful and one small slip can lead to a mess.
But you don’t have to do it all yourself. This is where getting a professional on your side turns a daunting annual chore into a simple tick-box exercise. Think of us as your financial co-pilot, navigating the tricky bits so you can focus on where you're going.
How We Make Your Life Easier
Working with an expert accountant isn't just about filing on time. It's about gaining peace of mind and unlocking potential savings you might have missed along the way. We can help you:
- Never miss a deadline: We track everything for you, making sure your return is filed and paid correctly and on time. No more nasty surprises from HMRC.
- Find tax efficiencies: Our team knows the tax system inside and out. We can spot legitimate opportunities to reduce your bill that you might not be aware of.
- Free up your time: Let us handle the numbers so you can pour your energy back into what you do best—whether that's running your business, managing your investments, or simply enjoying your free time.
Getting professional help is an investment in your peace of mind. It’s about swapping late-night paperwork sessions for more time doing what you love, confident that your taxes are in expert hands.
Ready to ditch the deadline dread for good? Get in touch with Artema Ltd today for a friendly, no-jargon chat about how we can help.
Your Self Assessment Questions Answered
Still got a few things nagging at you? You're definitely not alone. The world of tax can feel like it has its own language, so let's clear up some of the most common questions about the Self Assessment return date and the whole process.
What If I Make a Mistake on My Tax Return After Filing It?
Don't panic! It’s far more common than you might think. HMRC actually makes it pretty easy to amend your tax return online, giving you a full 12 months after the official filing deadline for that tax year to make changes.
All you need to do is log in to your account, find the return you submitted, and select the option to make a change. It's another great reason to file early—fixing a mistake is a lot less stressful when you're not up against the clock.
Do I Still Have to File a Return if I Made No Profit?
Yes, in most cases, you absolutely do. Once you've registered for Self Assessment, HMRC expects a return from you every year until you officially tell them your situation has changed and you no longer need to file.
You must report all your income and expenses, even if this results in zero profit or a loss. In fact, declaring a loss can be a smart move, as you can sometimes use it to lower your tax bills in future years.
Can I Get an Extension on the Filing Deadline?
This is a big one. Unlike the tax systems in some other countries, HMRC almost never grants extensions on the 31st January deadline. It's pretty much set in stone.
The only exceptions are for truly extreme and unforeseeable circumstances, and you'd need to contact HMRC directly with very strong evidence. It’s always safest to assume the deadline is non-negotiable and plan accordingly.
Beyond tax-specific questions, you can also find general FAQ answers on various topics online.
Feeling like you could use a hand to make sense of it all? At Artema Ltd, we take the guesswork and the stress out of your Self Assessment. Visit us at artema.co.uk and let our friendly experts handle the deadlines for you.