
Let's be honest, the words "business accounting" don't exactly get your pulse racing, do they?
For many entrepreneurs, it feels like a chore—a confusing mess of spreadsheets and receipts that gets shoved to the bottom of an ever-growing to-do list. You'd much rather be perfecting your product or charming new clients. And who can blame you?
But what if I told you that getting a grip on your finances is the single most powerful move you can make for your business? The best small business accounting advice anyone can give is this: keep it organised from day one. That means opening a separate business bank account and tracking every single penny that comes in and goes out. Mastering this habit is the foundation for avoiding tax-season nightmares and making genuinely smart decisions.
Why Good Accounting Is Your Secret Weapon
Good accounting isn't about becoming a maths whizz; it's about understanding the story your money is telling you. Think of it as your business's health check, roadmap, and crystal ball all rolled into one. When you know your numbers, you can answer those big, scary questions with confidence.
From Chaos to Clarity
Running a business without clear accounting is like trying to bake a cake without a recipe. You might end up with something edible, but you'll probably make a huge mess, forget the sugar, and set off the smoke alarm.
Solid accounting practices give you that clear recipe for success. They empower you to:
- Make Smarter Decisions: Should you hire a new team member? Can you afford that shiny new piece of equipment? Your financial reports hold the answers.
- Reduce End-of-Year Stress: Imagine a world where tax season is just a calm, organised process instead of a frantic scramble for crumpled receipts found in the car's glove compartment. That world is entirely possible!
- Boost Your Confidence: Knowing your exact financial position gives you the confidence to negotiate with suppliers, apply for funding, and set ambitious goals.
The goal isn't just to do accounting; it's to use accounting. It's about turning numbers on a page into real insights that fuel growth, reduce risk, and give you, the business owner, genuine peace of mind.
This guide is designed to be your friendly co-pilot on this journey. We'll skip the jargon and give you practical, straightforward small business accounting advice tailored for UK entrepreneurs.
You're not just another statistic; you're part of the engine driving the UK economy. In fact, an estimated 5.49 million SMEs make up over 99% of all UK businesses—a testament to the nation's entrepreneurial spirit. You can explore more about these small business statistics to see the big picture.
Now, let's get your finances sorted so you can get back to doing what you love.
Building Your Financial Foundation
Getting your financial house in order from day one is the difference between a minor headache and a full-blown migraine later on. This section is all about creating that solid foundation, starting with a few simple, non-negotiable steps.
The very first piece of small business accounting advice anyone should give you is this: open a separate bank account for your business. It might seem like an extra bit of admin, but believe me, mixing your personal and business spending is a recipe for absolute chaos.
Imagine trying to figure out if that £3 coffee was a client meeting or a personal treat a year from now. When your finances are tangled, you risk missing out on legitimate tax deductions and giving HMRC a massive headache—which usually becomes your massive headache.
Sole Trader or Limited Company
Once your banking is separate, you need to think about your business structure. For most new UK businesses, this comes down to being a sole trader or a limited company. From a financial perspective, the difference is huge.
- Sole Trader: You and the business are legally the same entity. It’s simpler to set up, but there’s no financial separation. This means your personal assets could be on the line if the business runs into trouble. Yikes.
- Limited Company: The business is a separate legal entity. This protects your personal assets and can be more tax-efficient once you start earning above a certain threshold, but it comes with more formal reporting requirements.
Deciding which path to take is a critical first step. For those looking at different international structures, understanding the difference between Inc and Corp in Canada provides a good example of how crucial these distinctions are.
Cash vs Accrual Accounting Explained
Next up is choosing your accounting method. This sounds technical, but it’s just about when you recognise your income and expenses. The two main options are cash and accrual.
Let’s use a simple coffee shop analogy.
Imagine you sell a coffee on 30th March, but the customer pays you on 2nd April.
- Cash Method: You record the income on 2nd April, the day the cash actually hits your bank account. It’s simple and shows your immediate cash flow. Easy peasy.
- Accrual Method: You record the income on 30th March, the day you made the sale (and earned the money), even though you haven’t been paid yet. This gives a more accurate picture of your profitability over a specific period.
Most small businesses start with the cash method because it’s so straightforward. However, as you grow, the accrual method provides a much clearer view of your business's financial health. Keeping on top of these transactions is where many business owners feel overwhelmed, but dedicated professional small business bookkeeping solutions can take this entire task off your plate.
Choosing the right accounting method isn't just a technicality; it's about seeing your business clearly. Cash accounting shows you the money in your pocket today, while accrual accounting gives you a true performance review for the month or quarter.
Creating a Simple Budget That Works
Finally, let's talk about budgeting. Forget rigid spreadsheets that make you feel trapped. A good business budget is a flexible roadmap, not a cage.
Start by looking at your last three months of business expenses. Group them into categories like:
- Fixed Costs: Rent, software subscriptions, insurance (things that don't change month to month).
- Variable Costs: Stock, marketing spend, shipping (things that fluctuate with sales).
- One-Off Purchases: A new laptop, office furniture.
Once you see where your money is going, you can set realistic spending targets. Your budget isn't there to stop you from spending; it's there to ensure you're spending smartly. It helps you plan for big purchases, anticipate quiet months, and invest in growth with confidence. A simple budget is your guide to building a profitable and sustainable business.
Choosing Your Accounting Toolkit
You wouldn't use a fork to dig a foundation, so why use the wrong tools for your business finances? Picking the right accounting toolkit is a critical piece of advice that will save you from future meltdowns. Let’s have an honest, jargon-free look at your options, so you can choose a system that feels like a helping hand, not another chore.
When you're first starting out—maybe it's a side hustle or you're just testing the waters—a simple spreadsheet can feel like the perfect solution. And for a little while, it is! It's free, familiar, and gets the basic job done of tracking money in and money out.
But there's always a tipping point. That trusty spreadsheet starts to groan under the weight of your success. You find yourself manually creating invoices, chasing payments, and spending hours trying to figure out your profit, all while risking a tiny typo that could throw everything off. That’s the moment your simple tool becomes a serious liability.
The Great Debate: Spreadsheets vs Software
The truth is, spreadsheets are brilliant for many things, but they were never designed to be a robust accounting system. They lack the automation and accuracy that a growing business desperately needs. This is where dedicated accounting software steps in—not as a complex burden, but as your new best friend.
Imagine a world where invoices are sent automatically, payment reminders go out without you lifting a finger, and your bank transactions are categorised for you. That’s not a distant dream; it’s what modern accounting software does. It transforms your bookkeeping from a manual data-entry marathon into an efficient, automated process.
The real value of accounting software isn't just in logging numbers. It's in the time it gives back to you—time you can spend on growing your business, serving your customers, or maybe even taking a well-deserved afternoon off.
For a clearer picture, this table breaks down when each tool really shines.
Choosing Your Accounting Tool: A Quick Comparison
| Feature | Best for Spreadsheets | Best for Accounting Software |
|---|---|---|
| Business Stage | Brand new side hustles or pre-trading businesses with very few transactions. | Any established business, from sole traders to limited companies. |
| Cost | Essentially free (if you already have the software like Excel or Google Sheets). | Monthly subscription fee, but saves significant time and money in the long run. |
| Key Function | Basic income and expense tracking. Good for simple lists. | Full financial management: invoicing, payroll, VAT returns, reporting, bank feeds. |
| Automation | None. Everything is manual, which is time-consuming and prone to errors. | High. Automates invoicing, payment reminders, bank reconciliation, and more. |
| Accuracy | Prone to human error. One wrong formula can throw everything off. | High. Direct bank feeds and built-in calculations reduce the risk of mistakes. |
| Scalability | Very limited. Becomes unwieldy and chaotic as your business grows. | Excellent. Grows with your business, handling more complex needs as you expand. |
As you can see, while a spreadsheet might work for day one, it quickly becomes a bottleneck. Dedicated software is built to handle the complexities of a real, growing business.
Finding the Right Fit for Your Business
Choosing software isn't about picking the one with the most features; it's about finding the one that fits your specific business. The needs of a freelance photographer are worlds apart from those of a local bakery with staff and stock to manage.
Here in the UK, a few key players tend to dominate the small business scene:
- Xero: Known for its user-friendly and beautiful interface, Xero is fantastic for business owners who want a clear, visual overview of their finances. It’s particularly strong for service-based businesses and connects with hundreds of other apps.
- QuickBooks: A powerhouse in the accounting world, QuickBooks is incredibly versatile. It’s great for businesses that manage stock or have slightly more complex needs, offering robust reporting that can grow with you.
- FreeAgent: Specifically designed for UK freelancers, contractors, and very small businesses, FreeAgent is celebrated for its simplicity. It excels at managing project-based work and simplifies tax estimations, making it a favourite among sole traders.
Here’s an example of the Xero dashboard, which shows a clean, at-a-glance view of key financial metrics.
This kind of visual summary helps you instantly see your cash flow, outstanding invoices, and upcoming bills, turning confusing data into clear, actionable insights.
Making the switch to a professional system is a sign of growth. Many business owners find that moving their bookkeeping into a dedicated platform is a game-changer for efficiency. If you're exploring your options, our guide on cloud-based accounting can help you understand the benefits of having your financial data accessible anytime, anywhere. This move isn't just about software; it's about building a scalable financial workflow that supports your ambitions.
Ultimately, the best tool is the one you will actually use. Don't get swayed by a long list of features you'll never touch. Instead, focus on a system that feels intuitive and solves your biggest bookkeeping headaches. Most platforms offer free trials, so take them for a spin and see which one clicks. Your future self, especially around tax time, will thank you for it. Ready to make a choice? Get in touch and we can help you find the perfect accounting software for your business needs.
Creating a Daily Financial Rhythm
Great financial management isn’t about one heroic, spreadsheet-fuelled weekend a year. It's about building simple, consistent habits that keep you in the loop without taking over your life.
Think of it less like cramming for a maths exam and more like brushing your teeth—a small, daily action that prevents much bigger problems down the line.
Let's build a financial rhythm for your business. This isn't about becoming an accountant overnight; it's about creating a simple routine that gives you a constant, clear view of your business's financial pulse. No more nasty surprises when the tax bill arrives.
Taming the Receipt Monster
Every small business owner has a version of "the receipt monster." It might be a shoebox stuffed with crumpled papers, a chaotic folder on your desktop, or a glove compartment that looks like a paper recycling bin exploded. This monster feeds on disorganisation and causes major stress.
The best piece of small business accounting advice for taming this beast is to go digital. Your smartphone is your secret weapon here. Apps like Dext, Hubdoc (which often comes with Xero), or even the mobile app for your accounting software can capture receipts in seconds.
- Snap a picture the moment you get a receipt—after buying a client coffee, paying for parking, or ordering new supplies.
- The app reads the data using clever technology, pulling out the vendor, date, and amount.
- It syncs directly with your accounting software, ready to be categorised.
This tiny habit, taking just five seconds, saves you hours of painful data entry later and ensures you claim every single legitimate expense you're entitled to.
This infographic shows how your accounting tools can evolve as your business grows, moving from manual entry to powerful automation.
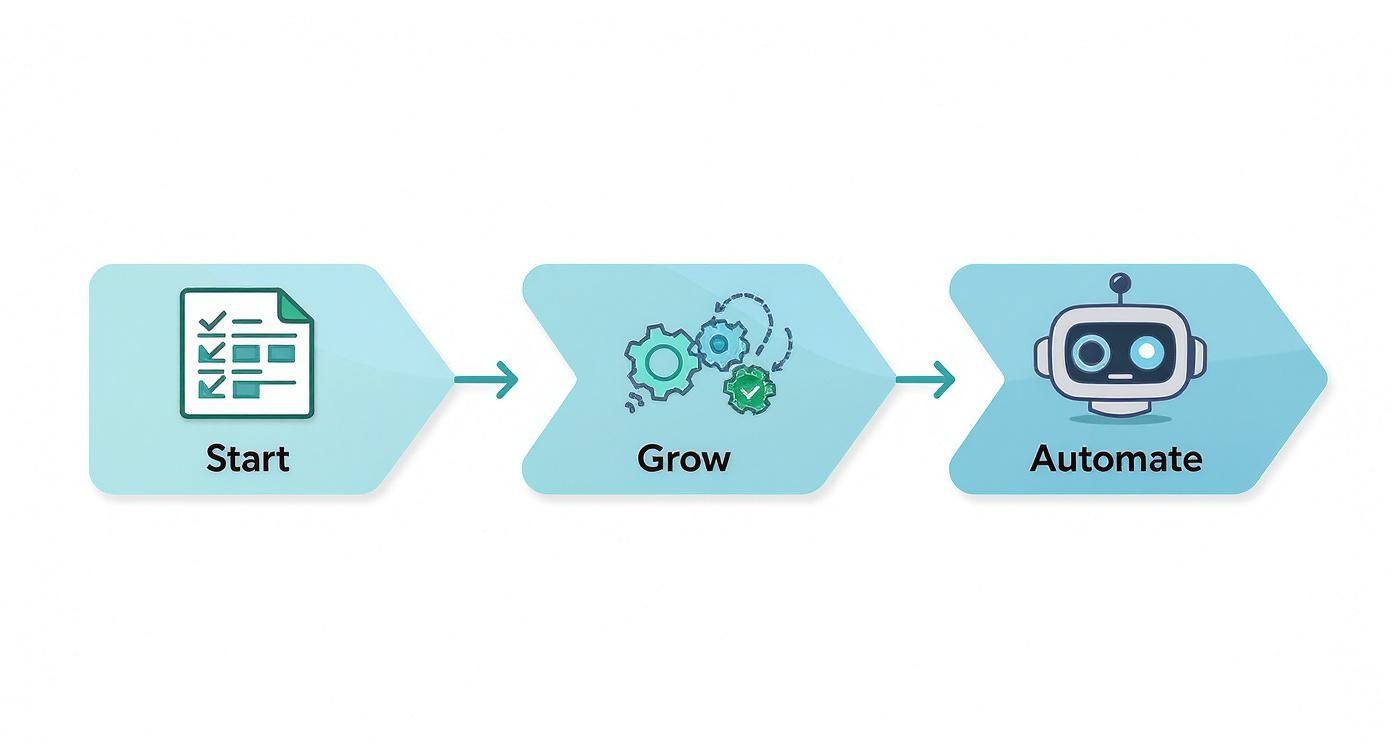
The key takeaway here is that as your business complexity increases, your tools should automate more of the manual work, freeing you up for more important tasks.
Getting Paid Without the Pain
Creating invoices is how you get paid, so let's make them work for you. A professional invoice does more than just ask for money; it makes it easy for your clients to pay you promptly.
Your invoices should always include:
- A unique invoice number
- Your business name and address
- The client's name and address
- A clear description of the services or products sold
- The date of the invoice and the payment due date
- Clear payment details (your bank account number and sort code)
Don't be shy about your payment terms. If you expect payment within 14 days, state it clearly. If you charge interest on late payments (which you're legally entitled to do), include that information too.
Of course, even with the perfect invoice, you'll eventually encounter a late payer. Chasing payments is awkward, but it’s a necessary part of business. For practical strategies on maintaining a healthy financial flow, delve deeper into managing cash flow effectively.
A polite, firm, and automated follow-up process is your best defence against late payments. Most accounting software can send automatic reminders when an invoice is due or becomes overdue. You write the email templates once, and the system does the awkward chasing for you.
Your Monthly Financial Health Check
Once a month, set aside an hour to sit down with your numbers. This isn't about finding mistakes; it’s about understanding your business's story. Pour a cup of tea (or something stronger, we don't judge) and look at three key things:
- Income: Where did your money come from? Which clients or products were most profitable?
- Expenses: Where did your money go? Are there any surprising costs creeping up?
- Profit: What's left over after all the bills are paid? This is your profit margin.
This monthly check-in is your early warning system. It helps you spot trends, like rising supplier costs or a dip in sales from a certain service, long before they become serious problems.
By building these simple daily, weekly, and monthly habits, you turn accounting from a dreaded task into a powerful tool. You’ll feel more in control, make smarter decisions, and have a much clearer path to growth.
Making Sense of Your Financial Reports
Let's be honest, the financial reports your accounting software churns out can look a bit intimidating. Filled with columns of numbers, they often feel like they’re written in another language—one designed for accountants who dream in spreadsheets.
But here’s the thing: those reports are telling you the story of your business. They aren’t just for your accountant or HMRC; they are your most powerful tools for making smart, confident decisions. Let’s break down the two most important ones into plain English.
The Profit and Loss Story: Money In vs. Money Out
First up is the Profit & Loss (P&L) statement. Don't let the name put you off. It’s simply a summary of your business's performance over a set period, like a month or a quarter.
Think of it as a scoreboard. It adds up all your income (money in) and then subtracts all your expenses (money out). What’s left at the end is your profit or loss. It answers the most fundamental question in business: “Am I actually making any money?”
For instance, a freelance graphic designer might look at her P&L for March and see:
- Income: £4,000 from client projects.
- Expenses: £500 for software subscriptions, £200 for a new monitor, and £300 for marketing.
- Total Expenses: £1,000.
- Net Profit: £3,000.
This simple report tells her she’s had a great month. But it can also flag problems. If her software costs suddenly jumped to £1,500, she’d know immediately that something was wrong and could investigate. It’s your first line of defence against runaway costs.
The Balance Sheet Snapshot: What You Own vs. What You Owe
Next, we have the Balance Sheet. If the P&L is a movie of your finances over time, the Balance Sheet is a single photograph. It captures your financial position on one specific day.
It shows two things:
- Assets: Everything your business owns that has value (like cash in the bank, equipment, and money your clients owe you).
- Liabilities & Equity: Everything your business owes (like supplier bills or a business loan) plus the owner's investment in the business.
The golden rule here is that Assets must always equal Liabilities + Equity. There’s a reason it’s called a balance sheet—it has to balance! This gives you a clear picture of your business's overall financial health. A healthy business will almost always have more assets than liabilities.
These reports are more than just numbers; they are diagnostic tools. A P&L showing shrinking profit margins might tell you it's time to raise your prices. A Balance Sheet with very little cash could be a warning sign to chase up unpaid invoices before you hit a cash flow crunch.
Understanding these reports is particularly crucial right now. UK small businesses are feeling the pressure from rising operational costs. In early 2025, a staggering 85% of SMEs reported an increase in their costs, which put a significant squeeze on their finances. You can discover more insights about these UK small business statistics at capsulecrm.com. Regularly reviewing your P&L helps you stay ahead of these rising costs and protect your bottom line.
These reports form the core of what are known as management accounts, which are essential for strategic planning. If you want to dive deeper, you can learn more about how management accounts can drive your business forward.
By taking a little time each month to get to grips with these two reports, you move from just running your business to truly leading it. You’ll be able to spot opportunities, fix problems before they get out of hand, and plan your future with genuine confidence.
Feeling like you need a hand translating your business story? That’s what we’re here for. Get in touch with us at Artema, and we can help you turn your financial reports into your greatest asset.
Got a Few Lingering Accounting Questions?
Feeling a bit more in control of your business finances but still have a few questions buzzing around? That's completely normal. Getting to grips with business accounting is a journey, not a destination, and it's natural to have "what if" or "how do I" moments.
To help you out, we’ve tackled some of the most common questions we hear from small business owners just like you. Here are some straight-talking answers to bring you a bit more clarity.
Can I Just Pay Myself Whatever Is Left in the Bank?
Ah, the dream question! While it’s tempting to view your business bank account as a personal piggy bank, it’s not quite that simple. This is honestly one of the most critical pieces of small business accounting advice we can give.
That money sitting in your business account has a few jobs to do before it can land in your pocket:
- Future Expenses: You'll need cash for upcoming stock orders, software renewals, or that marketing campaign you’ve been planning.
- Tax Obligations: A good chunk of that balance belongs to HMRC for VAT, Corporation Tax, or your personal tax bill. Don't get caught short.
- A Cash Cushion: It's always smart to keep a buffer for unexpected costs or a slow sales month. Peace of mind is priceless.
Instead of just taking what’s left, it's far better to decide on a fixed, regular salary or draw. This creates stability and predictability for both you and your business finances.
How Long Do I Need to Keep My Receipts?
In the UK, the rule of thumb is to hold onto your financial records for at least six years from the end of the last company financial year they relate to. This goes for both sole traders and limited companies.
But please, don't just chuck them in a shoebox under the stairs! Digital copies are perfectly fine with HMRC and are infinitely easier to organise and search. Just snapping a quick picture with an app is all it takes to keep things in order. It's a tiny habit that prevents a massive headache down the line.
Think of your digital receipt archive as your financial safety net. You might never need to look at a specific receipt from four years ago, but if you do, you'll be incredibly grateful it’s just a quick search away instead of buried in a dusty box.
Do I Really Need an Accountant if I Use Software?
This is a fantastic question, and the answer really depends on your own confidence and how complex your business is. Accounting software is brilliant for keeping your day-to-day transactions organised, but it can’t replace strategic, forward-looking financial advice.
A good accountant does so much more than just file your tax returns. They can help you:
- Structure your business in the most tax-efficient way possible.
- Spot opportunities for growth that you might not see in the numbers.
- Make sure you're complying with all of HMRC’s ever-changing rules.
- Act as a sounding board for big decisions, like hiring staff or making a large investment.
Think of it this way: your software is the car, but your accountant is the expert driver who knows all the shortcuts and how to avoid the traffic jams. The software does the heavy lifting, while the accountant provides the direction and expertise to get you where you want to go. For most business owners, that partnership is the real key to financial peace of mind.
Feeling like you could use an expert in the driver's seat? At Artema Ltd, we turn your financial data into clear, actionable guidance. We're here to answer all your questions—big or small—and help you build a stronger, more profitable business. Let's have a chat about how we can support you.