
Think of small business tax deductions as a secret handshake with HMRC that saves you money. For every quid you spend on a legit business cost, you get to shrink your taxable profit.
It’s a simple trick that means you keep more of your hard-earned cash. This isn't some dodgy loophole; it's exactly how the system is designed to give small business owners like you a well-deserved break.
How Tax Deductions Actually Cut Your Bill (The Fun Bit)

It’s easy to get lost in tax jargon, but the idea behind deductions is refreshingly simple. Let’s say you run a small coffee shop. All the money that comes in from selling lattes and croissants is your revenue. From that lovely pile of cash, you get to subtract—or deduct—all the costs of running the shop.
These costs are your business expenses. By taking them away from your revenue, you lower your 'profit on paper.' It's this final, smaller number that HMRC actually taxes. It feels a bit like magic, but it’s completely legal and, in fact, encouraged.
The Golden Rule: "Wholly and Exclusively"
So, what counts as a legit business cost? HMRC has a golden rule for this: the expense must be "wholly and exclusively" for business purposes. Don’t let the formal language scare you. It just means the money was spent purely for your business, not for your weekend shenanigans.
Back to our coffee shop. The cost of coffee beans, milk, staff wages, and your shop's rent are all clearly 100% for the business. Easy. But what about your personal weekly grocery shop? That’s for you, not the business, so it doesn't count. Sorry!
The goal isn't to pay zero tax. It's to make sure you only pay tax on your actual profit, not your total revenue. Nailing this is the first step to becoming a tax-savvy boss.
Here’s a quick look at how claiming everyday business expenses can dramatically shrink your final tax bill for a made-up business with £50,000 in revenue.
How Claiming Expenses Slashes Your Taxable Profit
| Scenario | Taxable Profit | Corporation Tax at 19% (Example) | Tax Saved |
|---|---|---|---|
| Business A: Claims no expenses (Oops!) | £50,000 | £9,500 | £0 |
| Business B: Claims £20,000 in expenses | £30,000 | £5,700 | £3,800 |
As you can see, just by tracking and claiming its costs, Business B keeps an extra £3,800 in its bank account. That’s a serious chunk of change you could pour back into your business.
Seeing Expenses in a New Light
Once you get the hang of this, you’ll start seeing your business costs differently. Every legitimate purchase becomes a secret weapon for lowering your tax bill.
Here’s how it works in the real world:
- Software Subscriptions: That monthly fee for your accounting software like Xero? Deductible.
- Marketing Costs: The money you splurged on Facebook ads to find new customers? Deductible.
- Office Supplies: The endless mountain of pens and printer paper? You guessed it—deductible.
This isn’t about being sneaky; it’s about being smart. By tracking and claiming every allowable expense, you make sure your final tax bill is as fair and low as possible. It’s a core part of running a healthy, profitable business. Ready to see where you can save?
The Ultimate "Can I Claim This?" Checklist
Think of this section as your treasure map to finding hidden cash. We’re about to turn confusing government guidance into a simple checklist, pointing out the expenses you already know about and, more importantly, the ones you might be missing.
This isn't about finding dodgy loopholes. It's about confidently claiming every pound you're legally entitled to. Let's dive in and start ticking things off the list.
Office and Premises Costs
This is the bread and butter of business expenses for most people. Whether you rent a swanky office or run your empire from the kitchen table, many of your running costs are claimable.
- Rent and Utilities: If you have a dedicated business space, the rent, business rates, electricity, gas, and water are all deductible. Easy peasy.
- Office Supplies: Every pen, notepad, ink cartridge, and box of paperclips adds up. Keep the receipts for all your stationery and office bits and bobs.
- Software and Subscriptions: Your monthly fee for Xero, Adobe Creative Cloud, or your project management tool is 100% a business expense.
Working From Home Expenses
Running your business from home? High five! You can claim a portion of your household bills. HMRC knows you’re not using your entire house for work (unless you live in a tiny flat with a giant desk), so you can’t claim everything.
There are two main ways to do this:
- HMRC’s Flat Rate: This is the super-simple option. If you work from home for more than 25 hours a month, you can claim a set monthly amount. It’s quick and saves you from doing any maths.
- Calculate a Proportion: For a more accurate claim, you can work out the business percentage of your actual household bills (like council tax, mortgage interest or rent, and utilities). For example, if your home office is one of ten rooms, you could claim 10% of those costs.
Whichever method you choose, consistency is key. Pick one and stick with it for the tax year. This keeps your records neat and tidy, which HMRC loves.
Marketing and Professional Costs
Getting your name out there and keeping your skills sharp costs money, and thankfully, HMRC gets that. These small business tax deductions are vital for growth.
- Advertising: Money spent on Google Ads, social media campaigns, print flyers, or sponsoring the local football team is all deductible.
- Website Costs: Your domain name registration, hosting fees, and paying a web developer to make your site look pretty are all claimable.
- Professional Subscriptions and Insurance: Are you a member of a professional body? That fee is deductible. So is your professional indemnity or public liability insurance.
- Bank Charges: Don't forget those pesky monthly account fees or transaction charges. They are a cost of doing business and can be claimed.
Travel and Vehicle Expenses
This is where people often get in a muddle, but the rules are simple once you know them. The key is knowing the difference between a 'commute' and 'business travel'.
Your daily trip from home to your permanent workplace (like your office or shop) is a commute, and you cannot claim for it. Sorry to be the bearer of bad news!
However, you can claim for:
- Mileage: If you use your personal car to visit a client, a temporary worksite, or to pick up supplies, you can claim mileage. The current approved rate is 45p per mile for the first 10,000 miles.
- Other Travel Costs: Train tickets, bus fares, and taxi rides for business-related journeys are all fair game.
- Accommodation and Subsistence: If you have to stay overnight for a business trip, your hotel costs and reasonable meal expenses are deductible. Just don't try to claim for a five-star spa weekend!
Staff and Equipment Costs
Your team and your tools are essential, and their costs are some of the most important small business tax deductions you can make.
- Salaries and Pensions: The wages you pay your employees, employer's National Insurance contributions, and pension contributions are all deductible.
- Training: Sending an employee on a course to improve their skills for their role is a claimable expense.
- Small Tools and Equipment: Everyday items like a new keyboard, office chair, or small tools for your trade can usually be claimed as a day-to-day expense.
- Larger Assets: What about a big purchase, like a new company van or fancy computer? These are treated differently. You can’t usually claim the full cost as a simple expense. Instead, you claim it through capital allowances, which let you deduct a portion of the value over several years. It's a bit more complex but super valuable; you can learn more about how capital allowances on commercial property and assets work to max out your claims.
Feeling more confident? This checklist is your starting point. The next step is understanding how these rules might change based on your business structure. Let's keep going.
How Deductions Work for Your Business Structure
When it comes to tax deductions, HMRC definitely doesn't do 'one-size-fits-all'. The rules you need to follow depend entirely on your business structure—whether you're a sole trader, running a limited company, or a landlord.
Think of it like coffee: a sole trader is a simple, strong espresso—the business and the owner are one and the same. A limited company is more of a layered latte, where the business is a completely separate legal entity from its owner. Each one needs a slightly different approach.
Let’s break down the rules that apply directly to you.
Sole Trader Deductions: The Direct Hit
If you're a sole trader, the link between your expenses and your tax bill is beautifully simple. Every allowable expense you claim directly reduces your profits.
Since you pay Income Tax on those profits, a lower profit means less tax. Simple as that. Spend £100 on essential software, and you’ve just knocked £100 off the profit figure that HMRC looks at.
For a deeper dive, check out our complete guide on sole trader tax deductions to make sure you're not leaving any money on the table.
Limited Company Deductions: A Corporate Affair
For a limited company, things are a little more formal. Your company is its own legal 'person', which means it pays Corporation Tax on its profits.
Allowable business expenses reduce the company's profit before this tax is calculated. A lower profit means a smaller Corporation Tax bill.
Historically, Corporation Tax rates have been on quite a rollercoaster. The Small Companies' Rate, introduced back in 1973 at around 40%, plummeted to 25% by the 1980s. By 2017, the main rate was down to just 19%.
While the main rate has recently increased for larger companies, businesses with profits under £50,000 still benefit from the 19% small profits rate, keeping more cash in the company. You can explore the history of Corporation Tax rates to see just how these shifts have played out.
For limited companies, expenses have a double whammy effect. They cut the immediate Corporation Tax bill and can also be used to pay directors (that's you!) in a tax-savvy way through salaries and dividends.
Landlord Deductions: Keeping Your Property Profitable
Are you a landlord renting out property? HMRC sees you as running a property business, which means you have your own special set of rules. You can deduct costs that are "wholly and exclusively" for the purpose of renting out your property.
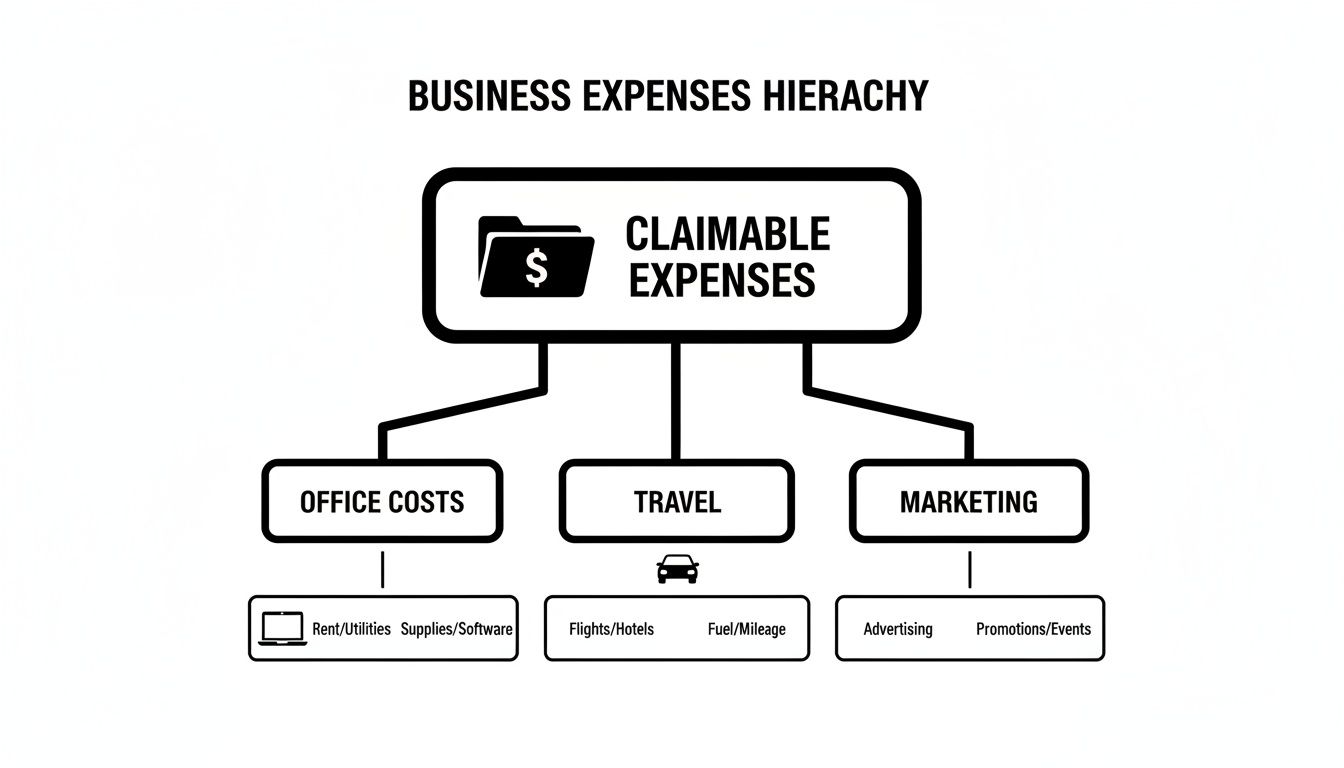
This gives you a good idea of where to look. Core business functions like your office costs, travel, and marketing are all prime areas for finding deductions.
Here are some classic landlord-specific examples:
- Letting Agent and Management Fees: The fees you pay an agency to find tenants or manage the property are fully deductible.
- Repairs, Not Improvements: This is a crucial one. Fixing a leaky roof or replacing a broken boiler is a repair and can be claimed. Installing a brand-new conservatory, however, is an improvement and cannot be claimed as a running cost.
- Landlord Insurance: The cost of your buildings, contents, and liability insurance policies are all allowable expenses.
Getting to grips with the rules for your setup is the key to unlocking maximum tax efficiency. No matter what, the goal is always the same: to accurately report your costs and pay the right amount of tax—and not a penny more.
Keeping Records Without the Headache

If tax deductions are the treasure, then solid records are the map. The mere mention of "record-keeping" can make even the calmest business owner break out in a cold sweat, picturing mountains of faded receipts and overflowing shoeboxes.
But it doesn't have to be a nightmare. Creating a perfect, stress-free paper trail is easier than you think. Let’s make it simple.
What HMRC Actually Wants to See
HMRC isn't trying to catch you out; they just want proof that your claims are legit. Think of it as showing your work in a maths exam. Your records are the evidence that backs up the numbers on your tax return.
So, what do you need to keep?
- Proof of Sales: All your invoices and bank statements showing money coming in.
- Proof of Expenses: Receipts, purchase invoices, and bank statements showing what you've spent. This is the golden ticket for your deductions.
That’s it. It’s not a secret formula. You just need a simple way to keep track of it all.
Your Toolkit for Staying Organised
Forget complicated systems. The best method is the one you’ll actually use.
- The Spreadsheet Approach: A well-organised spreadsheet is a perfectly fine way to log your income and expenses. It’s simple, free, and gets the job done.
- The Digital Revolution: This is where things get exciting. Modern accounting software, like Xero, is a total game-changer. Connect it to your business bank account, and it pulls in transactions automatically.
The real magic of going digital is the receipt handling. Snap a photo of a receipt with your phone the moment you get it, and the software stores it safely in the cloud. Goodbye, faded, crumpled bits of paper!
Being organised isn't just about pleasing HMRC. It gives you a crystal-clear view of your business's financial health, helping you make smarter decisions all year round.
How Long to Keep Your Records
Here’s the bit that often surprises people. HMRC expects you to hang on to your records for longer than you might think. Don't be tempted to have a ceremonial bonfire of your old receipts on the 1st of February.
For most businesses, the rule is to keep records for at least five years after the 31 January submission deadline of the relevant tax year. That’s a long time, which is another great reason to go digital.
Historically, good records have always been key. Back in the early 2000s, the government introduced a zero-rate corporation tax on the first £10,000 of profit. New company formations jumped a massive 45%! Having clear financial records was crucial to prove they were eligible. You can read about this fascinating shift in UK tax policy for more details.
Ready to stop worrying about paperwork? We can help you set up a simple system that works for you. Give us a shout for a friendly chat about making your record-keeping effortless.
Common Tax Mistakes and How to Sidestep Them
Let's talk about the banana peels of the tax world. Even the most careful business owner can slip up, but we're here to help you stay firmly on your feet.
Navigating your tax return can feel like a tightrope walk. But avoiding the most common mistakes is easy—it’s all about knowing where the pitfalls are so you can gracefully step around them.
Mixing Business with Pleasure
This is the number one slip-up. It’s so tempting to pay for a personal dinner with the business card "just this once," but this habit quickly turns your accounts into a messy spaghetti junction.
HMRC is crystal clear on the "wholly and exclusively" rule. When you mix personal and business spending, it becomes incredibly difficult to prove which costs were for your business. The easiest fix? Open a separate business bank account and use it for business stuff only. Simple.
Getting a Bit Too Creative
We’ve all heard the stories. While it’s funny to think about, you absolutely cannot claim your pet poodle as 'head of security' or your family's weekly takeaway as 'staff catering'. Believe us, HMRC has heard it all before.
A good rule of thumb is to ask yourself: "Would I have spent this money if I didn't have my business?" If the answer is a clear no, it's probably a legitimate expense.
Some "creative" claims that are definitely not allowed include:
- Your daily commute: The journey from your home to your normal place of work is not claimable.
- Personal clothing: That sharp new suit generally doesn’t count, unless it’s a specific uniform or essential protective gear.
- Entertaining UK clients: Unfortunately, taking a potential client out for a fancy lunch isn't a deductible expense in the UK.
Misunderstanding Big Purchases
You’ve just bought a shiny new van for your business. Fantastic! But you can't just list the full £20,000 price tag as a simple expense this year.
Large, long-lasting assets like these are treated differently. You claim their value over time through a system called capital allowances. Getting this wrong is a common error that can easily get your tax return flagged for a closer look.
This isn't about being penalised for investing in your business. It's just a different set of rules for big-ticket items versus day-to-day costs. Getting it right ensures you claim the maximum you're entitled to.
What if HMRC Wants a Chat?
The thought of an envelope from HMRC landing on your doormat can be scary, but it doesn't have to be a nightmare. A tax enquiry is usually just a request for more information to clarify things.
Inspectors simply want to see that the figures on your return are supported by the records you’ve kept. This is the moment your organised paperwork becomes your absolute best friend.
Recent data shows that small businesses accounted for 56% of the total £35.8 billion tax gap in 2022-23. A big chunk of this is down to honest mistakes. You can read the full analysis on the UK tax gap to understand better.
Your best defence against any enquiry is a solid, organised record-keeping system. If you can quickly pull up the receipt for every claim you've made, the whole process is usually smooth and stress-free.
Feeling a bit wobbly on that tightrope? Don't worry, we're here to be your safety net. Get in touch with us today, and let's make sure your tax affairs are accurate and straightforward.
Let Us Handle the Numbers So You Can Get Back to Business
Feeling a bit overwhelmed by all this? It’s completely normal. Juggling the ins and outs of tax deductions on top of, well, everything else is a huge ask. It can feel like you need a degree in accounting just to run your company.
This is where we come in. We live and breathe this stuff so you don't have to.
Your Expert Finance Team, Minus the Boring Suits
We partner with powerful, user-friendly software like Xero to make your financial admin feel effortless. Say goodbye to that shoebox full of faded receipts and those late-night spreadsheet headaches for good.
To really reclaim your time, many business owners delegate tasks like bookkeeping. After all, great record-keeping is the foundation of a stress-free tax season, and reliable professional bookkeeping services can be an absolute game-changer.
Our team offers more than just year-end accounts. We provide proactive advice all year round, helping you make smarter, more tax-efficient decisions that actually help your business grow.
Think of us as your financial co-pilot. We handle the navigation (the numbers and tax rules) so you can focus on flying the plane (growing your amazing business).
Let us take the stress out of your finances. Our accounting services for small business are designed to free you up, so you can get back to what you love doing.
Ready to make tax season feel less like a chore and more like a simple checkbox on your to-do list? Get in touch today for a friendly, no-obligation chat. We'd love to help.
Frequently Asked Questions
Welcome to the quick-fire round! We’ve gathered the most common questions we hear about small business tax deductions and answered them in plain English. No jargon, just straight-up advice.
Can I Claim Expenses if I'm Not Making a Profit Yet?
Yes, absolutely! You can, and definitely should, claim for all your business expenses even if you're making a loss. It shows HMRC the full picture of your start-up journey.
These losses can often be carried forward to lower your tax bill in future, more profitable years. It’s a vital way the system supports new businesses while they get on their feet.
What’s the Difference Between an Expense and a Capital Allowance?
Great question, as this one catches lots of people out. Let's imagine you're setting up your new office.
An expense is for your day-to-day running costs—things that get used up quickly, like pens or your monthly software subscription. You claim the full cost against your profit in the year you buy them.
A capital allowance is for buying a big, long-lasting asset, like a powerful new computer or a company van. Instead of claiming the whole cost at once, you deduct a portion of its value from your profits over several years.
Do I Need an Accountant to Claim Deductions?
There’s no law saying you must have one, but a good accountant is like a secret weapon. You can file on your own, but an expert will often save you more money in missed deductions and tax planning than their fee costs.
They know the rules inside-out, can spot savings you didn’t know existed, and make sure your records are perfect. It brings peace of mind and frees up your time to focus on what you do best.
How Do I Claim for Using My Car for Business?
For sole traders, the simplest way is to use HMRC's 'simplified expenses' mileage allowance. It’s a no-fuss method that saves you from tracking every single petrol receipt.
You can claim a flat rate of 45p per mile for the first 10,000 business miles you drive in a tax year, and 25p per mile for anything over that. This rate is designed to cover everything from fuel and insurance to general wear and tear. Just remember to keep a log of your business journeys!
Feeling clearer but still want an expert in your corner? Let Artema handle the numbers so you can focus on driving your business forward. Get in touch with us today for a friendly, no-obligation chat.