
That Sinking Feeling: What Is an HMRC Voluntary Disclosure Anyway?
We’ve all been there. That sudden, stomach-lurching memory of some cash-in-hand work from a few years back. The nagging suspicion you slightly fudged a figure on a tax return. Or perhaps an inheritance you weren't quite sure what to do with. The little voice in your head starts whispering, and suddenly, you’re picturing a terrifying brown envelope from HMRC crashing onto your doormat.

But before you start practising your best "who, me?" face, let's look at this differently. Making a voluntary disclosure to HMRC isn’t about being in trouble; it's about taking charge. It’s your chance to tell the taxman about any unpaid tax before they get their magnifying glass out and come looking for you.
Putting It Simply
Think of it like finding a library book you forgot about for a year. Instead of waiting for the overdue notices to morph into a fine big enough to buy the entire library, you march back in, explain what happened, and pay the small fee. HMRC sees a voluntary disclosure in a similar light – they'd much rather you owned up than have to chase you for it.
It's basically you saying, 'Oops, I've spotted a mistake and want to make it right.' This simple act of honesty is the secret sauce to the whole process and can massively reduce stress and penalties.
Who Is This For?
A voluntary disclosure isn't just for super-villains stroking white cats. It’s a common and sensible tool for perfectly normal people and businesses who’ve found themselves in a bit of a muddle.
You might need to make a disclosure if you're a:
- Freelancer who didn’t declare all the earnings from that unexpected project.
- Landlord who completely forgot about the rental income from that one little flat.
- Small business owner who made a bit of a mess with VAT calculations.
- Individual who received money from abroad and thought, "What on earth are the rules for this?"
In short, it’s for anyone who realises their tax situation isn't quite shipshape and wants to sort it out like a grown-up.
Why Bother Coming Forward?
It's tempting to shove the problem in a drawer and hope it magically disappears. But let’s be real, HMRC has some seriously clever tools to find unpaid tax, and their computers are getting smarter every year. The longer you leave it, the bigger the headache will be.
By making a voluntary disclosure, you’re grabbing the steering wheel. You get to explain what happened in your own words, which almost always results in smaller penalties than if HMRC kicks off a full-blown investigation. It’s a manageable process that puts you back in control.
Throughout this guide, we'll demystify the entire journey, showing you how coming forward is the smartest move for your bank balance and your sanity. If you're feeling that sinking feeling, don't panic. Give us a call today, and let's have a chat about how we can help you fix it.
The Awesome Benefits of Fessing Up Voluntarily
We’ve all done it. That little mental trick where you ignore a problem, hoping it will quietly tiptoe away. But when that problem has "HMRC" written on it, it’s a gamble you’re almost guaranteed to lose. Being proactive isn't just a good idea; it's the only sensible one.
Think of an unexpected letter from HMRC as the engine warning light flashing on your car's dashboard. Sticking a bit of tape over it doesn't fix the problem. It just means the eventual breakdown will be way more dramatic and expensive. Making a voluntary disclosure to HMRC is like booking the car in for a service yourself, at a time that suits you.
Slash Those Scary Penalties
Let's be honest, the biggest worry is usually the hit to your wallet. The single greatest perk of coming forward is the chance to dramatically shrink the penalties you'll face. HMRC is a bit like a strict but fair headteacher; they are much kinder if you own up to breaking a rule before you're caught.
When you take the first step, you're making what's called an ‘unprompted disclosure’. This simple action tells HMRC that the error wasn't a cunning plan to dodge tax, and they reward that honesty with a smaller fine.
The difference in penalties between coming forward yourself and being found out by an HMRC investigation can be eye-watering. You’re essentially taking control of the financial outcome instead of leaving it up to chance.
Avoid the Dreaded Tax Investigation
Beyond the financial savings, fessing up helps you dodge the massive stress of a formal tax investigation. An investigation isn't just a quick phone call. It’s a deep, intrusive dive into your finances that can be incredibly time-consuming and, frankly, a bit scary.
By making a voluntary disclosure, you can often sidestep this entire ordeal. You’re putting all your cards on the table from the start, which usually satisfies HMRC and lets everyone move on much more quickly. This means:
- Less Stress: No more sleepless nights wondering what an inspector might dig up.
- More Control: You're the one in charge, managing the process of gathering the facts and presenting your case.
- Fewer Costs: A formal investigation can quickly rack up big bills for professional help.
Ultimately, it’s about solving the problem and getting on with your life. The UK's tax gap—the difference between tax that should be paid and what’s actually collected—is forecast to hit an estimated £45 billion by 2025. Voluntary disclosures are a key tool for closing this gap, which is precisely why HMRC encourages taxpayers to come forward. You can find more insights into the reasons for voluntary disclosures and the tax gap on yogatax.co.uk.
Protecting Your Reputation (and Future)
In more serious situations, especially where mistakes were deliberate, a voluntary disclosure can be the critical move that stops things from escalating to a criminal prosecution. By coming forward, you’re showing a clear desire to make things right, which is a massive plus point in HMRC’s book.
For any business owner, landlord, or professional, keeping a clean record with HMRC is vital. A full-blown investigation can leave a lasting stain, whereas a settled disclosure is just a resolved admin issue. It’s about drawing a line under the past and building your financial future on solid ground.
At the end of the day, making a voluntary disclosure to HMRC is about being able to sleep at night. It’s the relief of knowing you’ve dealt with a problem head-on and can stop dreading the postman.
If you’re ready to take control and put a tax issue behind you for good, get in touch with our friendly team today. We can guide you through the process and help you get the best possible result.
Choosing the Right Path for Your Disclosure
Okay, you’ve decided to come clean. That’s a huge first step, and a really smart one. But what’s next? How do you actually do it? Not all tax slip-ups are created equal, and HMRC has a few different doors for people looking to set things straight.
Think of it like posting something important. You wouldn’t send a birthday card via a tracked, insured courier. And you wouldn't just pop a priceless vase in a standard postbox and cross your fingers. Picking the right service ensures it gets where it needs to go without any drama. It's the same idea when making a voluntary disclosure to HMRC.
Taking the wrong route can lead to unnecessary delays and a whole heap of stress, so let's break down the main options without the gobbledygook. This decision tree gets straight to the point: coming forward leads to a much better outcome, while hiding only makes things worse.
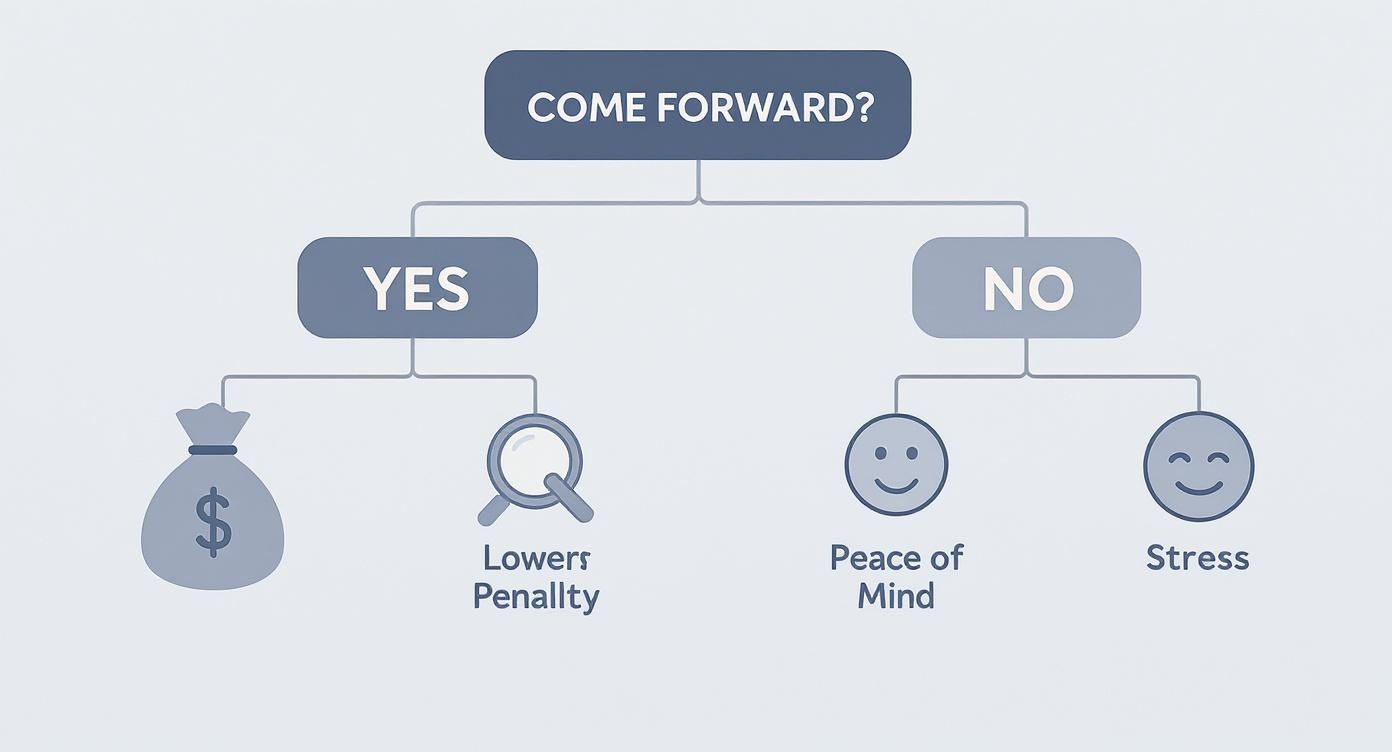
The picture makes it crystal clear—being proactive is the only sensible choice. It promises a smoother ride and, just as importantly, far less worry.
The Everyday Route: The Digital Disclosure Service (DDS)
For most common slip-ups, the Digital Disclosure Service (DDS) is your first port of call. This is HMRC’s standard online portal, built for people who’ve made a mistake with things like Income Tax, Capital Gains Tax, or National Insurance.
Think of the DDS as the main reception desk at HMRC. It’s the go-to option for straightforward disclosures, like:
- Forgetting to declare the income from your weekend side hustle.
- Not realising you needed to pay tax on the rent from a property you let out.
- Making a simple maths error on your Capital Gains Tax after selling something.
The whole thing is handled online and is designed to be as user-friendly as possible. If your mistake was down to carelessness or a genuine misunderstanding, this is almost certainly the right door for you.
The DDS is built for honesty and simplicity. It’s for taxpayers who've made a genuine mistake and want a clear, structured way to fix it without a fuss.
The Serious Route: The Contractual Disclosure Facility (CDF)
Now for the more formal option. The Contractual Disclosure Facility (CDF), often known by its code name "Code of Practice 9" (COP9), is for situations where tax fraud is suspected. This is the "tracked and insured courier" we mentioned earlier—it's for serious, complex cases.
You'd typically use the CDF if you have deliberately misled HMRC. We’re talking about things like intentionally hiding income or creating fake invoices to lower your tax bill. It’s a formal, legally binding deal between you and HMRC.
In return for a full and brutally honest disclosure of all tax mistakes, HMRC agrees not to pursue a criminal investigation. It offers immunity from prosecution, but it demands total transparency in return.
This isn’t a route to wander down lightly, and it almost always needs expert advice. If you think this might apply to you, don’t delay—speak to an expert immediately. Understanding the difference between these paths is the first critical step toward a successful voluntary disclosure to HMRC and finally putting the whole thing to bed.
Right then, let's get this sorted. You've decided to tackle the issue head-on, which is always the best approach. So, how does making a voluntary disclosure to HMRC actually work? It might sound like a huge, scary task, but it's really just a simple, three-stage process.
Think of it like a big financial spring clean. There's a bit of gathering and sorting to do at the start, but the peace of mind you get once it's done is priceless. The key is to be totally honest and thorough – that way, you can be sure you’ve drawn a final line under the matter.
Stage 1: Registration – The Official "Hello"
First things first, you need to tell HMRC that you're planning to make a disclosure. This is your formal way of saying, "Hi, I've got something to sort out." Most people do this by registering for the Digital Disclosure Service (DDS).
This step is vital because it officially starts a 90-day clock. From the day you register, you have exactly 90 days to pull all your info together and submit the full disclosure. Don't let that deadline freak you out; it's usually plenty of time if you stay organised.
By telling HMRC first, you make sure your disclosure is ‘unprompted’. This is crucial for getting those lower penalties we talked about earlier, as it proves you’re taking the initiative.
Stage 2: Disclosure – The Main Event
Now for the real work. During this 90-day window, you’ll need to put on your detective hat and dig into your own finances to figure out exactly how much tax is owed.
Here’s what you’ll be doing:
- Gathering Paperwork: This means finding all the relevant documents, like bank statements, invoices, rental agreements, or anything else related to the income you missed.
- Calculating the Tax: You'll need to work out the unpaid tax for each year involved. This can be the trickiest bit, especially when you add the interest that has built up.
- Assessing Your Behaviour: Have a think about why the error happened. Was it a simple mistake (careless), or was it more deliberate? Your answer here will directly affect the penalty percentage.
- Completing the Forms: Finally, you’ll pull all this information together and fill out the disclosure forms, giving HMRC a complete and honest picture.
Accuracy is king at this stage. If you're unsure about the kind of info required, our guide on Self Assessment tax returns explained is a great place to start, as a lot of the same principles apply.
The goal here is simple: give HMRC a complete and accurate picture. Leaving things out, even by accident, just complicates things down the line. It’s far better to be a bit over-the-top with the detail now.
Stage 3: Payment – Settling Up
Once your disclosure is sent off, HMRC will review it. Assuming they're happy with the details, they'll send you an acceptance letter with a payment reference number. You're on the home stretch!
The final step is to pay the total amount due, which covers the tax, any interest, and the penalty. HMRC offers several ways to pay, and it’s important to settle up as quickly as you can.
But what if you can't pay it all at once? Don't have a meltdown. HMRC can be reasonable. If you think you'll struggle, you can often arrange a 'Time to Pay' agreement, which lets you clear the debt in instalments. The most important thing is to be upfront and talk to them.
To make it even clearer, here's a quick summary of the journey:
Key Stages of an HMRC Voluntary Disclosure
| Stage | What It Involves | Key Tip |
|---|---|---|
| 1. Registration | Telling HMRC you want to make a disclosure, usually via the Digital Disclosure Service (DDS). This starts a 90-day countdown. | Act fast! Registering makes your disclosure 'unprompted', which helps lower potential penalties. |
| 2. Disclosure | Gathering all your financial documents, calculating the tax and interest, assessing your behaviour, and submitting the formal disclosure. | Be thorough and accurate. A complete disclosure avoids delays and more questions from HMRC. |
| 3. Payment | Getting HMRC's acceptance and making the full payment (tax, interest, and penalty). | If you can't pay in one go, contact HMRC right away to discuss a 'Time to Pay' arrangement. |
Making a voluntary disclosure to HMRC is a structured process designed to help you get your tax affairs back in order. By following these steps, you can sort out the issue efficiently and move on with your life. If any of this feels overwhelming, don't hesitate to reach out to us for a friendly chat. We’re here to make the journey as smooth and stress-free as possible.
Understanding Penalties, Timelines, and Offshore Income
https://www.youtube.com/embed/FDgC13sCYeA
Right, let's talk about the bit that causes the most sleepless nights – the penalties. It's easy to imagine HMRC plucking a huge, scary number out of thin air, but the reality is much more structured. And a little less terrifying, especially when you’re in control.
Think of it like a speeding ticket. The fine you get depends on how fast you were going and where you were caught. An HMRC penalty isn’t a one-size-fits-all punishment either. It’s calculated based on a few key things, and understanding them is your first step to minimising the damage.
How HMRC Calculates Penalties
The size of your penalty really boils down to two simple questions: Why did the mistake happen, and how did you tell them about it?
First, HMRC looks at your behaviour. Was it a genuine mistake made with the best of intentions? They call that ‘careless’. Or was there a deliberate attempt to pay less tax? The penalty for a deliberate error is, unsurprisingly, much higher.
Second, they look at whether your disclosure was ‘unprompted’ (you told them first) or ‘prompted’ (they found the issue and asked you about it). This is the golden rule of disclosures: telling them before they ask always gets you a better deal.
Coming forward before HMRC sends that dreaded letter is the single most powerful thing you can do to reduce your penalty. It’s the difference between saying, "I've messed up" and being told, "We've found your mess."
How Far Back Does HMRC Look?
Another common worry is how many years of dusty old bank statements you'll need to dig out. This ‘look-back’ period also depends on your behaviour.
- For careless errors, HMRC can usually go back 4 years.
- If the error was deliberate, they can look back as far as 20 years.
This is why being honest about the reason for the error is so important. A simple mistake has a much shorter time frame, making the whole process of putting things right a lot more manageable.
The Special Rules for Offshore Income
Now, let's add a bit of spice to the mix: offshore income. If your tax problem involves money or assets held outside the UK, the rules get much stricter and the penalties get much, much bigger. HMRC takes a particularly dim view of undeclared offshore income.
While penalties for deliberate UK tax errors can reach 100% of the tax owed, this can rocket up to a whopping 300% if it involves offshore assets. Coming forward voluntarily is the only way to get a significant reduction.
This is because global tax transparency is a huge deal now. Tax authorities worldwide share information automatically, making it almost impossible for offshore money to stay hidden. For complex situations, particularly those involving undeclared foreign income, understanding the nature of external financial crimes investigations can provide useful context for your disclosure.
Figuring out your tax duties for foreign income can be complicated, especially when it comes to your tax residency. You can learn more about how your residency status and overseas tax are connected in our detailed guide.
No matter what, the core message is the same. Coming forward voluntarily is your best, and frankly, your only sensible move to minimise the damage and get your affairs in order.
When to Call for Backup (aka Professional Tax Advice)
Trying to handle a tax disclosure on your own can feel a bit like assembling flat-pack furniture with the instructions in a different language. You might get there in the end, but you’ll probably be left with a few mystery screws, a wonky door, and a major headache. Sometimes, calling in an expert is the smartest move you can make.
This final section explains why getting professional help for your voluntary disclosure to HMRC can be a real game-changer, turning a scary process into a manageable one.
Speaking the Same Language as HMRC
A specialist tax advisor is fluent in a language most of us find baffling: "HMRC-speak". They understand all the fiddly bits of tax law and know exactly what inspectors look for. That expertise is priceless.
An advisor can help you:
- Check your calculations to make sure you're paying the right amount – no more, no less.
- Negotiate penalties and payment plans on your behalf, often getting a much better outcome than you could on your own.
- Provide crucial support during what can be a very anxious time, answering your questions and guiding you every step of the way.
Think of it not as a cost, but as an investment. You're investing in a smoother process, a better financial result, and most importantly, your own peace of mind.
When Is It Time to Call in the Pros?
While some super-simple disclosures can be handled alone, you should seriously think about getting expert help if your situation feels even slightly complicated.
If you’re feeling overwhelmed, or if your case involves large sums, multiple years, or offshore assets, seeking professional advice is a brilliant step toward a successful resolution.
The right expert can turn a tangled problem into a clear plan. If you’re looking for that clarity and support, our team of friendly tax advisors is here to help you get your tax affairs back on track. Don't hesitate to reach out for a confidential, no-obligation chat.
Common Questions About HMRC Disclosures
Still got a few questions buzzing around in your head? You're not alone. The world of tax can sometimes feel like you've been handed a rulebook for a game you've never played.
So, let's clear up some of the most common queries people have when they're thinking about making a voluntary disclosure to HMRC. This is your handy FAQ section to help you see the path forward more clearly.
How Long Does a Disclosure Take?
Once you've told HMRC you plan to make a disclosure, a 90-day countdown begins. During this time, you need to gather your information and send off your full disclosure.
After that, the timeline can vary. If your situation is fairly simple, HMRC might wrap things up in a few weeks. More complex cases can take several months, but the most important thing is that you've started the process. You're no longer looking over your shoulder.
Will HMRC Launch an Investigation Anyway?
This is a big worry for many, but the answer is almost always no. The entire point of a voluntary disclosure is to get ahead of the problem and avoid a formal, intrusive tax investigation.
By coming forward with a full and honest account, you’re giving HMRC all the information they would be looking for anyway. As long as they believe you’ve been completely transparent, they are usually happy to settle the matter and close the file. It saves them time, and it saves you a world of stress.
Think of it this way: you’re basically doing the investigation for them and handing them the findings. In most cases, they'll appreciate the effort and close the book on the matter.
What if I Can't Pay the Amount I Owe?
Don't panic. Staring down a large tax bill is a scary prospect for anyone. HMRC isn’t completely inflexible; they know that people's financial situations can be complicated.
If you genuinely can’t afford to pay it all in one go, you can often negotiate a ‘Time to Pay’ arrangement. This is a formal agreement that lets you pay back what you owe in manageable monthly instalments. The key is to be upfront about your financial situation right away. Ignoring the bill won't make it disappear!
Can I Handle the Disclosure Myself?
For a very simple mistake covering a single tax year, you might feel confident enough to handle it yourself using the online portal.
However, for anything more complex—perhaps involving multiple years, offshore assets, or large sums of money—getting professional advice is a very smart move. A tax advisor can make sure your calculations are spot-on, help you present your case in the best possible light, and ensure you don’t pay a penny more in penalties than you absolutely have to.
Navigating a voluntary disclosure to HMRC can feel complex, but you don't have to do it alone. If you're ready to put your tax worries behind you and get a clear, expert-led plan in place, get in touch with Artema Ltd. Visit us at https://www.artema.co.uk for a confidential chat about your situation.