
Trying to manage your business finances without a chart of accounts is like trying to bake a cake by just chucking random ingredients into a bowl and hoping for the best. You might end up with something edible, but you’ll have no idea how you did it, and it probably won't be a masterpiece.
So, what is a chart of accounts? In simple terms, it's a neatly organised list of every single financial category your business uses. It’s the secret recipe that tracks where your money comes from and, more importantly, where it all goes. Think of it as the ultimate index for your company's financial story.
Your Guide to Financial Organisation
Let's stick with that cake analogy for a second. In a recipe, you have your ingredients list: flour, sugar, eggs, etc. The chart of accounts (COA) does the exact same thing for your money. It's the organisational backbone for your general ledger—your company's big book of every single financial transaction.
Without this system, every payment you make and every pound you earn is like a random ingredient tossed into a giant, chaotic pile. Trying to figure out what you spent on eggs versus sprinkles would be a nightmare, and understanding the big picture would be completely impossible.
Bringing Order to Financial Chaos
A well-structured COA groups all your financial activities into sensible categories, giving you instant clarity. Every transaction, from buying tea bags for the office (a very important expense) to landing a massive client payment, gets assigned to a specific account.
This process is the bedrock of good financial management and is vital for anyone running a business in the UK, from a solo dog walker to a bustling tech company. It ensures every penny is accounted for, making scary tasks like tax returns or applying for a loan infinitely less painful.
The COA is far more than just a list; it’s the framework that brings structure to your financial data. In the UK, a typical small business might have between 200-500 accounts to ensure everything is tracked properly, while larger firms could easily have over a thousand. (Don't worry, you don't need that many to start!)
The Five Core Account Types
Every chart of accounts, no matter how complicated it looks, is built on five fundamental pillars. Getting to grips with these is the first step to becoming the boss of your finances.
Here’s a quick rundown of what they are and what they actually mean.
| The Five Core Account Types at a Glance |
| :— | :— | :— |
| Account Type | What It Represents | Simple Example |
| Assets | Everything your business owns that has value. The good stuff! | Cash in the bank, your work laptop, or your office building. |
| Liabilities | Everything your business owes to others. The not-so-fun stuff. | Bank loans, credit card debt, or unpaid supplier invoices. |
| Equity | The net worth of your business. Your slice of the pie. | What's left after you subtract liabilities from assets. |
| Revenue | All the money your business earns. Ka-ching! | Sales of your products or fees for your amazing services. |
| Expenses | All the costs of running your business. The money going out. | Rent, salaries, marketing, and the ever-present utility bills. |
Understanding these five categories is the key to unlocking a clear view of your company's financial health.
As you organise your finances, it's also worth considering how your systems talk to each other. Seamlessly integrating accounting software with other crucial business tools makes everything run more smoothly.
Need a hand getting your financial books in order? Our expert bookkeeping services can help you build a solid foundation for your business. Give us a shout!
Why a Chart of Accounts Is Your Secret Weapon
Let's be honest, the term "chart of accounts" doesn't exactly scream "edge-of-your-seat excitement." It sounds like something best left to the accountants, filed away in a dusty cabinet. But here’s the thing: a well-organised chart of accounts (COA) is one of the most powerful, stress-busting tools you can have as a business owner. It’s not just for your accountant; it’s your financial secret weapon.
Think of it as the dashboard of your business. Instead of a jumbled mess of transactions, a great COA gives you a crystal-clear snapshot of your financial health. At a glance, you can see precisely where your money is coming from and exactly where it’s going. No more guesswork or vague feelings about how the month went—just the cold, hard facts.
Get a Clear Financial Picture
Running a business without a proper COA is like driving in thick fog with no headlights. You might be moving forward, but you have no real idea what’s just around the corner. By organising every single transaction into a logical place, that fog magically lifts.
This immediate clarity helps you answer crucial questions in a heartbeat:
- Profitability: Which of my services are actually making me money, and which ones are a bit of a dud?
- Spending: Is my coffee budget getting out of hand, or am I spending a fortune on software I barely use?
- Cash Flow: Do I have enough cash in the bank to pay my team and keep the lights on next month?
Suddenly, your financial data goes from being an intimidating chore to a source of genuine "aha!" moments.
Make Smarter Business Decisions
Good decisions are always built on good information. Your chart of accounts is the engine that provides this information, helping you shift from reactively putting out fires to proactively planning your next brilliant move. With all your data neatly categorised, you can budget and forecast with far greater accuracy.
A well-structured chart of accounts gives you visibility into how your firm earns and spends money, ensuring that your financial reporting stays accurate and compliant. This isn't just about record-keeping; it's about building a framework for sustainable growth and informed decision-making.
For instance, if you're thinking about applying for a business loan, lenders will want to see organised financial statements. A detailed COA means generating reports like a Profit and Loss statement or a Balance Sheet is as simple as clicking a button. It shows you're on top of your game, which builds confidence and seriously improves your chances of getting that cash.
Simplify Your Tax Obligations
For any UK business owner, keeping HMRC happy is a top priority. Tax season can feel like a frantic scramble to find receipts and make sense of a year's worth of transactions. A proper chart of accounts transforms this chaotic annual ritual into a straightforward, manageable task.
When your expenses are already categorised—separating things like 'Office Supplies', 'Travel Costs', and 'Software Subscriptions'—filling out your tax return becomes dramatically simpler. Your accountant will probably send you a thank-you card, and you'll minimise the risk of errors or missed deductions. It’s about being organised all year round, not just in a mad dash every January.
Ultimately, this simple list is your ticket to less stress, better decisions, and more control. Ready to take control of your finances? Our team can help set up the perfect chart of accounts for your business.
Decoding the Structure of Your Chart of Accounts
At first glance, a chart of accounts can look a bit like secret code, full of numbers and unfamiliar labels. But don't worry, there's a simple and elegant logic behind it all.
Think of it as a super-organised filing cabinet for your money; every number has a purpose, guiding each transaction to its correct drawer. This system isn't designed to be confusing—quite the opposite! It’s built to bring clarity and order, turning a jumble of figures into a coherent story about your business.
Once you crack the code, you'll see it’s a seriously powerful tool for organisation.
The Five Pillars of Your Financial World
Every chart of accounts, no matter how big or small the business, is built on five fundamental account types. These are the main sections of your financial library, and every single transaction will find a home under one of them.
Let's break them down in plain English:
- Assets: This is everything your business owns that has value. Think cash in the bank, the laptop you're working on, or any property you might have.
- Liabilities: This is everything your business owes to other people or businesses. This covers things like bank loans, credit card balances, or money you owe to your suppliers.
- Equity: This is the net worth of your business. It's what's left over for you, the owner, after you subtract all your liabilities from all your assets.
- Revenue (or Income): This is all the money your business earns from whatever it is you do. For a landlord, it's rent; for a consultant, it's service fees.
- Expenses: This is all the money your business spends just to keep the lights on. It covers everything from office rent and staff salaries to software subscriptions.
Getting your head around these five pillars is the first big step. The next is seeing how they slot together to help you track your performance. By clearly separating what comes in (income) from what goes out (expenses), you get a direct line of sight into your company's profitability. This is absolutely essential when you need to understand how to read a profit and loss statement.
Putting It All Together with Numbers
Now for the "secret code" part—the numbers! To keep everything tidy, each account is assigned a unique number. And it isn't random; there's a proper system to it. Most businesses use a specific range of numbers for each of the five account types.
A simple numbering system might look something like this:
- 1000s for Assets: Accounts like '1010 Current Bank Account' or '1500 Office Equipment'.
- 2000s for Liabilities: Accounts like '2010 Business Loan' or '2200 Credit Card Payable'.
- 3000s for Equity: Accounts like '3000 Owner's Capital' or '3500 Retained Earnings'.
- 4000s for Revenue: Accounts like '4000 Sales Income' or '4100 Rental Income'.
- 5000s for Expenses: Accounts like '5010 Rent', '5050 Marketing', or '5100 Office Supplies'.
This logical numbering makes it incredibly easy to find things and run reports. When all your expenses start with a '5', you can see a summary of your spending in a flash.
This structured approach isn't just a business best practice; it's a fundamental principle of good financial management. A well-organised chart of accounts is designed for clarity and can easily grow with your business, whether you're just starting out or expanding your operations.
This infographic breaks down how this structure helps create clarity, aids strategic decisions, and ensures you stay compliant.
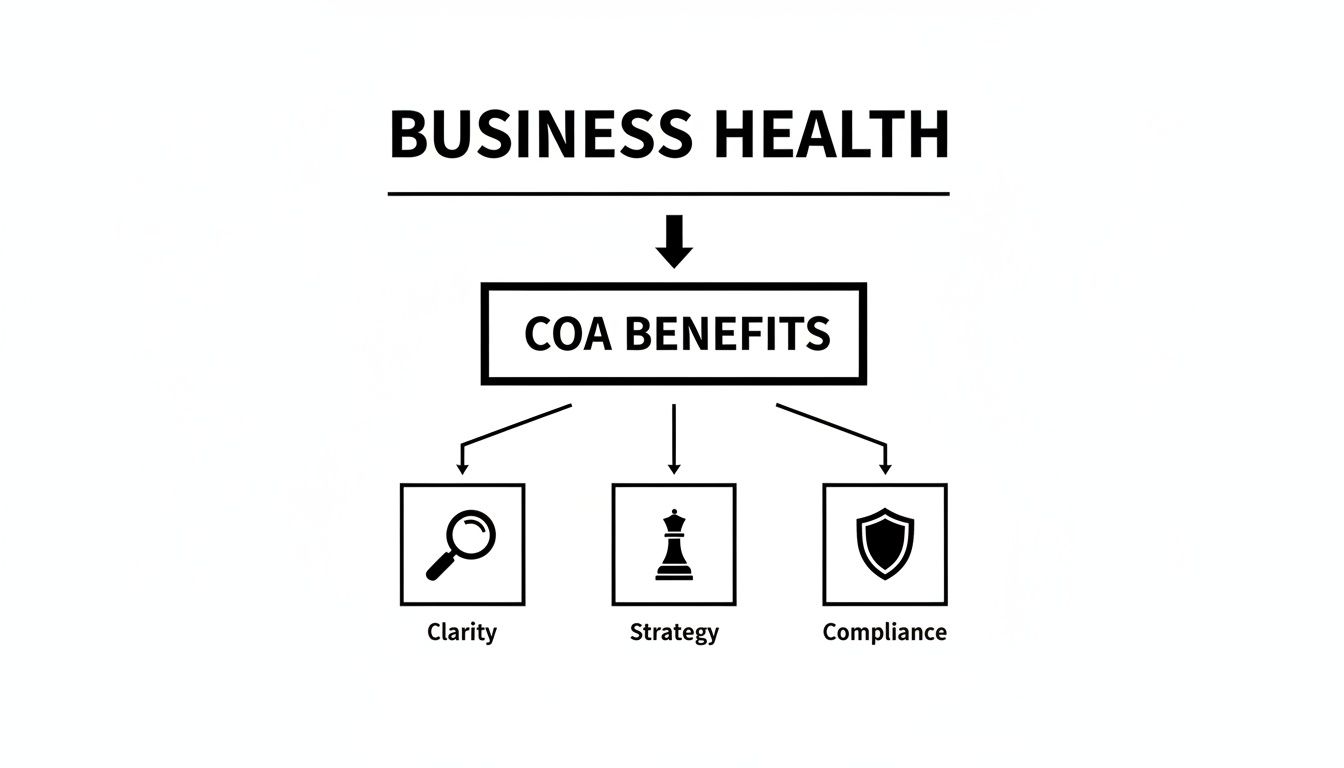
The key takeaway? A properly organised COA is central to keeping your business healthy by making your financial data transparent and, most importantly, actionable.
Right, let's roll up our sleeves and get practical. Theory is great, but now it’s time to actually build something. The good news is that modern accounting software like Xero does a lot of the heavy lifting for you. You don’t need to be a spreadsheet wizard or an accounting guru to get started.
When you first set up your Xero account, it doesn’t just give you a blank page and wish you good luck. Instead, it provides a default chart of accounts based on your business type. It’s a solid starting point, but think of it like a new suit off the rack—it does the job, but it’ll fit a lot better with a few custom alterations.
This default list is designed to be generic, covering the basics for most businesses. But your business is unique, and your financial tracking should reflect that. Tailoring your chart of accounts is the key to unlocking genuinely useful insights, not just ticking a bookkeeping box.
Why You Must Customise Your Xero Chart of Accounts
Sticking with the default COA is a bit like trying to sort your music collection into just two folders: "Music I Like" and "Music I Don't." It works on a basic level, but it’s not very helpful when you want to find something specific. You need more detail to know what’s really going on in your finances.
Customising your chart of accounts allows you to track income and expenses with a level of detail that actually matters to you. For a coffee shop, this might mean creating separate revenue accounts for "Coffee," "Cakes," and "Merch" to see what's really driving sales. For a freelance designer, it could mean creating specific expense accounts for various software subscriptions to see which ones are worth the cost.
This isn't about creating more work; it's about making your financial data work for you. The more relevant your categories are, the clearer your financial reports will be and the smarter your business decisions will become.
A Step-by-Step Guide to Customising in Xero
Ready to take control? Getting your chart of accounts just right in Xero involves three main jobs: adding, editing, and archiving accounts. Let’s break them down.
Here’s a look at the Xero dashboard where your journey begins.
From this central hub, you can easily find your chart of accounts by navigating to the advanced accounting settings.
1. Adding a New Account
You'll do this whenever you have a new income stream or a specific expense you want to track separately.
- Navigate: From your Xero dashboard, go to Accounting > Advanced, then click on Chart of accounts.
- Add Account: Hit the "Add Account" button.
- Fill in the Details: You'll need to fill in a few fields. The most important are:
- Account Type: Is it an expense, revenue, asset? Choose from the dropdown menu.
- Code: Give it a unique number that fits your numbering system (e.g., a new expense might be 5200 if your other direct costs are in the 5000s).
- Name: Give it a clear, descriptive name like "Marketing – Social Media Ads" instead of just "Marketing".
- Tax Rate: Make sure you assign the correct VAT rate.
- Save: Click save, and voilà! Your new account is ready to use.
2. Editing an Existing Account
Sometimes, Xero's default names are a bit vague. You can easily edit them to make them more meaningful for your business.
Don’t be afraid to change account names to something that makes immediate sense to you. Renaming 'General Expenses' to 'Office Snacks & Coffee' provides much clearer insight into where your money is really going (mostly on biscuits, probably).
The process is simple. Just find the account in your chart of accounts list, click on its name, change the details you need, and hit save. Just be aware that you can't change the account type if transactions have already been recorded against it.
3. Archiving an Unused Account
Over time, you might find you have accounts you no longer need. Deleting them can cause issues if they've been used in the past, so Xero lets you archive them instead. This hides them from your main list, keeping things tidy without losing any of your historical data. Think of it as putting them in the attic rather than throwing them out.
- Select the Account: Find the account you want to hide in the list.
- Click the Checkbox: Select the checkbox next to it.
- Archive: Click the "Archive" button at the top of the list. It’s that simple.
Taking these small steps transforms your Xero chart of accounts from a generic template into a powerful, personalised tool for your business. It’s the difference between having a vague idea of your finances and knowing them inside and out. For more in-depth guidance, exploring a comprehensive overview of Xero accounting can provide additional tips and tricks.
While Xero is a popular choice, it's also useful to understand how a chart of accounts operates in other systems like Sage 100, as this can offer broader insights into accounting software in general.
Common Chart of Accounts Mistakes to Avoid
So, you’ve built your chart of accounts. Fantastic! But before you put your feet up with a well-deserved cuppa, let's talk about a few common tripwires that can turn your beautifully organised list into a bit of a mess. Getting it right from the start saves you a world of accounting headaches down the line.
Think of your chart of accounts like that perfectly organised kitchen drawer. If you set it up logically, finding the spatula is a breeze. But if you just start shoving utensils in random places, you’ll never find anything when you need it most. Let's keep your financial drawers tidy.
The Goldilocks Dilemma: Not Too Vague, Not Too Detailed
One of the biggest mistakes is getting the level of detail wrong. This usually goes one of two ways, and honestly, both are pretty unhelpful.
First, there’s the ‘too vague’ approach. This is where you create a giant bucket account called "Miscellaneous Expenses" and throw everything from printer paper to client lunches into it. While simple, it tells you absolutely nothing. At the end of the year, that ‘Miscellaneous’ figure is just a big, unhelpful question mark.
On the flip side is the ‘absurdly detailed’ approach. This involves creating separate accounts for "Black pens," "Blue pens," and "Paperclips." This level of detail is exhausting to maintain and clutters up your reports, making it impossible to see the bigger picture.
The Fix: Find that ‘just right’ balance. Group similar items logically. For instance, instead of dozens of tiny stationery accounts, one category called ‘Office Supplies’ will do the job perfectly. This gives you meaningful insight without drowning you in pointless detail.
Keeping Your Naming Conventions Consistent
Imagine if half your team called an account "Sales Income," another part called it "Revenue," and a few stragglers used "Client Payments." When it's time to run a report, your income is suddenly split across three different places. It’s a recipe for confusion and bad decisions.
Inconsistent naming is a sneaky problem that can make your chart of accounts almost useless. It creates duplicate accounts and makes it impossible to get a reliable overview of your business performance.
To avoid this chaos, it’s vital to establish a clear and consistent naming system from day one.
- Be Descriptive: Use clear, unambiguous names. ‘Marketing – Social Media Ads’ is much better than just ‘Ads’.
- Document Everything: Create a simple guide that lists your account names and what they should be used for.
- Stick to the Plan: Make sure anyone who does bookkeeping for your business follows the same rules. No going rogue!
Pruning the Unused Accounts
Over time, your business will change. You might stop offering a certain service or switch software providers. When this happens, the accounts you created to track those things become obsolete. Leaving old, unused accounts in your chart of accounts is like keeping clothes you haven't worn in a decade—they just take up space and make it harder to find what you actually need.
A cluttered COA slows down data entry and increases the risk of someone accidentally posting a transaction to the wrong, defunct account. This can quietly skew your financial reports without you even realising.
The solution is simple housekeeping. Most accounting software, like Xero, lets you archive old accounts. This tucks them away from your active list without deleting the historical data. It’s the perfect way to keep your COA clean, relevant, and efficient.
Steering clear of these common blunders will ensure your chart of accounts remains a powerful tool for clarity and control. If you need a hand setting up a robust COA from scratch, our team is here to help you build a financial framework that truly works for you.
Your Chart of Accounts Questions Answered
We've covered a lot of ground on our journey through financial organisation, from what a chart of accounts actually is to the common pitfalls you'll want to avoid. But it's completely normal if you still have a few questions buzzing around.
This final section is here to tackle some of the most common queries we hear from UK business owners just like you. Let's clear up any last bits of confusion so you can move forward with total confidence.
Do I Really Need a Chart of Accounts as a Sole Trader?
Ah, the classic question! When you're a one-person show, it’s easy to think, "My business is simple, surely I don't need all this formal accounting stuff?" While you probably don't need hundreds of accounts, the answer is a resounding yes, you absolutely do!
Think of it this way: even if your finances feel straightforward, you still have to report your income and expenses accurately to HMRC. A basic chart of accounts is your best friend for separating business costs (like materials, travel, and software) from your personal spending. This doesn't just make your Self Assessment tax return a thousand times easier; it gives you a clear, honest picture of whether your business is actually profitable.
Without one, you’re just creating a chaotic shoebox full of receipts to deal with in January. A simple COA helps you stay organised, compliant, and on top of your game.
How Detailed Should My Chart of Accounts Be for a Limited Company?
For a limited company, your chart of accounts needs a bit more muscle. Unlike a sole trader, a limited company is a separate legal entity, which means its finances must be kept entirely separate from your own. This demands a greater level of detail in your bookkeeping.
Your COA needs to be robust enough to track key limited company items, such as:
- Directors' Loans: A specific account to track money you lend to the company or borrow from it.
- Corporation Tax: A liability account to set aside money for your upcoming tax bill.
- Dividends: An equity account to record profit distributions made to shareholders.
- Share Capital: An equity account showing the initial investment from shareholders.
The goal isn't to create a monstrously complex list. It's about having enough detail to produce accurate financial statements—like a Balance Sheet and a Profit & Loss statement—that meet legal requirements and give you a true view of the company’s financial health.
Can I Use the Same Chart of Accounts for My Rental Properties and My Small Business?
It’s a tempting shortcut, but it's generally a bad idea to mix them. Even though you own both, your rental property portfolio and your other small business are distinct operations with very different types of income and expenses.
Trying to cram everything into a single chart of accounts will quickly become a confusing mess. Imagine trying to figure out if your properties or your consulting business is more profitable when all the income is lumped into one "Sales" account. It's impossible.
The best practice here is to maintain two separate charts of accounts. One should be tailored for your property business (with accounts for rental income, letting agent fees, maintenance costs) and another for your other venture. This keeps your records clean, simplifies tax reporting, and gives you clear, actionable insights into how each is performing.
Is There a Standard Chart of Accounts for the UK?
While there isn't one single, government-mandated chart of accounts that every UK business must use, there are widely accepted structures based on UK accounting standards (like FRS 102 and FRS 105 for smaller companies).
Modern accounting software like Xero comes with excellent default templates already customised for UK businesses. These provide a fantastic starting point that covers most of the accounts you'll need for assets, liabilities, equity, revenue, and expenses.
This standardised approach actually has deep roots in tracking the nation's economic health. Since the mid-20th century, the COA has been central to understanding the UK's financial position. For example, by Q3 2025, the national current account deficit reached £12,100 million, a figure influenced by a services trade surplus of £37,713 million and secondary income outflows. Tracking these complex figures requires sophisticated COAs at the corporate level to separate different income and liability types, highlighting just how vital this organisational tool is. You can learn more about these national economic trends on tradingeconomics.com.
What’s the Difference Between the General Ledger and the Chart of Accounts?
This is a great question, as the two are closely related but play very different roles. They're like Batman and Robin—they work together, but they're not the same person.
Let's return to our library analogy one last time.
-
The Chart of Accounts is the library's catalogue or index. It’s the organised list of all the sections where the books can be found (e.g., "Fiction," "History," "Science"). It gives you the structure but doesn't contain the stories themselves.
-
The General Ledger is the entire collection of books. It’s the detailed, chronological record of every single transaction that has ever happened in your business, all filed neatly on the shelves defined by the chart of accounts.
In short, the chart of accounts provides the framework, and the general ledger contains the details. You can't have an organised general ledger without a logical chart of accounts to guide it.
Feeling more confident about what a chart of accounts is and how to make it work for you? Getting this financial foundation right is one of the smartest moves you can make for your business.
If you’d rather have an expert handle the setup and management, we'd love to help. Artema Ltd provides bespoke accounting and bookkeeping services that give you clarity and peace of mind. Visit us at https://www.artema.co.uk to learn how we can help your business thrive!