
Ever stared at your bank balance and felt that little jolt of surprise? "Hang on, I thought there was more in there…" It happens to the best of us. Well, accounts reconciliation is basically the superhero power that stops those mini heart attacks for good.
In simple terms, it’s checking that the money you think you have in your business records actually matches the money in your bank account. Think of it like comparing your shopping list to what’s in your trolley before you hit the checkout. It’s a quick, common-sense check to make sure everything adds up and there are no sneaky, unwanted items (or fees!) hiding in there.
So, What Is Accounts Reconciliation, Really?
Accounts reconciliation is the official-sounding name for a very simple idea: comparing two sets of financial records to spot any differences. Most of the time, this means you're lining up your company's own books (like your bookkeeping software) against an outside source, like your bank or credit card statement. The mission? To make sure every penny leaving and entering your business is accounted for in both places.
It's All in the Details (and the Detective Work)
Let's say your business records are proudly showing a balance of £5,000, but your bank statement is giving you the silent treatment at £4,800. Reconciliation is the detective work you do to find that missing £200. Was it a bank fee you forgot about? A customer payment that’s still floating in the ether? Or, in a less fun plot twist, a mistake or a dodgy charge?
This simple process answers a few critical questions for any business owner:
- Is the cash in my books the real deal?
- Have all my customers actually paid me?
- Are there any surprise bank charges lurking in the shadows?
- Did I pay all my suppliers what I thought I did?
By regularly reconciling your accounts, you’re not just tidying up your numbers. You’re painting an accurate, reliable picture of your financial health. It’s the secret ingredient for making brilliant business decisions.
More Than Just Your Bank Balance
While checking your bank account is the most common type, this handy habit can be used all over your finances. You can reconcile supplier statements, customer invoices, and even the office petty cash tin (to find out who keeps buying all the fancy biscuits). Each check makes sure a different part of your financial engine is humming along nicely.
For a deeper dive into specific types, you might also find it useful to learn about What Is Payment Reconciliation.
Ultimately, reconciliation transforms bookkeeping from a chore into a superpower. It gives you the confidence that the numbers you rely on are real and accurate. Ready to see why this simple check is so vital? Let's get into it.
Why Reconciliation Is Your Financial Superpower
Okay, so we know what it is, but why should you really care? Let’s be honest: doing a regular reconciliation is less of a boring chore and more like unlocking a financial superpower for your business. It turns your bookkeeping from a dusty old history book into a crystal ball for making smart moves.
Without it, you’re basically driving your business with a foggy windscreen and hoping for the best. With it, you get crystal-clear vision to spot trouble long before it grows into a monster. It’s your first line of defence against all sorts of financial gremlins, protecting your hard-earned cash and letting you sleep at night.
Catching Costly Errors and Sneaky Charges
Let's face it, banks make mistakes. Suppliers can accidentally send a duplicate invoice. And sometimes, mysterious subscription fees pop up like weeds. Reconciliation is your chance to play detective and catch these little gremlins before they start nibbling away at your bank account.
Think about a café owner we worked with. She diligently reconciled her accounts every month. One day, she spotted a supplier invoice that was £500 higher than usual. A quick phone call revealed they’d charged her for an order that never showed up. That simple check saved her an entire week’s profits. Whoops!
Reconciliation isn't just about ticking boxes; it's about actively protecting your cash flow. It empowers you to question every transaction and make sure your money is only going where you want it to.
Making Smarter Business Decisions
How can you confidently decide whether to hire a new team member or launch that awesome marketing campaign if you’re not 100% sure about your numbers? Reconciled accounts provide a rock-solid foundation for all your big plans.
When your books are accurate, you can:
- Secure Funding: Lenders and investors want to see clean, trustworthy financials. It’s a deal-breaker if you’re looking for a loan or investment.
- Breeze Through Tax Season: Imagine having all your numbers perfectly organised when tax time rolls around. No more late-night scrambles hunting for missing receipts!
- Master Your Cash Flow: You’ll get a true picture of your cash situation, helping you see bumps in the road ahead and avoid nasty surprises.
Ultimately, turning reconciliation into a regular habit gives you control. It takes the guesswork out of your finances and gives you the confidence to lead your business with clarity.
Feeling ready to unlock this superpower but not sure where to start? Don't sweat it. Our friendly team at Artema is here to help you get organised. Reach out today for a friendly, no-obligation chat about your books!
The Main Types Of Reconciliation You'll Actually Use
The phrase "accounts reconciliation" sounds a bit grand and stuffy, doesn't it? The good news is, you don't have to wrestle the whole beast at once. In reality, it boils down to a few key checks that, once you get the hang of them, become easy-peasy habits.
Think of it like sorting your laundry. You don't just chuck everything in one big pile; you separate it into whites, darks, and "I'm not sure what colour this is anymore." We'll do the same with reconciliation, breaking it down into logical chunks that make the whole thing far less scary.
A Quick Peek at the Different Flavours
Before we dive in, here’s a quick look at the main types of reconciliation. Each one does a different job, but they all work together to give you a complete picture of your financial health.
| Reconciliation Type | What You Compare | Why It's a Lifesaver |
|---|---|---|
| Bank Reconciliation | Your business's cash records against your actual bank statement. | Confirms your cash is all there, spots bank errors, and tracks down runaway payments or fees. |
| Customer Reconciliation | Your sales invoices against the payments you've received from customers. | Makes sure you've been paid for all your awesome work and helps you chase any late payers. |
| Supplier Reconciliation | Your supplier invoices against the payments you've made to them. | Stops you from paying twice by mistake, helps manage your bills, and keeps your suppliers happy. |
Now, let’s see what each of these actually involves.
Bank Reconciliation
This is the big one, the headliner, the one everyone thinks of first. Bank reconciliation is simply comparing your internal business records (your cash book or accounting software) with your official bank statement. The goal is to make sure the cash you think you have is the cash you actually have.
This check is brilliant for spotting things like:
- Uncashed cheques that are still out there in the wild.
- Bank fees or interest payments you forgot to record.
- Customer payments that have bounced or haven't cleared yet.
Customer and Supplier Reconciliation
These two are two sides of the same coin, and they are absolutely vital for keeping your cash flowing in the right direction.
Customer Reconciliation involves checking your sales invoices against the payments you've received from your clients. It’s how you answer that crucial question: "Has everyone who owes me money actually paid up?" This helps you gently nudge any overdue payments.
On the flip side, Supplier Reconciliation is all about making sure you've paid your own bills correctly. You compare the invoices from your suppliers with the payments you’ve sent out. This stops you from accidentally paying for something twice (it happens!) and helps you maintain great relationships.
Using modern tools can make this a whole lot easier. For managing supplier payments, exploring solutions for Accounts Payable Automation can save you from a world of headaches.
By splitting your reconciliation tasks into these three areas, the job becomes much more manageable. Smart tools can simplify it even further, and many find that learning about Xero accounting software is a great first step towards automating these essential checks.
A Simple Step-By-Step Guide to Reconciliation
Alright, let’s get down to business. The good news is that the actual process isn't as scary as it sounds. You don’t need a maths degree or a secret decoder ring to get it right.
Think of it like building flat-pack furniture. It looks a bit wild in the box, but if you just follow the instructions step-by-step, you’ll have a sturdy bookshelf in no time. We’ve broken it down into four simple stages to get you started.
Step 1: Gather Your Documents
First things first, get all your paperwork together. This is like prepping your ingredients before you start cooking. For the period you're looking at (let's say last month), you'll need two things:
- Your Internal Records: This is everything from your business’s own records—sales invoices, receipts, and reports from your accounting software.
- Your External Records: This is mainly your official bank statement, but it could also be your credit card statement.
Having it all in one place before you start will save you from a frantic treasure hunt for a missing receipt later on.
Step 2: Play a Game of "Match the Transactions"
Now for the fun part! Go through both sets of documents and match up the transactions. It’s like a game of financial ‘snap!’ – a £50 payment to a supplier in your books should have a matching £50 withdrawal on your bank statement.
As you find a match, tick it off on both lists. This is surprisingly satisfying and helps you clearly see what’s left over to investigate. Which leads us to…
This is where modern accounting software becomes your best friend. Instead of manually ticking off hundreds of transactions, tools like Xero can automatically match most of them for you, turning hours of work into a few clicks.
This screenshot from Xero's website shows how bank feeds can bring transactions directly into your accounting software.
Automated bank feeds pull in your transaction data, making it much easier to see what needs to be matched and reconciled.
Step 3: Investigate the Mysteries
Once you’ve paired everything up, you’ll probably have a few rogue items left over. Don’t panic! This is totally normal. Now you get to put on your detective hat and figure out what’s going on.
The usual suspects for these mismatches are:
- Timing Differences: A payment you made on the 30th might not have left your bank account until the 2nd of the next month.
- Bank Charges: Those sneaky monthly fees or interest that you forgot to log.
- Forgotten Transactions: That business lunch you paid for on your card but forgot to get a receipt for.
Step 4: Make It Right
The final step is to fix everything up. Once you know why there’s a difference, you just need to update your own records to reflect reality. This is called making an adjusting entry.
For instance, if you found a £10 bank fee on your statement that wasn't in your books, you'd add it as an expense. Once all your adjustments are made, your records and your bank statement should finally be holding hands and singing in harmony. And that’s it—you’re reconciled!
Feeling like this is still a bit much? For expert help getting your books in order, check out our professional bookkeeping services. We love doing the detective work!
How to Beat Common Reconciliation Headaches
Even with the best plan, accounts reconciliation can sometimes feel like trying to solve a puzzle where the pieces just don't fit. You sit down, ready to go, only to find the numbers are being stubborn. It’s a common frustration, but don’t throw your calculator at the wall just yet!
Most reconciliation headaches come from a handful of usual suspects. Once you know what to look for, they become much less of a big deal.
This simple diagram breaks down the core reconciliation process, from gathering your documents to making the final tweaks.
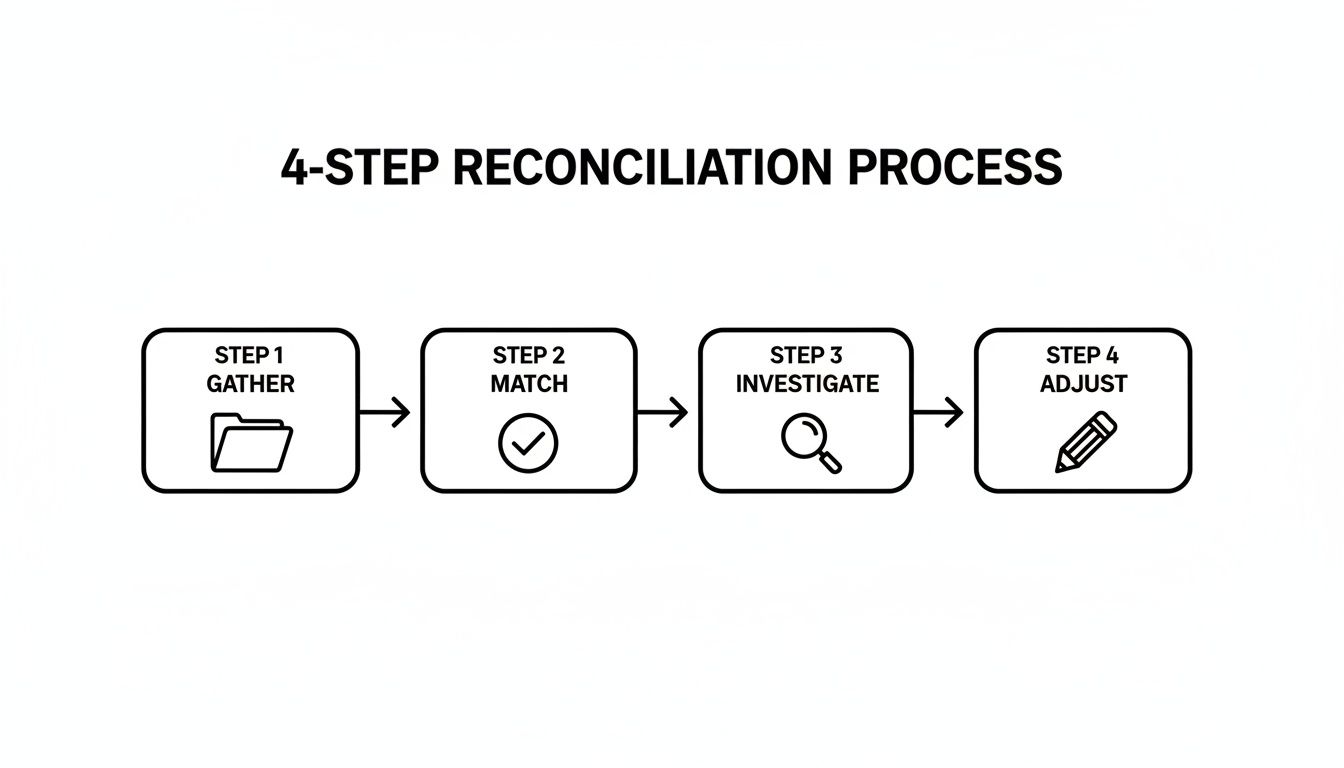
Following these four key stages—Gather, Match, Investigate, and Adjust—gives you a clear roadmap for tackling any weird numbers you come across.
The Mystery of the Missing Transaction
One of the most common culprits is a simple timing difference. Maybe you’ve recorded a payment from a customer, but it hasn’t actually landed in your bank account yet. Or you paid a supplier on the 31st, but they haven’t cashed it, so it’s missing from your bank statement.
These aren't errors, just a natural lag in the system. The solution is to make a note of these "outstanding" items. They should pop up on your next statement, and your books will match up perfectly then.
Another classic is a genuinely missed transaction. That coffee you bought during a meeting or a small bank fee that slipped your mind. It’s easy to forget to log these little things.
The fix is simple: when you spot a transaction on your bank statement that’s missing from your books, you just need to add it as an adjusting entry. Problem solved.
Pesky Human Errors (Oops!)
We’ve all been there. A busy afternoon, a slip of the fingers, and suddenly you’ve entered £15.20 as £12.50. These little typos are incredibly common but can throw your entire reconciliation off. A single switched number can send you on a wild goose chase for hours.
The best way to handle this is to double-check your entries. If your balances are off by an amount that looks familiar or is divisible by nine (a classic sign of switched digits), it’s worth checking your recent entries for typos.
Feeling like you’re spending more time being a financial detective than running your business? If these headaches are becoming a regular migraine, it might be time to call for backup. Get in touch with the Artema team, and let us solve the puzzle for you.
When to Call for a Reconciliation Lifeline
Doing your own accounts reconciliation is a bit like DIY. When it works out, it feels amazing. But there’s often a moment when you’re staring at a mess, ankle-deep in confusing figures, and realise that calling in a pro from the start might have been a better idea.
While tackling your own books is empowering, knowing when to ask for help is a brilliant business skill. It isn't admitting defeat; it's making a smart decision to protect your time, your sanity, and your business's financial health.
Signs You Need an Expert on Speed Dial
Even if you're a reconciliation pro, some situations just scream for an expert. Think of it as getting help before a small leak turns into a full-blown flood.
Here are a few tell-tale signs that it's time to make the call:
- The Numbers Just Won’t Balance: Do you always end up with a mysterious, unexplained difference that you just can't track down? An expert has a trained eye for spotting the subtle things you might be missing.
- You're Always Playing Catch-Up: Is “reconcile accounts” a permanent resident at the bottom of your to-do list? Falling months behind isn't just annoying—it can hide serious cash flow problems until it's too late.
- Your Business Is Growing Fast: Rapid growth is awesome! But it also means more transactions, more complexity, and more room for error. The simple system that worked when you started will quickly get overwhelmed.
- Things Are Getting Complicated: Are you now dealing with foreign currencies, multiple payment systems (like Stripe and PayPal), or tricky supplier contracts? Each of these adds another layer of difficulty that an expert handles every day.
Handing over your accounts isn’t giving up. It’s a strategic move that frees you up to do what you do best—running and growing your business.
At Artema, we genuinely enjoy taking that weight off business owners' shoulders. We can step in to get everything back on track, untangle any existing messes, and set you up with a smooth, simple process for the future.
If you’re tired of battling spreadsheets and just want it done right, our friendly team is ready to help. Discover how our online bookkeeping services can give you back your time and complete financial peace of mind. Let’s have a chat.
Frequently Asked Questions About Reconciliation
We’ve covered a lot, but it’s totally normal to still have a few questions buzzing around. Let's tackle some of the most common things business owners ask when it comes to accounts reconciliation.
How Often Should I Reconcile My Accounts?
Great question! The honest answer is: it depends on your business. For most small businesses, doing it monthly is the sweet spot. This lines up perfectly with your bank statements and creates a nice, regular rhythm for checking in on your financial health.
However, if your business has a high number of daily transactions—like a busy café or an e-commerce shop—you might find weekly works better. Doing it more often helps you catch any issues much faster and keeps your cash flow picture super clear. The real key is consistency; pick a schedule that works for you and stick to it.
Can’t My Software Just Do It All for Me?
Modern accounting software like Xero is an absolute game-changer. It automates a huge chunk of the work by pulling in bank transactions and suggesting matches, which saves a massive amount of time. But it’s not quite a "set it and forget it" magic button.
Think of your accounting software as your super-smart assistant, not your replacement. It does the heavy lifting, but you still need to be the boss who gives the final review and says, "Yep, that looks right." Your human brain is crucial for spotting anything that looks a bit odd.
What’s The Biggest Mistake to Avoid?
The single biggest mistake we see is letting small, unexplained differences slide. It's so tempting to see a tiny discrepancy of a few pounds and think, "Ah, it's not worth the hassle." But these little mysteries have a nasty habit of adding up, and they can often hide much bigger problems.
Ignoring them is like ignoring a tiny rattle in your car. It might be nothing, or it could be the first sign that something major is about to go wrong. Always investigate every single difference, no matter how small. That discipline is what separates financially healthy businesses from those that run into nasty surprises.
Still feeling a bit lost in the numbers? The friendly experts at Artema Ltd are here to bring clarity and calm to your bookkeeping. We can help you set up a smooth process or take it completely off your hands. Visit us at https://www.artema.co.uk to learn more.