
Welcome to the world of running your own limited company! If you’ve heard the term 'Director’s Loan Account' (or DLA) floating around and thought it sounded horribly complicated, you're not alone. The good news is, it's much simpler than it seems and is a super useful tool for managing your business finances.
Your Director's Loan Account Explained Without The Jargon
So, what exactly is a Director's Loan Account? The easiest way to think of it is as a running tab between you and your company. It’s a record that tracks any money moving between your personal funds and the business's bank account that isn't a salary, dividend, or an expense reimbursement.
Sometimes you’ll lend money to the business, and other times you might borrow from it. It's a two-way street that offers brilliant flexibility when you know how to manage it correctly.
The Company Piggy Bank Analogy
Let’s imagine your limited company has a piggy bank. This isn't for saving up for a rainy day; this is your DLA.
- When you lend money to the company: Your business is a bit short on cash, so you pay a supplier invoice from your personal bank account. This is like putting your own money into the company piggy bank. The company now owes you, and your DLA is 'in credit'.
- When you borrow money from the company: You accidentally use the company debit card to pay for your weekly shop. Whoops! This is like taking an IOU from the piggy bank. You now owe the company money, and your DLA is 'overdrawn'.
This simple concept is the foundation of the DLA. It's just a record to keep things transparent, showing who owes what to whom at any given time.
Why Does It Matter So Much?
Keeping this record straight is absolutely vital because HMRC has specific rules about these loans. The DLA is a brilliant tool for UK company owners, allowing you to borrow from your company without it immediately being treated as salary or dividends.
While there's no legal limit on borrowing, taking out more than £10,000 triggers a 'benefit in kind' tax, which needs to be reported on your self-assessment tax return. It’s a detail that’s easy to miss but important to get right.
And it’s not just about taking money out. Understanding your DLA is central to figuring out the most tax-efficient ways to pay yourself. You can explore this more in our guide on how to pay yourself from a limited company.
To help you keep track, here's a quick reference guide to what your DLA status means.
Your Director's Loan Account At a Glance
| DLA Status | What It Means in Simple Terms | Your Next Step |
|---|---|---|
| DLA in Credit | The company owes you money. You've lent it your personal funds. | You can withdraw this money from the business tax-free, as it's just a repayment. |
| DLA Overdrawn | You owe the company money. You've borrowed from the business. | You need to repay the loan within a specific timeframe to avoid tax charges. |
Ultimately, managing your DLA properly is a cornerstone of good financial hygiene for any company director.
The Director’s Loan Account isn’t something to be scared of. Think of it as a flexible friend that just needs a bit of attention to stay on the right side of HMRC. Get it right, and it’s a huge asset; get it wrong, and it can lead to unnecessary tax headaches.
If you're ever unsure about where your account stands or how a transaction might affect it, don't guess. Getting professional advice can save you a huge amount of stress and money down the line.
Ready to get your finances in order? Contact the team at Artema today, and let’s make sure your DLA is working for you, not against you.
The Overdrawn DLA: What HMRC Wants You To Know
So, you’ve dipped into the company piggy bank. It happens! When you borrow money from your business, you create what’s known as an ‘overdrawn’ Director's Loan Account. While this flexibility is one of the great perks of being a company director, HMRC has a few ground rules to ensure it isn’t used as a permanent, tax-free cash machine.
This is where we need to pay close attention, but don’t worry, we'll keep it simple. Think of it like this: your company has kindly lent you some cash, and HMRC just wants to make sure you have a plan to pay it back in a reasonable timeframe.
The Not-So-Scary Section 455 Tax
Let’s introduce you to the infamous Section 455 tax, or S455 for short. The name might sound like something out of a spy film, but its purpose is actually quite straightforward. It’s essentially a temporary charge from HMRC for leaving your 'IOU' to the company unpaid for too long.
It’s not a permanent tax. It's more of a hefty deposit that HMRC holds onto until the loan is cleared. The whole idea is to strongly encourage directors to settle their overdrawn loan accounts promptly.
The key deadline to remember is nine months and one day after your company’s financial year-end. If your loan is still outstanding after this date, your company must pay S455 tax on the balance. And the rate is significant—it’s currently 33.75%, which conveniently mirrors the higher rate of dividend tax. That’s a substantial chunk of cash for your business to lend to the taxman!
The good news? This tax is refundable. Once the loan is eventually repaid, your company can get the S455 tax back from HMRC. However, the process isn't instant, which can put a real strain on your company's cash flow. You can learn more in our detailed guide on reclaiming S455 tax.
When Your Loan Becomes a Benefit in Kind
There’s another important number HMRC wants you to keep in mind: £10,000. If your director's loan goes over this amount at any point during the tax year, it trips a wire and creates a 'benefit in kind'.
A benefit in kind is any non-cash perk you receive from your company, and HMRC treats it as part of your taxable income. In this case, the 'perk' is getting an interest-free loan from your business, which is pretty nice of them.
Loans exceeding £10,000 automatically qualify as benefits in kind. This means you’ll owe personal tax on the benefit, which has to be declared on your Self Assessment tax return. On top of that, the company will have to pay Class 1A National Insurance on the same amount. It's a double whammy!
To avoid this, you can either keep the loan below the £10,000 threshold or have the company charge you interest at HMRC’s official rate.
Here’s a quick summary of the key triggers to watch out for.
Key Tax Triggers for Overdrawn Director's Loans
This table breaks down the main tax implications when your DLA becomes overdrawn.
| Trigger Event | Tax Implication | Applicable Rate or Amount | Crucial Deadline to Know |
|---|---|---|---|
| Loan over £10,000 | Creates a 'benefit in kind' for the director. | Taxed at your personal rate; company pays Class 1A NI. | Must be reported on your Self Assessment tax return. |
| Loan unpaid after year-end | Company must pay S455 tax. | 33.75% of the outstanding loan balance. | Nine months and one day after the company's year-end. |
Our goal isn't to scare you away from using your DLA. It's an incredibly useful tool! We just want to make you aware of the rules so you can borrow wisely and stay on the right side of HMRC.
Feeling a bit overwhelmed by the numbers and deadlines? You’re not alone. Managing a Director's Loan Account correctly is one of the most common challenges business owners face. If you want peace of mind, get in touch with Artema today for a friendly chat about how we can help.
When Your Company Owes You Money
So far, we've focused on what happens when you borrow from your company. But it’s not always a one-way street. Often, especially in the early days, you’ll be the one lending it money.
Think about it. Maybe you paid for a new laptop on your personal credit card, covered start-up legal fees out of your own pocket, or just popped some cash into the business account to tide it over before a big client paid. Sound familiar? All these actions put your director's loan account 'in credit'.
The Good Side of the DLA
When your DLA is in credit, it simply means the company owes you money. This is definitely the better side of the DLA to be on! It’s your business’s way of saying, "Thanks for the help, IOU." And the best part? Taking this money back is completely tax-free.
That’s right. It was your own personal, post-tax money in the first place. You’re not drawing a salary or taking a dividend; you’re simply being repaid a loan you made. This makes using your own funds to support the business a wonderfully simple and tax-efficient way to manage cash flow.
Common scenarios that put your DLA in credit include:
- Initial Start-Up Costs: Paying for things like website design, incorporation fees, or the first batch of stock from your own savings.
- Covering Expenses: Using your personal card for business travel or materials when the company card isn't handy.
- Direct Cash Injection: Transferring a lump sum into the business bank account to cover wages or a large purchase.
Earning Interest on Your Loan
Here’s an interesting little twist. You can choose to charge your company interest on the money it owes you. This creates a personal income stream for you, paid directly from the business, and it's a perfectly legitimate way to get more money out of your company.
Of course, there are a few rules. The interest you receive is taxable personal income, so you’ll need to declare it on your Self Assessment tax return.
From the company's perspective, the interest it pays you is typically an allowable business expense. This means it can be deducted from the company's profits, which in turn reduces its Corporation Tax bill. It’s a potential win-win.
This really highlights the DLA's value as a flexible financial tool when you're the lender. It's not just an accounting formality; it's a practical way to fund your business's growth and manage your own finances at the same time.
Managing all this might sound complicated, but it doesn't have to be. Keeping clear, accurate records is the key to making sure everything is above board and you’re making the most of the situation.
If you know you've personally funded your business and want to make sure you're getting your money back correctly and tax-efficiently, get in touch with the Artema team. We'll help you make sense of it all.
How to Repay Your Director's Loan Stress-Free
So, you’ve borrowed from the company and now the nine-month repayment deadline is creeping up on you. Don’t panic! Clearing your overdrawn Director's Loan Account (DLA) is usually straightforward, and you have a few good options to get it sorted without any unnecessary drama.
The best method really depends on your personal cash flow and the financial health of the business. Let's walk through the most common ways to settle up and keep everything above board with HMRC.
The Straightforward Cash Repayment
The simplest and cleanest way to clear your director's loan is to pay it back with cash. It’s exactly what it sounds like: you transfer the money from your personal bank account straight back into the company’s account. Job done.
This approach leaves a crystal-clear audit trail for your records. It’s the best option if you have the funds available, as it neatly closes the loop without any complicated accounting footwork.
Paying it Off with a Dividend
What if you don’t have the cash on hand to make a direct repayment? A very common and effective strategy is to declare a dividend. Instead of the company paying the cash out to you, it uses the value of that dividend to clear your loan balance on paper.
Of course, this only works if your company has enough distributable profits to legally declare the dividend in the first place. You can’t just pluck a number out of thin air! Your accountant can prepare the necessary board minutes and dividend voucher, and the dividend amount is then credited to your DLA, reducing or clearing what you owe.
The decision tree below gives you a simple way to think about how money you've already put into the business can be returned to you.
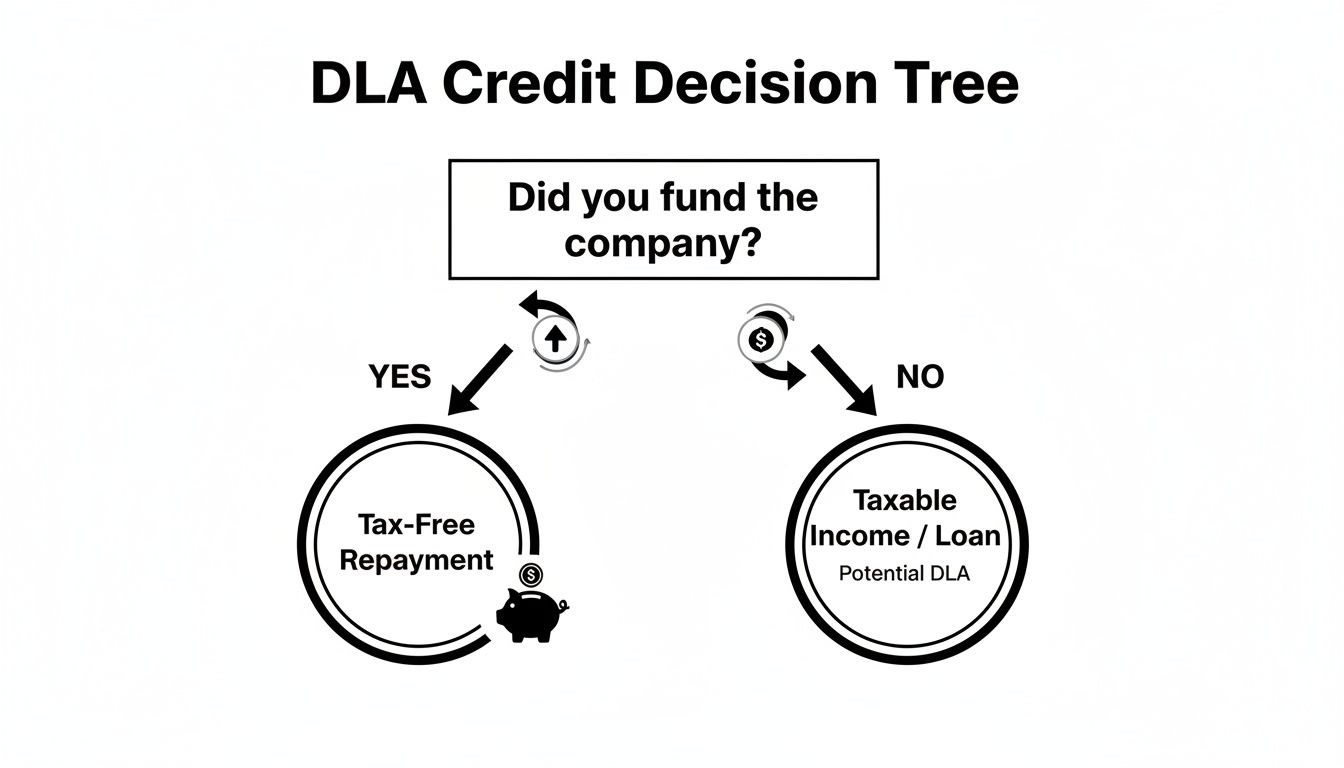
This illustrates a core idea: if you've previously funded the company with your own money, taking it back is just a tax-free repayment of your own capital.
Using Your Salary or a Bonus
Another route is to credit a salary or a bonus to your DLA. Much like the dividend method, the company owes you money (your net salary), but instead of transferring it to you, it uses that amount to pay down your loan.
This method does come with strings attached, however. The salary or bonus is subject to PAYE tax and National Insurance contributions for both you and the company, which can make it a more expensive option than a dividend. It’s a useful tool in certain situations, but it’s often less tax-efficient.
A Serious Warning About 'Bed and Breakfasting'
Now for a friendly but firm warning. Some directors think they can outsmart the system by repaying their loan just before the nine-month deadline, only to borrow the same amount again a few days later. This little trick is known as ‘bed and breakfasting’, and HMRC is completely wise to it.
Tax rules were specifically tightened to clamp down on this. If you repay a loan of over £5,000 and then borrow a similar amount again within 30 days, HMRC will treat it as if the original loan was never repaid. The result? That hefty Section 455 tax charge will still apply.
The lesson here is simple: repay your loan properly, with the genuine intention of clearing the debt. Trying to play games with deadlines will almost certainly end in a painful tax bill.
Need help figuring out the best repayment strategy for your situation? Speak to the team at Artema, and we’ll guide you through the process stress-free.
Keeping Track of Your DLA in Xero
Leaving your director's loan account until your accountant flags it at year-end is a bit like ignoring that funny noise your car's been making. Sooner or later, it’s going to lead to a surprise bill that makes you wince. The key to stress-free DLA management is much simpler: real-time bookkeeping.
Here at Artema, we're big fans of making life easier. So, we'll walk you through just how simple this can be using Xero, our accounting software of choice. A few minutes of setup now will save you hours of headaches down the line.
This Xero dashboard gives you a fantastic at-a-glance view of your company's finances. With a properly set up DLA, you can easily keep an eye on your loan balance right here, too.
Setting Up Your DLA in the Chart of Accounts
First things first, your DLA needs a proper home in your accounts. That means creating a dedicated account for it in Xero's Chart of Accounts.
Think of the Chart of Accounts as your business’s financial filing cabinet. By creating a specific drawer labelled "Director's Loan Account," you're making sure every single related transaction gets filed in the right place, every time.
Here’s a quick step-by-step guide:
- Head over to Accounting and select Chart of Accounts.
- Click Add Account.
- Set the Account Type to 'Current Liability'. A positive balance means the company owes you money, which is a liability on its books.
- Give it a unique Code (something like 835) and a clear Name, such as 'Director Loan – [Your Name]'.
- This next part is crucial: tick the box for 'Enable payments to this account'. This is the magic button that lets you allocate transactions to your DLA with ease.
- Click Save. That's it! Your DLA is now ready for action.
Recording Transactions The Right Way
With your DLA all set up, you can now start tracking money moving in and out with pinpoint accuracy. After all, good bookkeeping is really just about telling the story of every penny.
A well-managed DLA in Xero gives you a clear, instant picture of where you stand. No more guesswork, no more year-end panic—just total clarity on who owes what.
Let's look at two common real-world scenarios and how you'd handle them.
Scenario 1: You Buy a Personal Item on the Company Card
You’re at the supermarket and accidentally pay for your weekly shop with the company debit card. Oops! It happens to the best of us.
Here’s how to fix it in Xero when you’re doing your bank reconciliation:
- When the transaction pops up in your bank feed, find that specific payment.
- Instead of coding it to a business expense like 'General Expenses', you’ll allocate it directly to your new 'Director Loan' account.
- This instantly updates your DLA balance, clearly showing that you now owe that money back to the company. Simple.
Scenario 2: You Pay for a Business Expense Personally
You need to buy some urgent supplies for a project, but you've left the company card back at the office. No problem—you pay with your own money.
Here's how to record it so the company can pay you back:
- Go to Bills to Pay and create a New Bill.
- Make the bill out from yourself (as the supplier) for the exact amount you spent.
- Allocate the bill to the right expense category, like 'Stationery' or 'Materials'.
- When you 'approve' the bill, instead of scheduling a payment, you can mark it as paid from your 'Director Loan' account. This increases the amount the company owes you.
By keeping your records up to date like this, you'll never have to second-guess your DLA balance again. While we've focused on Xero here, similar principles apply if you use FreeAgent or other accounting software, which also offer ways to streamline your financial tracking.
Feeling like you could use a hand getting your books in order? Get in touch with the Artema team, and we’ll make sure your Xero is set up for success from day one.
Common DLA Mistakes and How to Avoid Them
We all make mistakes. But when it comes to your director’s loan account, a few common slip-ups can be particularly costly, leading to surprise tax bills and a whole lot of unnecessary stress. Think of us as the friend who points out the banana peel on the pavement before you take a tumble.
Managing your DLA really just comes down to being mindful. By understanding where others often trip up, you can easily sidestep the same issues and keep your company's finances in good health.
Losing Track of the Balance
This is the classic blunder. It's so easy to do. You use the company card for a personal item here, forget to log a mileage claim there, and before you know it, your overdrawn loan has quietly crept over the £10,000 threshold.
The moment you cross this line, HMRC considers the loan a 'benefit in kind'. This means a personal tax bill for you and a Class 1A National Insurance bill for the company. It’s a completely avoidable expense that usually comes down to not keeping a close eye on the running total. Your best defence? Regular, consistent bookkeeping.
It's also worth noting the interest rate on these benefits isn't fixed. Historically, HMRC's official rates have moved from a high of 7.79% in 1995/96 down to 2.25% in recent years, and it's set to rise again to 3.75% from April 2025. If you're curious, you can explore the trends in director's loan account rates to see why HMRC is paying closer attention.
Missing the S455 Repayment Deadline
We’ve talked about the Section 455 tax already, and for good reason. Missing the repayment deadline—which is nine months and one day after your company’s year-end—is a very expensive error. If you don't clear the loan in time, the company gets stung with a tax charge of 33.75% on whatever is left outstanding.
Imagine your DLA is overdrawn by £20,000. Forgetting to pay it back on time would land your company with a £6,750 tax bill. While you can reclaim this from HMRC once the loan is finally cleared, it can put a serious dent in your cash flow in the meantime.
A simple calendar reminder for your year-end and another for nine months later is a surprisingly effective way to dodge this bullet.
Falling for the 'Bed and Breakfasting' Trap
This is a tactic that HMRC has completely shut down, so don't be tempted. "Bed and breakfasting" refers to repaying a loan just before the deadline only to take the same amount out again shortly afterwards. The sole purpose is to avoid the S455 tax charge.
The rules are now crystal clear on this. If you repay a loan of more than £5,000 and then take out a similar sum within 30 days, HMRC will treat it as if the repayment never happened. The S455 charge will still apply. Genuine repayment is the only way forward here.
Keeping Messy Records
Finally, we get to the root of most DLA evil: poor record-keeping. When personal and business expenses get mixed up without being properly allocated, you create an accounting nightmare. It becomes impossible to know the true balance of your DLA, which is what leads to all the other mistakes we've covered.
Use your accounting software diligently. Every time money moves between you and the company, log it straight away. It takes seconds but will save you hours of forensic accounting and potential penalties down the line.
Navigating these pitfalls might seem a bit much, but it doesn't have to be. If you're ever feeling unsure about your DLA, just get in touch with the Artema team. We'll help you keep your account clean, compliant, and completely stress-free.
Frequently Asked Questions About Director's Loans
Still have a few questions buzzing around? You're not alone. When you’re getting your head around what a director's loan account is, a few common queries always pop up. Here are some quick, clear answers to the ones we hear most often.
Can I Have a Director's Loan Account as a Sole Trader?
Sorry, but that’s a no! Director's Loan Accounts are a feature specifically for limited companies. As a sole trader, you and your business are legally the same entity.
Any money you take out of the business is simply logged as 'drawings', not a loan. This means all the rules we’ve just gone through, like the dreaded Section 455 tax, don't apply to you. It's a much simpler setup, but it doesn't offer the same flexibility as a DLA.
What Happens to the Section 455 Tax if I Repay the Loan Late?
This is the silver lining to the Section 455 cloud—the tax is refundable! Once the director’s loan is fully repaid, the company can claim back every penny of the S455 tax it paid over to HMRC.
But there's a catch. HMRC won't process the refund until nine months and one day after the end of the accounting period in which you repaid the loan. This means your company’s cash can be tied up for a considerable amount of time, which is why it's always best to repay on time if you possibly can.
Can My Spouse Get a Loan From My Company?
Yes, they can, but you need to tread carefully. The tax rules were written to cover this exact scenario. Loans to ‘participators’ (that’s a technical term for shareholders) or their ‘associates’ (like a spouse) are caught by the very same Section 455 rules.
So, if your spouse borrows money and doesn't pay it back within the nine-month deadline, the company will still face that hefty 33.75% tax charge. These rules stop directors from simply sidestepping their obligations by getting a family member to take the loan instead. It's a clever bit of tax law designed to keep things fair.
Managing a director's loan account can feel like a juggling act, but you don't have to do it alone. The team at Artema is here to provide clear, friendly advice to keep your finances in perfect order.
Ready for some peace of mind? Visit us at https://www.artema.co.uk to see how we can help.