
So, what is financial compliance all about? In a nutshell, it’s about making sure your business plays by the financial rules of the game. Think of it as the official rulebook for handling money, designed to keep everything fair, transparent, and above board for everyone. No secret handshakes, no funny business.
The Official Rulebook for Your Money
Imagine your business is a player in a pretty high-stakes game. The prize isn't just turning a profit; it's building a stellar reputation, earning your customers' trust, and ensuring your company sticks around for the long haul. In this game, financial compliance is the friendly but firm referee who makes sure you’re not accidentally running off with the ball. It’s not about memorising a load of baffling acronyms, but about understanding the core principles of fair play.
At its heart, being 'compliant' means you’re taking solid steps to protect customer money, prevent financial shenanigans, and keep your operations as honest as the day is long. It’s the framework that holds everything together.
What Does the Referee Actually Watch For?
The compliance referee has their eye on a few key areas of the game. These aren't just bureaucratic hurdles designed to give you a headache; they are the pillars that support a trustworthy financial environment. Once you get your head around the 'why' behind these rules, figuring out the 'how' becomes a whole lot easier.
A solid compliance approach is built on a few core principles that every business, no matter its size, needs to understand. To make it clearer, here’s a quick breakdown of what compliance really covers.
The Core Pillars of Financial Compliance
| Compliance Pillar | What It Means in Simple Terms |
|---|---|
| Protecting Customers | Making sure your clients' money is handled responsibly and that they are always treated fairly. This builds the kind of trust that keeps them coming back (and telling their friends!). |
| Preventing Financial Crime | Actively working to stop illegal activities like money laundering and fraud. This protects not just your business but the wider economy, too. Think of yourself as a financial superhero. |
| Maintaining Transparency | Keeping clear, accurate records and being open about your financial activities with regulators. Honesty really is the best policy here, and it saves a lot of awkward conversations later. |
Understanding these pillars shifts your perspective from seeing compliance as a chore to recognising it as a vital part of a smart business strategy.
The goal of financial compliance isn't to slow you down; it's to build a foundation of trust and stability that allows your business to grow safely and sustainably. Without it, you’re just playing a risky game without a safety net.
Getting these fundamentals right from the start will save you a world of headaches down the line. Ready to get in the game and play to win? Our team at Artema can help you understand the rules.
Why You Can’t Afford to Ignore Compliance
Let's be honest, the words "financial compliance" don't exactly scream "fun weekend activity." It often feels like a mountain of paperwork and a chore you’d much rather put off until… well, forever. So, why bother with all the fuss?
The simple answer is that ignoring compliance is like trying to build a house of cards during a light breeze. Sooner or later, things are going to get wobbly.
Thinking of compliance as just a box-ticking exercise to avoid fines is missing the bigger picture. In reality, strong compliance is a business superpower. It's the bedrock of trust between you and your customers. When people know their money is safe with you, they don’t just become customers; they become loyal fans.
More Than Just Avoiding Fines
Of course, the penalties for non-compliance are a major motivator. Fines can be steep enough to make your eyes water, especially for a growing business. But the true cost of getting it wrong goes far beyond a single financial hit.
The reputational damage from a compliance failure can be catastrophic. News travels fast, and a story about a company playing fast and loose with customer funds can shatter years of hard-won trust in an instant. This is the kind of business insurance you simply can't buy. It’s earned through consistent, diligent effort.
Imagine this: a small investment firm cuts corners on its anti-money laundering checks to onboard clients faster. When a regulator uncovers this, the firm faces not only a hefty fine but also a public relations nightmare. Existing clients pull their investments, and potential new clients run for the hills. The business never fully recovers.
This kind of cautionary tale is more common than you might think. Protecting your brand, your team, and your company's future starts with taking your responsibilities seriously.
The Hidden Benefits of Staying Compliant
Beyond just dodging disaster, a robust compliance framework brings some fantastic, and often overlooked, advantages to your business. It forces you to have better processes, clearer records, and a deeper understanding of your own operations.
Here are a few ways compliance acts as a secret weapon for growth:
- It Builds Unbreakable Trust: When customers feel secure, they're more likely to do business with you and recommend you to others. This is your strongest marketing tool.
- It Improves Decision-Making: Good compliance means good data. Having organised, accurate financial records allows you to make smarter, more informed decisions about your business's future.
- It Protects Your Team: Clear rules and procedures protect your employees from making unintentional mistakes that could have serious consequences for them and the company.
A Foundation for Sustainable Growth
Ultimately, financial compliance is about creating a stable and ethical foundation for your business to stand on. Understanding and managing risks is fundamental to this process. As regulatory bodies often mandate robust frameworks, learning how to conduct effective risk assessment is a critical skill for any business owner.
It's the difference between a business that's built to last and one that's a ticking time bomb. By embracing compliance, you’re not just following the rules—you're investing in your company’s resilience, reputation, and future success.
Feeling a bit overwhelmed? You don't have to navigate this alone. At Artema, we can help you build a compliance strategy that protects your business and lets you focus on what you do best. Get in touch today for a friendly chat!
Meeting the UK’s Top Financial Regulators
Alright, so you know why financial compliance is a big deal. Now, let’s get to know the people who actually set the rules. Welcome to the UK’s financial landscape, where a couple of key players act as the head referees of the game.
It’s best to think of them less as scary headmasters and more as the guardians of a fair and stable financial system. Understanding who they are and what they care about is the first step to playing the game well. Don’t worry, we’ll skip the dense legal jargon and keep it simple.
The Two Main Referees on the Pitch
In the UK, the job of financial oversight is split between two main bodies. They work together, but each has a distinct role. You can think of them as a referee and an assistant referee—both are watching the game, but they’re focusing on different things.
-
The Financial Conduct Authority (FCA): This is the referee you'll interact with most often. The FCA's main job is to protect consumers. They make sure financial firms are treating customers fairly, communicating clearly, and not selling dodgy products. If your business deals directly with the public, the FCA is your new best friend (who you definitely want to keep on-side).
-
The Prudential Regulation Authority (PRA): The PRA is a bit more behind-the-scenes. As part of the Bank of England, its focus is on the bigger picture—the stability of the entire UK financial system. They regulate the big players like banks and insurance companies to ensure they're financially sound and won't suddenly collapse, taking everyone’s money with them.
For most small businesses, sole traders, and investors, the FCA's rulebook will be your primary guide.
Translating the Rulebook into Plain English
These regulators create rules with some hefty-sounding names, but the ideas behind them are usually quite straightforward. Let’s decode a couple of the big ones you’ll almost certainly bump into.
First up is Anti-Money Laundering (AML). It might sound like something out of a spy film, but for your business, it simply means you need to be confident you know who your customers are. It’s all about having procedures in place to stop criminals from using your services to wash their dirty money.
Then there's the Consumer Duty. This is a relatively new but incredibly important rule from the FCA. It boils down to one simple principle: you must act to deliver good outcomes for your customers. It's no longer enough just to avoid misleading people; you have to proactively ensure your products and services are fair, clear, and genuinely helpful.
The Consumer Duty fundamentally shifts the focus from 'Are we following the rules?' to 'Are we doing the right thing for our customers?' It's about embedding fairness into the very core of your business operations.
This rule means you need to think about your customer's journey from start to finish, making sure you're putting their interests first at every single stage.
Staying on Top of Regulatory Priorities
The UK's financial compliance landscape is always evolving. New technologies, global pressures, and a constant push for better consumer protection keep things moving. For instance, the Financial Conduct Authority (FCA) has sharpened its focus for the coming years. Financial crime is one of its four main priorities in its 2025–2030 strategy, with clear goals to cut down on investment fraud and money laundering.
With the FCA investing more in financial crime intelligence, UK firms with sloppy data or poor customer checks are facing more scrutiny than ever. This, combined with the Consumer Duty introduced in 2023, firmly links regulatory rules to real-world customer outcomes. You can explore a deeper analysis of what to expect in UK financial services regulation.
Understanding these priorities helps you focus your compliance efforts where they matter most. It’s not about being perfect; it’s about showing the regulators you’re aware of the risks and are making a genuine effort to manage them.
Navigating the world of UK regulators can feel daunting, but it doesn't have to be a solo mission. At Artema, we help businesses like yours understand and implement these rules in a practical, stress-free way. Give us a call today, and let's make sure you're playing to win.
Staying Ahead of Evolving UK Regulations
If financial compliance were a weather forecast, the prediction would almost always be "changeable with a high chance of new rules." Just when you think you’ve got everything sorted, the regulatory landscape shifts again. You can't just set your compliance strategy and forget about it; it’s a living, breathing part of your business that needs constant attention.
So, why all the change? Well, the world doesn’t stand still. New tech pops up (hello, crypto!), global events cause economic ripples, and there's a constant demand for better consumer protection. Each of these things prompts regulators to update the rulebook.
Think of it like updating the software on your phone. You do it to patch security holes and make sure everything runs smoothly. Staying on top of regulatory changes does the same for your business—it protects you from new risks and keeps you on the front foot.
The Rise of Operational Resilience
One of the biggest trends in UK financial compliance right now is operational resilience. It sounds a bit jargony, but the idea is actually quite simple: can your business handle a major disruption and bounce back without causing harm to your customers?
This isn't just about surviving a power cut. Regulators want to know you have a solid plan for all sorts of wobbles, including:
- Cyber-attacks: What happens if your systems are hacked? How do you protect customer data?
- Economic shocks: How would your business cope with a sudden market crash?
- Third-party failures: What if a key supplier you rely on suddenly goes out of business?
Building resilience means identifying your most important business services, understanding what could go wrong, and having a plan B (and maybe a plan C) ready to go. It’s all about being prepared for the unexpected. You can check out our guide on how your accounts system can help with resilience and compliance with rules like MTD for VAT.
In a nutshell, operational resilience is about being robust enough to take a punch and keep going. It proves to regulators, and more importantly to your customers, that you're a safe pair of hands.
Keeping Pace with a Changing World
The UK’s financial compliance scene is always a hot topic, with new priorities emerging constantly. According to the FCA’s own data for 2022–2025, while most firms are managing their financial requirements well, operational resilience has become a major headache. The number of operational incidents reported to the FCA has increased, with cyber threats topping the list of concerns. You can read the full FCA report on outcomes and metrics to see the trends for yourself.
This data tells us exactly where the regulators' focus is shifting. It shows us that simply having enough money in the bank isn't enough anymore; you also have to prove your business is tough enough to withstand modern threats.
Your Strategy for Staying Informed
So, how do you keep up without spending all day reading dense legal documents? The key is to make it a manageable habit.
- Follow the Regulators: The FCA and PRA websites are your primary sources. They regularly publish updates and guidance (often with surprisingly readable summaries!).
- Read Industry News: Sign up for newsletters from reputable financial news outlets. They do the hard work of sifting through the noise for you.
- Work with Professionals: This is where we come in. A good accountant or compliance expert stays on top of these changes so you don't have to.
Financial compliance is an ongoing journey, not a destination. By staying informed and adaptable, you can turn what feels like a headache into a powerful advantage, keeping your business secure and a step ahead of the competition.
Feeling like you're trying to catch a moving train? Contact Artema today, and let us help you stay on the right track with your compliance strategy.
Building Your First Compliance Framework
Alright, let's roll up our sleeves and move from theory to practice. How do you actually do compliance without drowning in paperwork? The good news is you don’t need an army of lawyers to get started. Building your first compliance framework is all about taking sensible, practical steps.
Think of it as creating a custom-made playbook for your team. It's a clear guide that outlines how you handle important financial tasks, protect customer info, and stay on the right side of the law. The goal is to make everything less mysterious and give everyone confidence.
This infographic shows how technology, global events, and consumer protection are all shaping the evolution of financial rules.
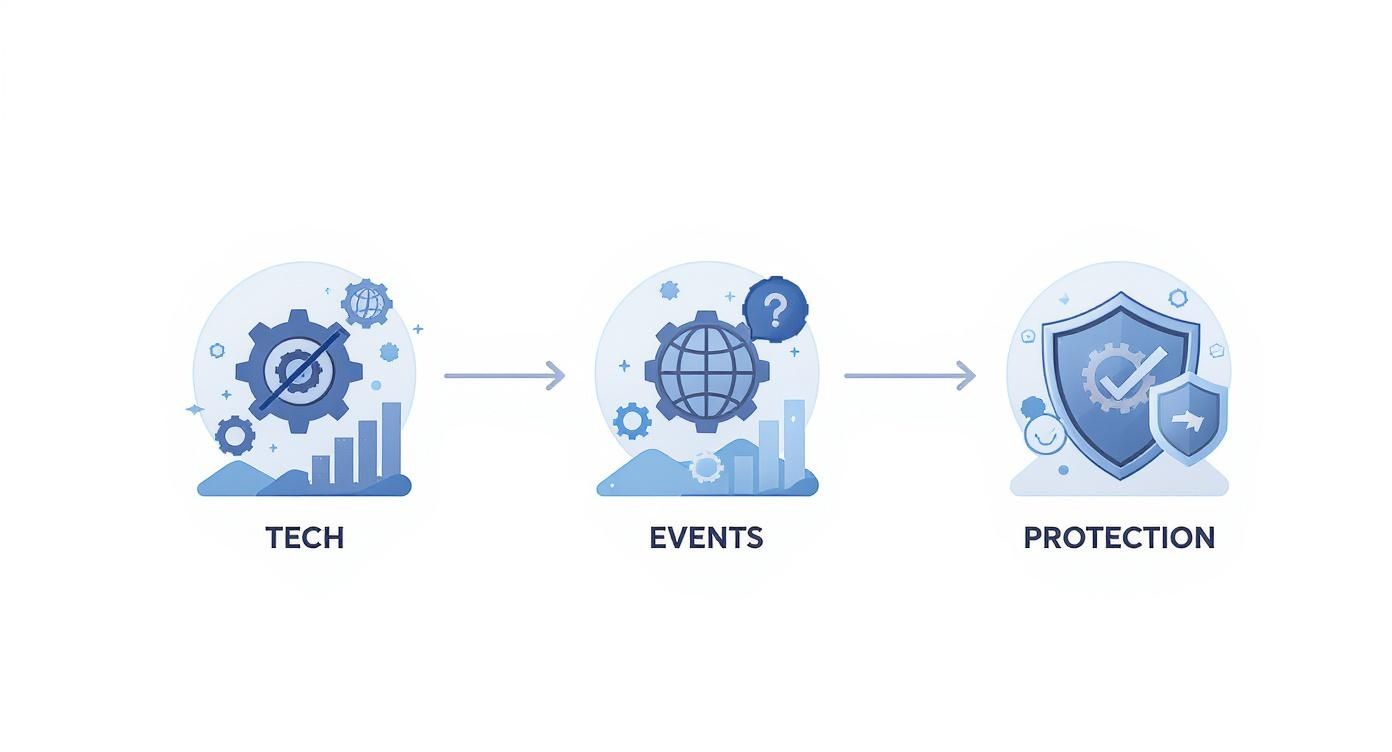
As you can see, compliance isn't a static, tick-box exercise. It’s a living process that has to adapt to real-world changes and risks.
Start with a Simple Risk Assessment
Before you can build your fortress, you need to know where the weak spots are. A risk assessment might sound intimidating, but it’s really just a structured way of asking, "What could go wrong here?"
Pour yourself a cuppa and have a proper think about your daily operations. Where does money change hands? How do you store customer data? Who has access to sensitive information?
Jot down a list of potential risks, no matter how small they seem. This could be anything from a team member accidentally sharing a password to failing to verify a new client's identity. Once you know where your vulnerabilities lie, you can start putting up your defences.
Create Your Own Team Rulebook
Now it’s time to get your internal policies down on paper. These don't need to be lengthy legal tomes; they should be clear, simple instructions that your team can actually follow. Your rulebook should cover a few key areas.
Here are the essentials to include:
- Customer Onboarding: How will you verify the identity of new clients to prevent fraud? This process is often called "Know Your Customer" or KYC.
- Data Protection: What are your procedures for handling sensitive customer information? Detailing this is crucial. You can learn more in our guide on the important General Data Protection Regulation.
- Complaint Handling: What is the step-by-step process for a customer to raise a concern, and how will your team respond fairly and promptly?
- Transaction Monitoring: What red flags will you look for to spot suspicious financial activity?
When you're building a robust compliance framework, it's also a great idea to integrate official identifiers like the Legal Entity Identifier (LEI) for any companies you work with. This adds a solid layer of verifiable information to your processes.
Train Your Team and Use Technology
Your framework is only as strong as the people using it. Regular training ensures everyone on your team understands the rules and, more importantly, why they matter. This doesn't have to be a boring seminar; a quick monthly update or a short online module can do the trick.
This is also where technology can become your best friend. Modern tools can automate many of the tedious bits of compliance. So-called 'RegTech' can help you verify identities in seconds, monitor transactions automatically, and keep your records perfectly organised.
Using the right technology doesn't just make compliance easier—it makes it better. It reduces the risk of human error and provides a clear, auditable trail that shows regulators you’re taking your responsibilities seriously.
Thankfully, the UK government is also working to make things more manageable. Recent regulatory reforms are reshaping financial compliance by streamlining processes, especially for smaller firms. A package of changes aims to recalibrate the rules, including simplifying the Senior Managers and Certification Regime (SMCR), which is expected to cut the compliance burden by an estimated 50%.
Feeling ready to build your own framework but not sure where to start? Chat with the team at Artema, and we can help you create a practical, effective compliance plan that fits your business perfectly.
Your Top Financial Compliance Questions Answered
Feeling a bit lost in the maze of financial compliance? You're definitely not the only one. It's a topic that seems designed to be confusing, but a few simple answers can make a world of difference. Here, we tackle some of the most common queries we hear.
We’ve kept each response clear, practical, and completely free of jargon. The goal is to clear up any lingering confusion and give you the confidence you need to get your compliance in order.
What Is the Difference Between Regulatory and Financial Compliance?
This is a fantastic question and one that often trips people up. Think of it like this: 'regulatory compliance' is the massive umbrella covering all the rules for every industry. It includes everything from health and safety on a building site to data protection for a tech start-up.
'Financial compliance' is a very important, specialised slice under that main umbrella. It focuses squarely on the rules for handling money, preventing financial crime, and protecting consumers in the financial services sector.
So, in short: all financial compliance is a form of regulatory compliance, but not all regulatory compliance is financial. It's the specific rulebook for the world of money.
Does My Small Business Really Need to Worry About This?
In a word: absolutely. While a huge international bank will have a much bigger compliance department than a local financial advisor, the core principles apply across the board. If your business handles client money, processes payments, or gives any form of financial advice, you’re in the game.
Regulators like the FCA are increasingly focused on how firms of all sizes treat their customers, especially with rules like the Consumer Duty. This rule places the responsibility on every business to deliver good outcomes for their clients, no matter how big or small the company is.
The key isn't to copy a multinational's setup. It's about creating a sensible system that fits your business's specific size and risks. Ignoring it isn't an option, but scaling it to your needs is the smart move.
For a small business, financial compliance isn't about creating bureaucracy for its own sake. It’s about building a solid, trustworthy foundation that protects both your customers and your company's future from day one.
What Are the First Steps to Becoming Compliant?
The thought of where to begin can be the most daunting part, but don't panic! You don't need to do everything at once. The best approach is to take small, deliberate steps.
Here’s a simple three-step process to get you started:
- Run a Simple Risk Assessment: Start by pinpointing where things could go wrong in your business when it comes to money or customer data. Ask yourself: What are our biggest vulnerabilities?
- Write Down Your Key Policies: Create a straightforward "team playbook." Document how you'll handle essential tasks like verifying new client identities (KYC) and managing complaints. Keep it simple and clear.
- Train Your Team: Make sure everyone involved understands these basic rules and why they are so important. An informed team is your first and best line of defence.
Starting small is far more effective than getting overwhelmed and doing nothing. These first few steps create a strong base you can build upon as your business grows.
Can Technology Help with Financial Compliance?
Yes, and in a massive way! When it comes to managing compliance efficiently, technology is your best mate. The world of 'RegTech' (Regulatory Technology) has produced some brilliant tools designed to make your life easier.
These systems can automate many of the time-consuming tasks that are essential for good compliance. For example, technology can:
- Automate Customer Checks: Instantly verify customer identities and screen them against watchlists, saving you hours of manual work.
- Monitor Transactions: Use smart algorithms to flag suspicious activity in real-time, helping you spot potential financial crime before it becomes a major problem.
- Organise Records: Keep all your compliance documentation neat, tidy, and easily accessible. This is invaluable when you need to prove you're doing everything by the book.
Putting money into the right technology can save you a huge amount of time, dramatically reduce the risk of human error, and provide genuine peace of mind. It’s an investment that truly pays for itself.
Feeling clearer on financial compliance but still want a helping hand to guide you? At Artema Ltd, we specialise in helping sole traders, investors, and small business owners navigate these complexities. We'll help you build a compliance strategy that fits your business perfectly, so you can focus on growth.
Visit us at Artema to learn more and book a consultation today!