
Ever feel like you’re running a free loan service for your customers? You do the work, send the invoice, and then… crickets. You wait weeks, maybe even months, for the money you're owed to finally land in your bank account. Invoice factoring is the brilliant financial hack that lets you skip the waiting game.
In a nutshell, it’s a way for businesses to sell their unpaid invoices to a third party (a factoring company) at a small discount. In return, you get the cash you’ve earned almost instantly. It’s like hitting the fast-forward button on your cash flow.
Why Waiting for Payments Stalls Your Business Growth
It’s the most common—and let’s be honest, most frustrating—waiting game in business. You’ve done fantastic work, sent the invoice with a polite “thank you,” and now… you hear nothing. Your cash is completely tied up while you wait 30, 60, or maybe even 90 days for payment to land. Sound familiar?
This cash flow crunch is more than just a minor headache; it can bring your business grinding to a halt. Projects get put on hold, payroll becomes a nail-biting experience, and exciting growth opportunities have to be shelved. It can feel like you’re trying to run a marathon with your shoelaces tied together.
The Real Cost of Delayed Payments
The impact of late payments goes well beyond the numbers on a spreadsheet. The wider UK economy continues to squeeze company cash flow and growth prospects. A recent survey of 200 UK businesses revealed that the top three challenges remain the same: growing sales, economic uncertainty, and managing cash flow. It really highlights the need for smart financial tools.
This constant waiting game creates a cycle of uncertainty that can be incredibly difficult to break. But what if you could sidestep the wait entirely? What if you could unlock the money tied up in your unpaid invoices and turn it into working capital right now?
Turning Invoices into Instant Cash
This is exactly where invoice factoring swoops in to save the day. It’s a practical solution to this universal problem, letting you access the funds you’ve already earned without the long, anxious wait. Think of it as selling an asset—in this case, your invoice—to get cash now, right when you need it most.
It’s important to remember that this isn't a loan, so you’re not taking on new debt. You're simply accelerating your cash flow. This is a game-changer for businesses that need to:
- Cover immediate expenses like rent and salaries.
- Purchase stock or materials for the next big job.
- Invest in new equipment to fuel expansion.
- Simply have a healthier bank balance for peace of mind.
Businesses grapple with these cash flow challenges all the time, which makes solutions like exploring contract factoring services a valuable strategy. By figuring out how to get paid faster, you can take back control of your finances. You can also check out our guide on the 5 steps to create a cash flow for your business for more tips.
How Invoice Factoring Works Step by Step
So, how does this magic trick of turning unpaid invoices into instant cash actually work? It’s far less complicated than pulling a rabbit out of a hat. Really, it’s a straightforward process that just rearranges the order in which you get paid.
Imagine you have a valuable, sold-out concert ticket for a gig that's three months away. You know it’s worth its full face value, but you need the money now. Instead of waiting, you sell the ticket to a friend for a little less than its face value. You get cash in your pocket straight away, and your friend gets the ticket's full value when they go to the concert.
Invoice factoring operates on the exact same principle. Your unpaid invoice is the concert ticket, the factoring company is your helpful friend, and your customer is the one who ultimately pays up at the concert. You’re simply selling an asset you already own—the invoice—to get your money faster.
The Key Players in the Process
To get a clear picture of how invoice factoring works in practice, it helps to understand who's involved. There are three main parties in this financial team-up, each with a specific role.
- Your Business: You're the one who has done the great work and issued an invoice. You’re looking for a way to get paid sooner rather than later.
- Your Customer (The Debtor): This is the company that owes you money for your services or products. They will eventually pay the invoice, but on their own sweet time (e.g., 30 or 60 days).
- The Factoring Company (The Factor): This is the financial partner that buys your invoice. They provide the immediate cash and then take on the job of collecting the payment from your customer.
Breaking Down the Factoring Journey
The journey from a pending invoice to cash in your account is typically quick and efficient. While the finer details can vary between providers, the main steps are pretty consistent and designed to get you funded as fast as possible.
1. You Do Your Thing and Invoice Your Customer
Everything starts as usual. You deliver your brilliant product or service, raise an invoice for the total amount, and send it to your customer. This is where the 60-day waiting game would normally begin. But not this time.
2. You Sell the Invoice to a Factoring Company
Instead of staring at your calendar, you send a copy of this unpaid invoice to your chosen factoring partner. They’ll check the details to make sure it's a legitimate debt from a reliable customer. This isn't about your credit score; it's all about the quality of the invoice itself.
3. Ka-Ching! You Get a Big Chunk of Cash
This is the best part. Once the invoice is approved, the factoring company advances you a large slice of its value, usually within 24 to 48 hours. This can be anywhere between 70% and 90% of the total invoice amount. That’s the bulk of your money, ready to be used.
The infographic below gives a simple visualisation of this process.
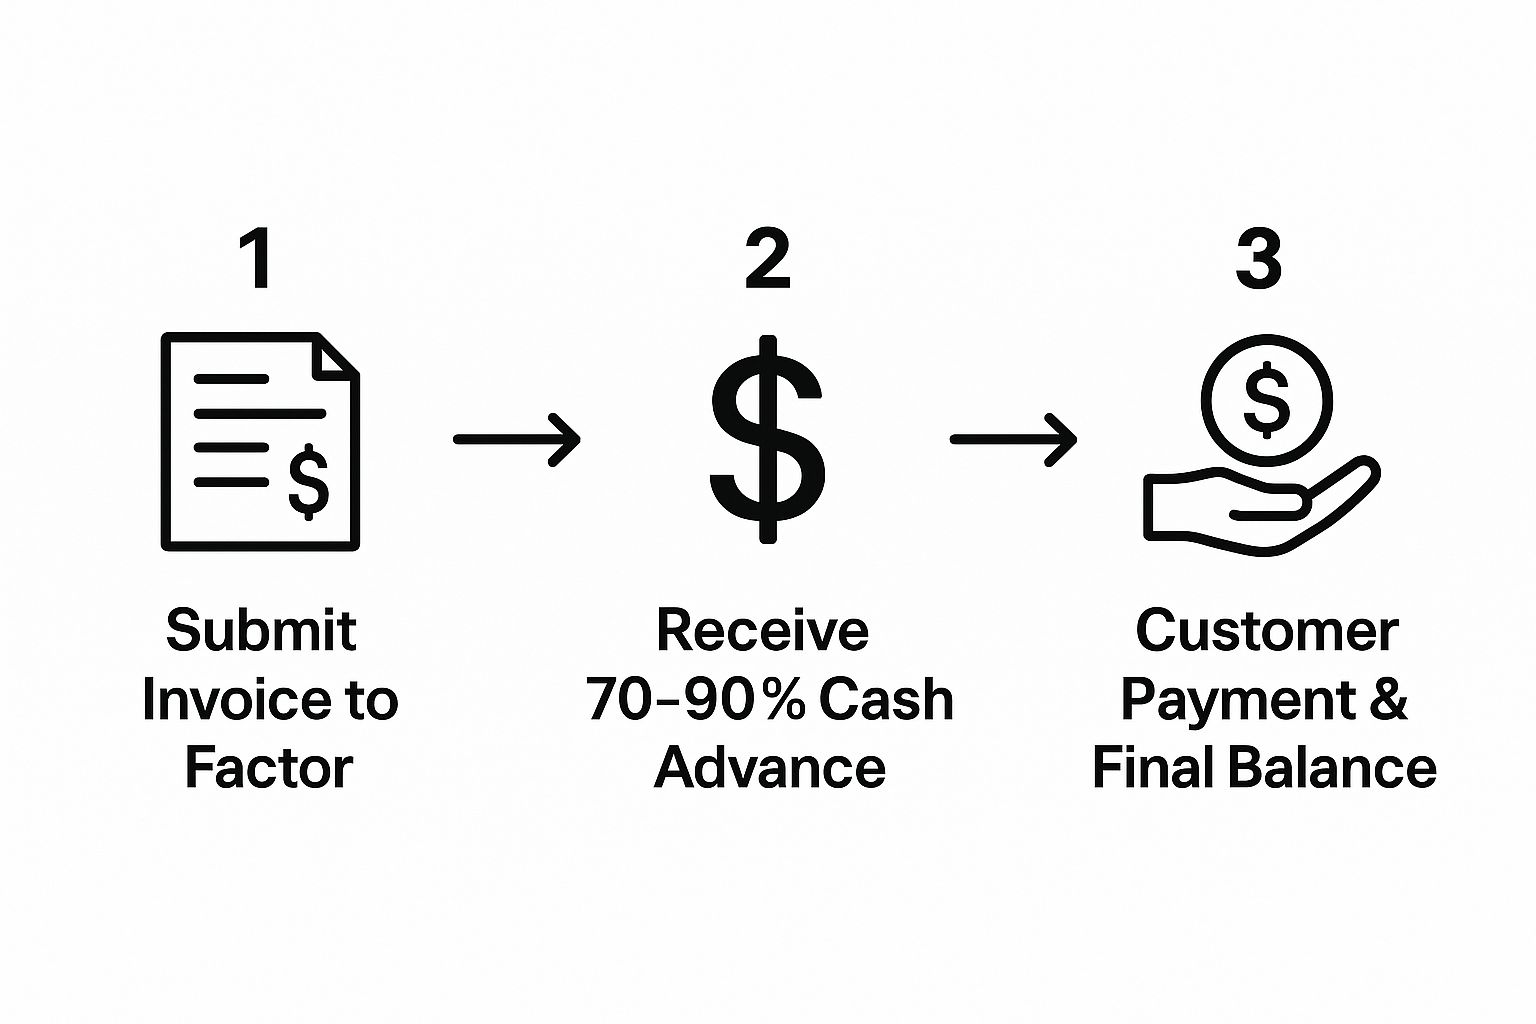
This visual guide neatly summarises how quickly you can convert an outstanding invoice into usable working capital for your business.
4. The Factoring Company Chases the Payment (So You Don't Have To)
Now you can relax. The factoring company’s professional team will manage your sales ledger and collect the full payment from your customer when it's due. No more spending your valuable time sending awkward reminder emails. Phew!
5. You Get the Rest of Your Money
Once your customer pays the invoice in full to the factoring company, they will release the remaining balance to you, minus their agreed-upon fees. You get the rest of your money, and the process is complete. Invoice factoring in the UK is a major financial service that helps businesses, especially SMEs, by converting their unpaid invoices into immediate cash. To learn more about how factoring rates work in the UK, you can explore valuable insights about invoice factoring companies.
To help put all of this into perspective, here’s a simple table that maps out the entire journey.
The Invoice Factoring Journey From Invoice to Cash
| Stage | What Happens | Who Is Responsible |
|---|---|---|
| 1. Service Delivery | You provide your service or product to your customer. | Your Business |
| 2. Invoicing | You create and send an invoice with standard payment terms (e.g., 30, 60 days). | Your Business |
| 3. Invoice Sale | You submit a copy of the approved invoice to the factoring company. | Your Business |
| 4. Cash Advance | The factor verifies the invoice and advances you 70-90% of its value. | The Factoring Company |
| 5. Payment Collection | When the invoice is due, the factor collects the full amount from your customer. | The Factoring Company |
| 6. Final Settlement | The factor sends you the remaining balance, minus their fee. | The Factoring Company |
As you can see, the process is designed to be as hands-off for you as possible after the initial invoice submission, letting you focus on running your business.
Key Takeaway: Invoice factoring isn't a loan. It's the sale of a financial asset. You're not creating debt; you're simply unlocking the value of money that is already owed to you, making it one of the most effective ways to manage your cash flow.
The Pros, Cons, and Costs of Invoice Factoring
No financial tool is a magic wand that solves every problem with a flick of the wrist (if only!). Invoice factoring is powerful, but it’s essential to have a balanced, honest look at what to expect. Let’s get real about the good, the not-so-good, and the costs involved, so you can decide if it’s the right fit for your business.
Think of it like getting a takeaway. The biggest pro is getting a delicious meal delivered to your door almost instantly, saving you hours of cooking. The con? It costs a bit more than making it yourself. Invoice factoring works in a similar way—you're paying for speed and convenience.
The Major Benefits of Invoice Factoring
The most obvious advantage is the immediate injection of cash into your business. Waiting 60 days for a payment can feel like an eternity when you have bills to pay today. Factoring turns that wait into a 24-hour reality, transforming your cash flow from a slow trickle into a healthy, flowing river.
But the perks don't stop there. Here are some of the key benefits:
- Fewer Admin Headaches: You can say goodbye to spending hours chasing late payments. The factoring company’s professional team takes over credit control, freeing you up to focus on what you do best—running your business.
- Protection Against Bad Debt: With non-recourse factoring, the factoring company assumes the risk if your customer fails to pay due to insolvency. It’s like having an insurance policy against your customer's financial trouble.
- Funding That Grows With You: Unlike a fixed bank loan, factoring is flexible. The amount of funding available grows as your sales grow. More invoices mean more available cash, making it a perfect partner for ambitious, expanding businesses.
Invoice factoring isn't just about surviving; it’s about thriving. By unlocking working capital, it allows you to take on larger orders, negotiate better terms with suppliers, and confidently invest in growth without taking on traditional debt.
Understanding the Costs Involved
Naturally, this service comes with a cost. Factoring companies aren’t charities, after all! The fees are usually broken down into two main parts, and understanding them is key to knowing exactly what you're paying for.
1. The Discount Fee (or Factoring Fee)
This is the main cost, calculated as a percentage of the invoice's value. It's typically between 1% and 4% and is charged for the time it takes your customer to pay. Think of it as a small "thank you for the fast cash" fee.
2. The Service Fee (or Admin Fee)
This fee covers the work the factoring company does for you, such as managing your sales ledger, chasing payments, and processing everything. It can be a flat monthly fee or a percentage of your turnover.
For example, on a £10,000 invoice with a 90% advance and a 2% discount fee, you’d get £9,000 upfront. Once your customer pays, you'd receive the final £1,000, minus the £200 fee (2% of £10,000) and any service charges. You get your money fast, and the factor gets paid for their service.
Potential Downsides to Consider
While the benefits are compelling, it’s important to be aware of the potential cons. The most significant is the cost—it’s generally more expensive than a traditional bank loan. You are paying a premium for speed, convenience, and access to funding that might otherwise be unavailable.
Another consideration is the impact on customer relationships. In a disclosed factoring arrangement, your customers will know you're using a third party to collect payments. While this is a common business practice, you need to choose a factoring partner with a professional and respectful collections team to maintain your good relationships.
Finally, it's crucial to remember that factoring is the sale of an asset (your invoices), not a loan. This means you lose a degree of control over your sales ledger. For business owners who prefer to manage every aspect of customer interaction themselves, this can be a difficult adjustment.
Deciding if invoice factoring is right for you involves weighing these pros, cons, and costs against your unique business needs.
If you’re ready to explore how this could work for your business, our friendly team at Artema is here to help. Get in touch with us today for a no-obligation chat about your cash flow.
Is Invoice Factoring Right for Your Business?
So, you get the what and the how, but the real question is: does invoice factoring actually make sense for your business? It’s not a one-size-fits-all solution. Think of it like deciding whether to get a dog – a brilliant idea for some, but maybe not the best fit if you live in a tiny flat and are allergic to fur.
Let’s cut through the jargon and figure out if factoring aligns with your specific needs. This is your friendly guide to making a smart financial decision, without the stuffy bank manager vibe. We’ll look at the businesses that thrive with factoring and those that might be better off exploring other routes.
When Invoice Factoring Is a Perfect Match
Certain business models are practically made for invoice factoring. If you find yourself nodding along to any of these situations, it could be a fantastic tool for your financial toolkit.
- You're Growing at Lightning Speed: Fast-growing companies often face that classic "good problem to have." You’re winning huge new orders, but you need cash now to buy materials or hire the staff to fulfil them. Factoring bridges that gap, turning your new invoices into the fuel you need to keep up with demand.
- You're Stuck in 'Payment Term Purgatory': Do your customers consistently pay on 60 or 90-day terms? It can feel like you’re giving them an interest-free loan. Factoring frees you from this waiting game, making sure your cash flow stays predictable and healthy.
- You Run a Seasonal Business: For businesses that are flat-out during certain times of the year, cash flow can feel like a rollercoaster. Factoring can provide the capital you need during the quiet months to prepare for the busy season, ensuring you’re always ready to hit the ground running.
A brilliant real-world example is a recruitment agency. Imagine you run a temp agency that has to pay its staff every single Friday. Your corporate clients, however, all operate on monthly payment terms. This creates a massive weekly cash flow headache. Invoice factoring solves this perfectly, giving you the funds to cover payroll without chasing your clients.
When You Might Want to Swipe Left on Factoring
Just as it’s a game-changer for some, invoice factoring isn’t always the right choice for every business. It’s important to be honest about whether your operations are a good fit.
Here are a few situations where it might not be the best option:
- Your Invoices Are Teeny-Tiny: If your business deals with a high volume of very small invoices, the admin and fees that come with factoring might outweigh the benefits. Most factoring companies have a minimum invoice value to make the process worthwhile for everyone.
- Your Customers Have Shaky Credit: Remember, factoring companies are essentially buying your customer's debt. They will check the creditworthiness of your clients before agreeing to buy their invoices. If you have lots of customers with poor payment histories, you may struggle to get approved.
- You Have Very Tight Profit Margins: The fees involved in factoring, while often modest, do eat into your profit on each sale. If your margins are already razor-thin, giving away a percentage of each invoice might not be financially sustainable in the long run.
Ultimately, the decision comes down to a simple cost-benefit analysis. Does having immediate access to cash and spending less time on admin justify the fees? For countless businesses, the answer is a resounding yes. It empowers them to say yes to growth, pay suppliers on time, and sleep better at night.
If you’re still unsure whether it's the right path for your business, why not have a chat with an expert? Contact the Artema team today, and we can help you weigh up the options with no strings attached.
Factoring Compared to Other Funding Options
Invoice factoring is just one tool in the business finance toolbox, and let's face it, that toolbox can look pretty crowded. To help you choose the best one for the job, it’s useful to see how factoring stacks up against the other usual suspects. It’s a bit like choosing a car; a sporty two-seater is great for a weekend trip, but you'll want something bigger for the weekly shop.
We’ll compare factoring directly with some of the most common funding options: the traditional bank loan and its close relative, invoice discounting. Understanding their key differences will help you confidently select the right strategy to solve your specific cash flow challenges without getting lost in financial jargon.
Factoring Versus a Traditional Bank Loan
A traditional bank loan is often the first thing people think of when they need business funding. It involves borrowing a lump sum of money that you pay back in regular instalments over a set period, with interest. It's a reliable, old-school method, but it’s not always the fastest or most flexible.
The main differences really come down to speed and what the lender is looking at:
- Approval Process: Getting a bank loan can be a slow, paperwork-heavy process. Banks will meticulously examine your business credit history, trading history, and financial projections. In contrast, invoice factoring focuses on the creditworthiness of your customers, making it much more accessible for newer businesses without a long track record.
- Debt: A bank loan is new debt added to your balance sheet. Factoring, on the other hand, isn't a loan; it's the sale of an asset (your invoices). You're simply unlocking cash you're already owed.
A solid financial plan is crucial when applying for a loan, and you can learn more about crafting one in our guide to business plans and budgeting.
Factoring Versus Invoice Discounting
Invoice discounting is factoring’s slightly more reserved cousin. They look similar but behave quite differently. Both use your unpaid invoices to release cash, but the biggest distinction lies in who manages your sales ledger and chases payments.
With factoring, the finance provider takes over credit control. They manage your sales ledger and collect payments directly from your customers. This is great for businesses that want to outsource their collections process and save admin time.
With invoice discounting, you remain in control. You collect payments from your customers as usual, and they are typically unaware of the financing arrangement. This is often preferred by larger, more established businesses that have a dedicated credit control team in place.
When weighing up your funding options, it's always useful to explore various capital solutions. You can learn more about how the Kwilladvisors' Capital division approaches this.
To make this even clearer, let's break it down in a quick comparison table.
Funding Options at a Glance: Factoring vs. Alternatives
This table compares invoice factoring with other popular business financing methods to help you choose the right one for your specific situation.
| Feature | Invoice Factoring | Bank Loan | Invoice Discounting |
|---|---|---|---|
| Funding Speed | Very fast (24-48 hours) | Slow (weeks or months) | Fast (similar to factoring) |
| Qualification | Based on customer credit | Based on your credit score | Based on your turnover & credit control |
| Debt Creation | No, it's a sale of assets | Yes, a new loan is created | No, it's a confidential advance |
| Collections | Managed by the factor | You manage your customers | You manage your customers |
| Best For | SMEs needing fast cash & admin support | Established firms with strong credit | Larger firms with in-house collections |
Ultimately, choosing the right funding path is about matching the solution to your business's unique circumstances. While a bank loan offers structure, invoice factoring provides speed and flexibility, making it a powerful option for businesses that can't afford to wait.
How to Choose the Right Factoring Partner
So, you’re considering invoice factoring. That’s a great first step! But now you’ve hit the most critical part of the journey: choosing the right partner to work with.
Think of it a bit like a business partnership. You need someone you can trust, who is upfront about everything, and won't spring nasty surprises on you once you’re committed. The right factoring company becomes an extension of your own team, not just a faceless lender. They should understand your business, believe in what you’re doing, and treat your customers with respect when it’s time to collect payment.
Look for Industry Expertise
Not all factoring providers are cut from the same cloth. A company that specialises in the construction industry, for example, will already know the ins and outs of its unique payment cycles and contractual challenges. This is a world away from a generalist provider who might not grasp the nuances.
You want to find a partner with a proven track record in your specific field. Their experience means they can offer genuine support and advice that actually applies to your situation. Don't be shy about asking for case studies or to speak with other businesses like yours that they've worked with.
Understand the Contract Terms
Nobody wants to get bogged down in pages of confusing small print. The first thing to look at is the fee structure. Are all the costs laid out clearly, or are they buried in jargon? Total transparency here is non-negotiable.
Another crucial point to clarify is recourse vs. non-recourse factoring. With a recourse agreement, you are still on the hook for the debt if your customer fails to pay. Non-recourse means the factoring company takes on most of that risk, giving you what is essentially bad debt protection. It usually costs a little more, but for many, the peace of mind is well worth it.
The UK invoice factoring market continues to grow, even in a wobbly economy. While traditional financing still dominates with about 99.3% of the market, the rise of fintech is bringing far more flexible options to the table for businesses. You can find out more about how UK companies are managing cash flow to see the broader trends.
A Quick Checklist for Potential Partners
To help narrow down your options and find the perfect fit, here are a few essential questions you should be asking any potential provider:
- What are all your fees? Push for a complete, itemised breakdown with no hidden extras.
- Do you have experience in my industry? Ask them to prove it with concrete examples.
- What is your process for contacting my customers? Make sure their approach is professional and friendly.
- Is the agreement recourse or non-recourse? You need to know exactly where the risk sits.
- What are the contract length and exit terms? You don’t want to be locked into a long, inflexible deal.
Choosing the right factoring partner can make all the difference. For expert advice on how factoring can fit into your wider financial strategy, it's worth exploring the benefits of an outsourced financial function. With the right support in your corner, you can truly unlock the potential of your invoices.
Common Questions About Invoice Factoring Answered
We’ve covered a lot of ground on invoice factoring, from the nuts and bolts of how it works to how it measures up against other ways to fund your business. But you might still have a few questions ticking away. Let’s think of this as a final chat over a cuppa to clear up any last bits of uncertainty.
Will My Customers Know I Am Using a Factoring Company?
This is a big one, and the honest answer is yes, most of the time, they will. With standard invoice factoring, the finance company steps in to manage your sales ledger. A key part of their service is professionally chasing and collecting payments, which means they'll be in touch with your customers.
This is what's known as ‘disclosed’ factoring, and it's a completely normal and accepted way of doing business in the UK. Many companies will already be familiar with it and simply see it as a smart way to manage cash flow.
If keeping things confidential is a must, you might want to look into ‘invoice discounting’. It's a similar idea, but you stay in control of your own sales ledger, so your customers won't know a finance partner is involved behind the scenes.
What Is the Difference Between Recourse and Non-Recourse Factoring?
This is probably the most important detail to get your head around, and it all boils down to one simple question: who's responsible if your customer doesn't pay? It’s all about where the risk lies.
- Recourse Factoring: This is the most common and cost-effective option. With a recourse agreement, you're ultimately responsible for the debt. If your customer fails to pay an invoice, you’ll have to buy it back from the factoring company.
- Non-Recourse Factoring: This option gives you a bit more of a safety net. Here, the factoring company takes on most of the risk if your customer can’t pay because they’ve become insolvent. Think of it as a form of bad debt protection that provides real peace of mind. As you’d expect, this extra security comes at a slightly higher cost.
Choosing between recourse and non-recourse is a bit like deciding whether to take an umbrella on a cloudy day. Recourse is cheaper, but if it starts pouring (your customer doesn't pay), you get soaked. Non-recourse costs a little more, but it keeps you dry no matter what.
How Quickly Can I Get Funded After I Am Set Up?
Speed is really the name of the game here, and it's one of the main reasons businesses turn to invoice factoring. The initial setup with a provider might take a week or two while they do their checks and get your account organised. But once that’s out of the way, things move incredibly fast.
After you submit an approved invoice, you can often see the cash advance in your bank account within 24 to 48 hours. This rapid access to funds is what makes factoring such a powerful tool for covering daily running costs or seizing unexpected growth opportunities without a moment's hesitation.
Does My Business Credit Score Matter for Invoice Factoring?
This is where invoice factoring really comes into its own, especially for newer or fast-growing businesses. A traditional bank loan will put your business's credit history under a microscope, but invoice factoring looks at things differently. It's much more focused on the financial strength of your customers.
What the factoring company really cares about is the creditworthiness of the business that needs to pay the invoice. This means even if your business is young and doesn't have a long, sparkling credit history, you can still get funding. As long as you have good-quality invoices from reliable customers, your chances of approval are very strong. It's the strength of your sales ledger that truly matters.
We hope this has cleared up any lingering questions you had about what is invoice factoring. It’s a flexible and effective tool that helps countless UK businesses take control of their cash flow and focus on what they do best: growing.
If you think it could be the right solution for you, the next step is a simple conversation.
The friendly experts at Artema Ltd are here to help you explore your options with no pressure or confusing jargon. Get in touch with us today for a no-obligation chat to see how we can help your business thrive.