
If the phrase 'statutory accounts' makes you instinctively reach for a strong coffee, don't worry. You're not alone. In simple terms, they are the official annual report card for your limited company – a financial story you're legally required to prepare and share with the government each year. Think of it less as a dreaded exam and more as your company's official 'yearbook' photo.
Your Not-So-Scary Introduction to Statutory Accounts
Ever come across a term that sounds incredibly complicated, but the idea behind it is actually quite straightforward? "Statutory accounts" is a classic example. Let's cut through the jargon.
The word "statutory" just means it’s required by law. So, these are simply the accounts you are legally obligated to create. Think of it like your car’s annual MOT. It’s a mandatory check-up proving your vehicle is roadworthy and meets certain standards. Statutory accounts do the same for your business, showing it’s financially sound, transparent, and playing by the UK's rules.
Who Needs to File Them and Why?
So, who's on the hook for this annual financial check-up? If you run a private or public limited company in the UK, this one's for you. It applies to everyone, from the smallest one-person operation right up to the big leagues. It doesn’t matter if your company is making a mint or is currently 'resting its eyes' (dormant); the filing obligation is still there.
The main reason for this is transparency. These accounts are filed with Companies House, making them public records. This allows a few important groups to see how your company is getting on:
- Lenders and Investors: They can check your financial health before deciding to lend you money or invest. A bit like checking someone's dating profile before committing.
- Suppliers: They might have a look to feel confident you can pay your bills on time.
- The Public: It holds businesses accountable and builds trust in the marketplace.
To give you a quick summary, here's a simple breakdown of what these accounts are all about.
Statutory Accounts at a Glance
| Concept | Simple Explanation |
|---|---|
| What are they? | Your company's official, legally required annual financial statements. |
| Who files them? | All UK limited companies, including the sleepy (dormant) ones. |
| Why? | To provide transparency for the public, lenders, and HMRC. It's the law! |
| Who sees them? | They're public records filed with Companies House. Anyone can have a nosey. |
| Key Components | A balance sheet, a profit and loss account, and notes explaining the figures. |
Think of this table as your cheat sheet—the core facts without the fluff.
"At its core, filing statutory accounts is about being a good corporate citizen. It’s a formal promise of transparency that shows the world your business is operating openly and honestly."
This requirement is all laid out in the Companies Act 2006, which is basically the rulebook for UK companies. And with the number of UK businesses growing all the time, this kind of transparency is more important than ever. In the year ending March 2024, the total count of registered private UK businesses hit 4,871,801—a jump of 4.98% from the previous year. That’s a lot of companies navigating these rules, as you can see from the latest UK business growth data from the Department for Business and Trade.
Preparing these accounts can feel like a chore, but it’s a fundamental part of running a credible and successful limited company. Getting them right not only keeps you on the right side of the law but also gives you a clear, official snapshot of all your hard work over the past year.
Deconstructing Your Company's Financial Story
Alright, so we've established that statutory accounts are your company's official, non-negotiable annual report card. But what's actually inside this report? Peeking into a set of accounts for the first time can feel a bit like trying to assemble flat-pack furniture without the instructions. Don't worry, we’ve got the Allen key.
Think of your statutory accounts as your company’s financial story, told in three distinct chapters. Each one reveals something different, and together, they paint a complete picture.
This concept map breaks down the core purpose of statutory accounts into the what, who, and why.
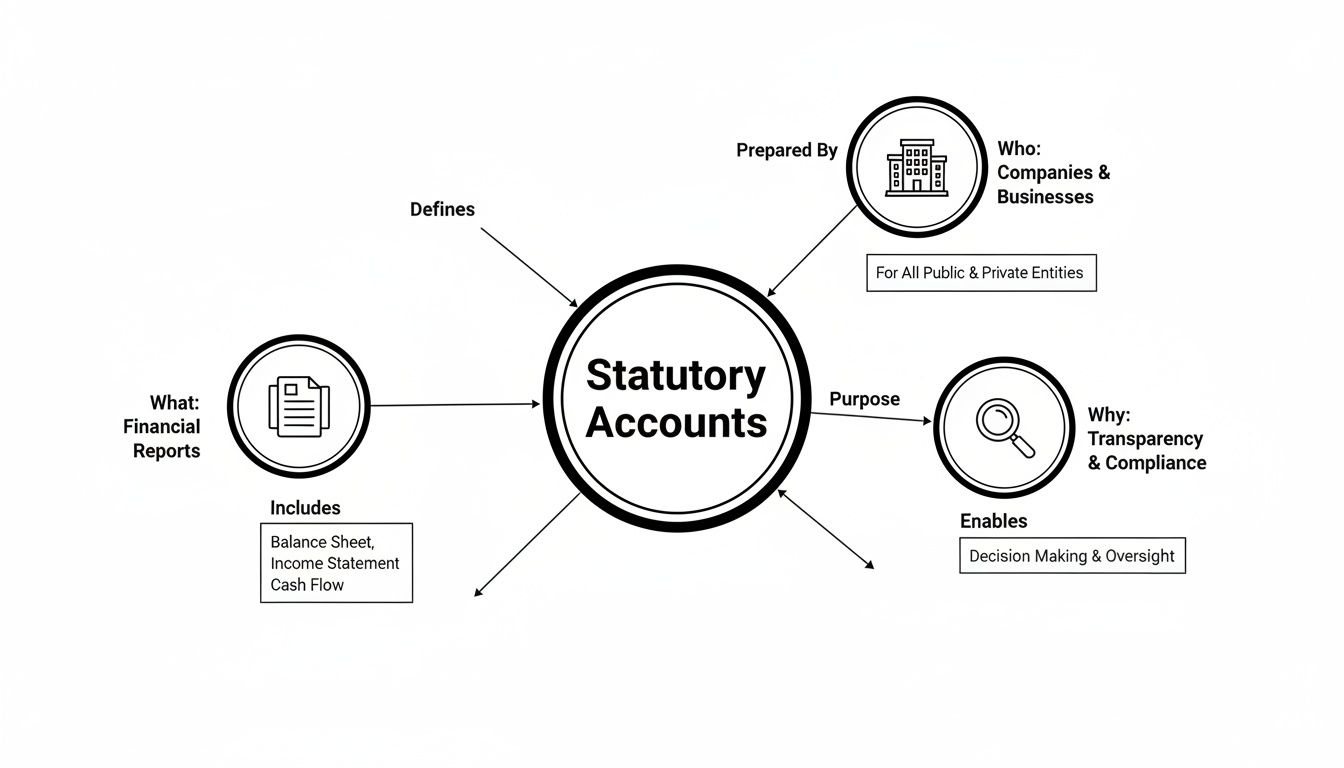
As the visual shows, it’s a required document for companies, produced to provide financial transparency.
The Balance Sheet: Your Financial Foundation
First up is the Balance Sheet. This is a snapshot of your company’s financial position on a single day—usually the last day of your financial year. It doesn't tell you about the journey; it just shows you where you’ve ended up. A financial "we are here" pin on the map.
The Balance Sheet follows a beautifully simple equation: Assets = Liabilities + Equity.
Let's break that down into plain English:
- Assets: All the good stuff your company owns. This includes cash in the bank, equipment, and money your customers owe you.
- Liabilities: All the stuff your company owes to others. Think bank loans, supplier bills you haven't paid yet, and taxes.
- Equity: What's left over for the owners after you’ve settled all your debts. It’s your slice of the pie.
Essentially, it balances what you have against what you owe, showing the net worth of your business at that moment.
The Profit and Loss Account: The Year's Blockbuster Movie
Next, we have the Profit and Loss (P&L) Account, sometimes called the Income Statement. While the Balance Sheet is a photo, the P&L account is a movie, detailing your performance over a 12-month period.
This report tells the story of your trading year. It starts with your total sales and then subtracts all your costs—from materials and rent to salaries and that all-important biscuit budget. What’s left at the bottom is your net profit (or, fingers crossed it's not the case, a loss).
It's the ultimate 'did we actually make any money?' report. The P&L account is arguably the most scrutinised part of your accounts because it directly answers that big, juicy question.
Understanding this document is crucial for seeing where your money is coming from and where it's going. For a deeper dive, you can learn more about how to read a profit and loss statement in our detailed guide: https://www.artema.co.uk/how-to-read-profit-and-loss-statement/.
The Notes to the Accounts: The Juicy Gossip
Finally, we have the Notes to the Accounts. These are the footnotes that add context and the nitty-gritty details behind the headline numbers. It’s where you explain how you arrived at the figures in the other statements.
They might seem like the boring small print, but they are incredibly important. The notes might break down your assets, explain your debts, or detail your accounting policies. They add transparency and ensure anyone reading your accounts can understand the full story, not just the highlights.
As you deconstruct your company's financial story, understanding modern reporting requirements like the UAE E-Invoicing compliance guide is essential for ensuring your data is accurate and compliant from the very start. These three components—Balance Sheet, P&L, and Notes—work together to create a robust, transparent, and legally compliant financial narrative.
Statutory Accounts vs Management Accounts
So, you’ve got your head around statutory accounts – the official, polished annual report card you show the world. But then you hear your accountant talking about "management accounts," and things get a bit confusing. Are they the same thing in a different hat? Not even close.
Let's break it down.
Think of your statutory accounts as your public-facing social media profile. It’s the carefully curated version you’re happy for anyone to see—well-presented, accurate, and telling the official story of your year. It's all about compliance and showing the outside world you're playing by the rules.
Your management accounts, on the other hand, are like your private group chat with your closest friends. This is where the real, unfiltered story of your business lives. It’s for your eyes only (and your leadership team's), packed with day-to-day details, honest opinions, and 'what-if' scenarios to help you make smarter, faster decisions.
What Is The Core Difference?
The main distinction boils down to two things: purpose and audience.
Statutory accounts are backward-looking. They report on what has already happened to satisfy your legal duties. The audience is purely external: Companies House, HMRC, and anyone else who fancies a look. Because of this, they must follow very strict legal formats.
Management accounts are all about looking forward. They’re designed to help you steer the ship, not just report on where it's been. The audience is internal—that means you and your team. And because of this, there are no rules. You can format them however you like to get the insights you need. Want to see sales broken down by a specific product? Go for it. Need to forecast your cash flow for the next quarter? That’s what they’re for.
While statutory accounts prove your compliance to the outside world, management accounts are the secret sauce you use to actually run and grow your business day-to-day.
A Head-to-Head Comparison
To make it crystal clear, let's put them side-by-side.
| Feature | Statutory Accounts | Management Accounts |
|---|---|---|
| Purpose | Comply with the law and report history. | Inform internal decisions and strategy. |
| Audience | External: HMRC, Companies House, etc. | Internal: Owners, directors, managers. |
| Format | Strictly regulated by UK law & standards. | Totally flexible and tailored to you. |
| Frequency | Annually. | As often as you like—monthly or quarterly. |
| Content | Formal summary of the past year. | Detailed, forward-looking data. |
| Legal Status | Mandatory legal requirement. | Optional, but highly recommended. |
Getting this distinction right is key. While one keeps you out of trouble with the authorities, the other is your secret weapon for growth. If you're interested in harnessing this strategic tool, you can learn more about the benefits of regular management accounts.
Ultimately, you need both. Statutory accounts are your ticket to play. But management accounts? That's your playbook to win the game.
Understanding Filing Deadlines and Penalties
When it comes to your statutory accounts, think of the deadline as a fixed, non-negotiable date in the diary. Missing it isn't really an option if you want to avoid some rather unfriendly letters and financial headaches.
Honestly, keeping track of this one date is one of the most important parts of running a limited company.
For most private limited companies, the rule is pretty straightforward. Your statutory accounts must be filed within nine months of your company's financial year-end. So, if your business year wraps up on 31st December, you have until 30th September of the following year to get your paperwork submitted. Mark it in your calendar, set a reminder on your phone—stick a post-it note on the dog if you have to!
The Cost of Being Fashionably Late
So, what happens if you miss the big day? Unfortunately, Companies House doesn’t send a polite nudge; they send a penalty notice. And these are automatic, legally enforced fines that get more expensive the longer you wait.
Think of it like a library book you forgot to return. The first day it's overdue, the fine is small. A month later, it's a bit more painful. Six months later, you’re wondering if it would have been cheaper to just buy the book. The penalty system for late accounts works in a similar way, but the stakes are much higher.
This is a common pitfall for many business owners. Historically, over 10% of filings are late each year, risking not just fines but even the company being struck off the register. You can get a sense of the scale of the issue in the government's latest annual report and accounts data.
How the Penalties Stack Up
The penalty structure is designed to encourage you to file on time, with fines escalating sharply the longer you leave it.
Here’s a quick look at the typical penalties for a private limited company:
- Up to 1 month late: £150
- 1 to 3 months late: £375
- 3 to 6 months late: £750
- More than 6 months late: £1,500
An important thing to remember is that these penalties double if you file your accounts late for two years in a row. A £150 fine can quickly become £300, and a £1,500 fine turns into a whopping £3,000. That’s a lot of money that could be reinvested back into your business.
On top of the fines from Companies House, being late can also trigger penalties from HMRC for your Corporation Tax return. For more details on this, check out our guide on understanding Corporation Tax penalties. Staying on top of your deadlines isn't just about good practice; it’s about protecting your bottom line.
Your Practical Year-End Preparation Checklist
Getting your financial admin in order before handing everything over to your accountant can feel like a mammoth task, but it doesn’t have to be a last-minute panic.
Think of it as packing for a holiday; a bit of prep beforehand makes the whole trip much smoother.
This simple checklist is designed to guide you through gathering all the necessary bits and bobs. Let’s turn what feels like a chore into a straightforward, manageable process and get you ready for a stress-free year-end.
Gathering Your Core Financials
First things first, let's pull together the headline documents that form the backbone of your accounts.
- Bank and Credit Card Statements: Collect statements for every business bank account and credit card for the entire financial year. These are crucial for verifying every single transaction.
- Loan and Finance Agreements: If you’ve taken out any loans or other finance, have the paperwork ready. This includes statements showing the outstanding balances at your year-end date.
Having these documents neatly organised is a huge first step.
Tracking Your Income and Sales
Now for the good stuff—the money you’ve earned! Accurately recording your income is essential.
Your accountant will need:
- A Full List of Sales Invoices: This means every invoice you sent to customers during the year, whether they’ve paid it yet or not.
- Details of Other Income: Did you earn interest on your bank account or receive any grants? Make a note of any income that didn't come from a sales invoice.
Remember, it’s not just about what’s hit the bank account. For accounting purposes, income is often recognised when the sale is made, not when the cash arrives.
Modern accounting software like Xero makes this incredibly easy by automatically tracking invoices and payments, saving you from a frantic paper chase.
Collating Your Expenses and Purchases
This is where you get to see where all the money went! Tracking every single business expense is vital, as it reduces your profit and, in turn, your tax bill. Don’t leave any money on the table.
Your checklist for expenses should include:
- Supplier Invoices and Receipts: Gather all the bills and receipts for everything you’ve bought for the business. This covers everything from stock and software to office tea and biscuits.
- Employee Expense Claims: If your team members have claimed expenses, make sure you have all their receipts and records.
- Payroll Records: You’ll need a summary of all salaries, PAYE, and National Insurance contributions paid throughout the year.
Think of yourself as a detective, hunting down every legitimate business cost. From the big-ticket items down to the small but frequent purchases, every single one counts.
Feeling a bit overwhelmed? That’s completely normal. This checklist is here to break it down, but the real magic happens when you have an expert in your corner. If you’re ready to make your year-end process effortless, we're here to help. Get in touch with us at Artema today, and let’s make your next set of statutory accounts the smoothest one yet.
Making Statutory Accounts Effortless
After navigating the checklists and deadlines, you’re probably thinking there has to be a simpler way. The good news is, there absolutely is. Preparing and filing your statutory accounts doesn't have to be an annual ordeal that pulls you away from what you do best—running your business.
Having an expert in your corner can completely change the game, turning a legal chore into a genuine business advantage.
Beyond Compliance to Peace of Mind
Imagine getting to your year-end without that last-minute scramble for documents or the nagging worry that you’ve missed something. A trusted accounting partner handles all the fiddly details for you. We live and breathe this stuff, so you don’t have to.
This gives you something priceless: peace of mind. You can rest easy knowing that your accounts are not only filed on time, every time, but are also 100% accurate and compliant. No more stressing about penalties or surprise letters from Companies House. Just a smooth, predictable process.
Partnering with an accountant isn't just an expense; it's an investment in your business's stability and your own sanity. It frees up your time and energy to focus on what really matters.
The Power of Smart Technology
A key part of making this process so smooth is using the right tools. We build our services around powerful, user-friendly software like Xero. This isn't about using fancy tech for the sake of it; it's about creating a solid foundation of real-time, accurate financial data throughout the year.
When your bookkeeping is organised from day one, preparing year-end accounts becomes dramatically simpler. The data is already there, ready for us to work with.
Here's how this approach helps you directly:
- Real-Time Data: You always have an up-to-date view of your financial health, not just a historical snapshot once a year.
- Fewer Errors: Automation minimises the risk of manual mistakes, meaning more reliable numbers.
- Seamless Collaboration: We can access your data directly, making the year-end process faster and less of a hassle for you.
From Filing Paperwork to Fuelling Growth
At Artema, we believe statutory accounts are much more than a legal hoop to jump through. They are a rich source of insight into how your business is really performing. We don't just take your numbers and plug them into a form. We help you understand what they truly mean.
We’ll sit down with you to go through the story your accounts are telling. Where are your biggest profit drivers? Are your costs under control? How could you improve cash flow for the year ahead? These are the strategic conversations that turn compliance into a catalyst for growth.
Ready to make your year-end accounting effortless and insightful? Let’s work together to transform your statutory accounts from a chore into a strategic advantage.
Contact Artema today for a friendly, no-obligation chat and find out how we can help your business thrive.
Your Questions Answered
Still got a few things buzzing around your head about statutory accounts? That’s completely normal. We’ve pulled together some of the most common questions we hear to help clear things up.
Do I Have to File Statutory Accounts if My Company Is Dormant?
Yes, you absolutely do. Even if your company hasn't traded or earned a single penny, you're still legally required to file dormant company accounts with Companies House. The good news is they are much simpler than full accounts, but you can’t just ignore them.
Think of it as officially telling the authorities, 'Nothing to report this year, but we're still here!' Skipping this can lead to penalties and a headache you don't need.
Can I Prepare and File My Own Statutory Accounts?
Technically, yes, but it’s a bit like trying to do your own dental work – possible, but probably not the best idea! The rules are complex and constantly changing, and the risk of making a mistake is high. Getting it wrong can lead to fines or even attract unwanted attention from HMRC.
Working with an accountant isn't just about ticking boxes. It saves you a massive amount of time and stress, and a good accountant can often spot tax-saving opportunities you'd likely miss. It's about working smarter, not harder.
What Happens if I Find a Mistake After Filing?
First of all, don't panic. It happens! If you spot an error after your accounts have been filed, you can submit an amended version to Companies House to correct the public record. There's a formal process for this, and it’s best to get it sorted as soon as you can.
This is another situation where having an accountant in your corner is a lifesaver. They can handle the entire amendment process smoothly for you.
What Are Abridged Accounts and Should I File Them?
Abridged accounts are essentially a shorter, simplified version of full statutory accounts. Certain small companies can choose to file them, which means less of your financial information is on public display. It's like posting a highlights reel instead of the full movie.
To go down this route, you need to get the thumbs up from all of your company's shareholders. An accountant can tell you if your business qualifies and help you decide if it's the right move, helping you balance privacy with transparency.
Feeling clearer? Managing your statutory accounts is a fundamental part of running a successful company, but it doesn't have to be a burden. At Artema, we make it simple and stress-free.
Ready to hand over the paperwork and get back to what you do best? Get in touch with us for a chat about your needs.