
The world of tax can often feel like a maze designed by a particularly mischievous goblin, but understanding Capital Gains Tax (CGT) is more straightforward than you might think. Depending on your income and what you've sold, the rate you'll pay is either 10%, 18%, 20%, or 24%.
For most assets, like that portfolio of shares you’ve been nurturing, basic rate taxpayers pay 10%, while higher rate taxpayers pay 20%. If you’re selling a residential property that isn’t your main home (think a buy-to-let or a holiday cottage), the rates are a bit steeper at 18% and 24% respectively.
Understanding Capital Gains Tax in Plain English
Let's be honest, "Capital Gains Tax" sounds like something you’d rather ignore. But what if we boiled it down? Think of it like this: when you sell something valuable for more than you originally paid for it, the government asks for a small slice of that profit.
That profit is your 'capital gain', and that slice is Capital Gains Tax (CGT). Simple as that. It’s like selling a concert ticket for more than you paid, but for bigger things and with HMRC watching.
This tax applies when you ‘dispose of’ an asset. Now, ‘disposing’ isn't just about selling. It can also mean gifting an asset to someone, swapping it for something else, or even getting an insurance payout if it's been lost or destroyed. The key thing to remember is that it's the profit that gets taxed, not the total amount you receive.
Who Needs to Pay Attention?
Most people will come across CGT at some point, particularly if they are investors or own more than one property. You’re typically in the CGT zone if you sell assets such as:
- Shares that are not held in a tax-free ISA or PEP
- A second home or a buy-to-let property
- Valuable personal belongings like antiques, artwork, or jewellery
- Your own business
The good news is that not everything is taxed. Your main home, your car, and any assets held within an ISA are usually exempt from CGT.
Believe it or not, Capital Gains Tax isn't a new idea. It was first introduced back in 1965 at a flat rate of 30%, largely to tackle the booming property market. Over the decades, its structure has evolved significantly, leading us to the tiered system we use today. You can find out more about the history of UK tax changes online.
Before we get into the nitty-gritty, here’s a quick cheat sheet with the rates you need to know.
UK Capital Gains Tax Rates at a Glance
This table gives a quick summary of the current CGT rates based on your income tax band and the type of asset you've sold.
| Your Income Tax Band | CGT Rate on Most Assets (e.g., Shares) | CGT Rate on Residential Property (Not Your Main Home) |
|---|---|---|
| Basic Rate | 10% | 18% |
| Higher Rate | 20% | 24% |
Feeling a bit clearer? We hope so! Now, let’s find out if this is something you actually need to worry about.
If you're ever unsure about your situation, getting professional advice is always a smart move. Here at Artema, we can help you understand your tax obligations and plan effectively to make sure there are no nasty surprises down the line.
Do You Actually Need to Pay Capital Gains Tax?
Before you reach for the calculator and a strong cup of tea, let's first figure out if Capital Gains Tax (CGT) is even something you need to worry about. Think of this as a quick check—a way to see if you need to read the rest of this guide, or if you can happily get back to your day.
It all boils down to whether you've sold, or more accurately, 'disposed of' something of value.
The term 'disposing of an asset' sounds a bit dramatic, like you’re launching it into space. In reality, it simply means you no longer own it. While selling it is the most obvious route, it also covers a few other scenarios:
- Gifting it to someone (unless that someone is your spouse or a charity).
- Swapping it for something else of value.
- Receiving an insurance payout if an asset was lost or destroyed.
So, if you've done any of these things and made a profit in the process, CGT might be on the cards.
The Usual Suspects for CGT
Certain assets are notorious for catching HMRC's eye. You'll most likely be looking at a CGT bill if you've profited from selling:
- A buy-to-let property or a second home. This is a big one for many landlords and property investors. If this is you, our guide on the tax implications of buy-to-let properties has more detail.
- Shares or investments that aren't safely tucked away in a tax-free wrapper like an ISA.
- Personal belongings worth more than £6,000 each—things like jewellery, paintings, or antiques (but your car gets a free pass!).
- Your own business or valuable business assets.
Think of it like a party. Your main home, your car, and your ISAs get to chill in the VIP lounge, completely tax-free. Other assets, like your second property or share portfolio, are on the main dance floor where the CGT rules apply.
What’s Usually Exempt?
Now for the good news. A surprising number of things are completely safe from CGT, which is a huge relief for most people. You generally do not have to worry about paying this tax on profits from:
- Your main home: Thanks to something called Private Residence Relief, the home you actually live in is almost always exempt.
- Your car: No matter how much of a classic it might be.
- Assets held inside an ISA or PEP: These are your tax-free savings superheroes.
- UK government gilts and Premium Bonds: They’re exempt right from the start.
- Any winnings from the lottery, betting, or pools. Phew!
By now, you should have a much clearer idea of whether CGT applies to your situation. If you’ve recently sold a second property or some shares, stick with us. If you’ve only sold your car or had a lucky win on the lottery, you can probably relax.
Your Tax-Free Allowance: The Magic Number
Right, let’s get to the good news. Just when you think it’s all about paying up, the tax system does occasionally throw you a bone. Every individual gets a tax-free allowance for capital gains each year, which is officially known as the Annual Exempt Amount (AEA).
Think of it as your personal tax-free bubble. It’s a set amount of profit you can make each tax year without having to pay a single penny of Capital Gains Tax.
This allowance is a cornerstone of smart tax planning. By using it wisely, you can time the sale of your assets to crystallise gains up to this limit each year, legally keeping more of your hard-earned money away from the taxman. It's the first and most important tool in your tax-reduction toolkit.
What Is the Current Allowance?
This is where you need to pay close attention because things have changed quite a bit recently. The government likes to keep us on our toes by adjusting these figures, and the AEA has seen a significant haircut.
For the current 2024-2025 tax year, the Annual Exempt Amount is:
- £3,000 for individuals and personal representatives.
- £1,500 for most trustees.
This is a sharp drop from where we were. It wasn't that long ago that this allowance was far more generous, giving investors and property owners a lot more breathing room.
The big shift happened in the 2023 to 2024 tax year when the Annual Exempt Amount was slashed from £12,300 down to £6,000 for individuals. This single change was estimated to bring around 83,000 additional people into the CGT net who were previously protected by the higher threshold. You can learn more about the impact of these tax changes on the government's website.
This reduction makes it more important than ever to understand what the capital gain tax rate is and how this smaller allowance affects your potential bill. You can no longer rely on a large tax-free buffer to shield your profits.
Making the Magic Number Work for You
So, how can you use this £3,000 allowance to your advantage? The key is planning.
If you have a large portfolio of shares, for example, you could consider selling a portion each year to realise gains that fall under the tax-free limit. This strategy helps you chip away at your profits over time without triggering a large tax bill in one go.
Understanding this allowance is your first step towards getting to grips with your tax situation. But what happens once your gains exceed this magic number? That’s when we need to get the calculator out, which we’ll cover in the next section.
If you’re unsure how these changes affect your investments or property sales, don’t hesitate to get in touch. We can help you navigate the new rules and make a plan that works for you.
How to Calculate Your CGT Bill Without a Headache
Right, time for the maths. Don’t panic! Calculating your Capital Gains Tax (CGT) bill sounds more intimidating than it actually is. We’ll break it down into a simple, step-by-step process that won't require a degree in advanced calculus.
At its core, the calculation is beautifully simple: work out your profit, take off any allowable costs, subtract your tax-free allowance, and then apply the correct tax rate to what’s left. Easy, right? Let's get started.
Step 1: Work Out Your Total Gain
First things first, you need to figure out your total profit. The basic formula is something you probably learned in primary school: what you sold it for, minus what you paid for it.
Sale Price – Purchase Price = Your Basic Gain
So, if you bought a piece of art for £10,000 and sold it for £25,000, your basic gain is a tidy £15,000. But hold on, don’t start writing a cheque to HMRC just yet. It’s rarely that simple, and this is where you can make some smart savings.
Step 2: Deduct Your Allowable Costs
This is the fun part—shrinking your gain! HMRC allows you to deduct certain costs you incurred when buying, selling, or improving your asset. Think of these as legitimate expenses that reduce your overall profit, and therefore your tax bill.
Common allowable costs include:
- Fees for buying and selling: This covers things like solicitors' fees, stamp duty, estate agent commissions, or stockbroker fees.
- Costs of improvement: If you spent money enhancing the asset’s value (like building an extension on a buy-to-let property), you can often deduct these costs. Note that normal maintenance, like a quick repaint, doesn't count.
- Valuation fees: Any costs for having the asset professionally valued can also be included.
Once you’ve tallied these up, subtract them from your basic gain. This gives you your final, taxable gain.
Step 3: Apply Your Tax-Free Allowance
Now it’s time to use that magic number we talked about earlier—your Annual Exempt Amount (AEA). For the 2024-2025 tax year, this is £3,000. You can deduct this full amount from your final gain.
This simple infographic shows how your profit is reduced by the annual allowance before any tax is calculated.
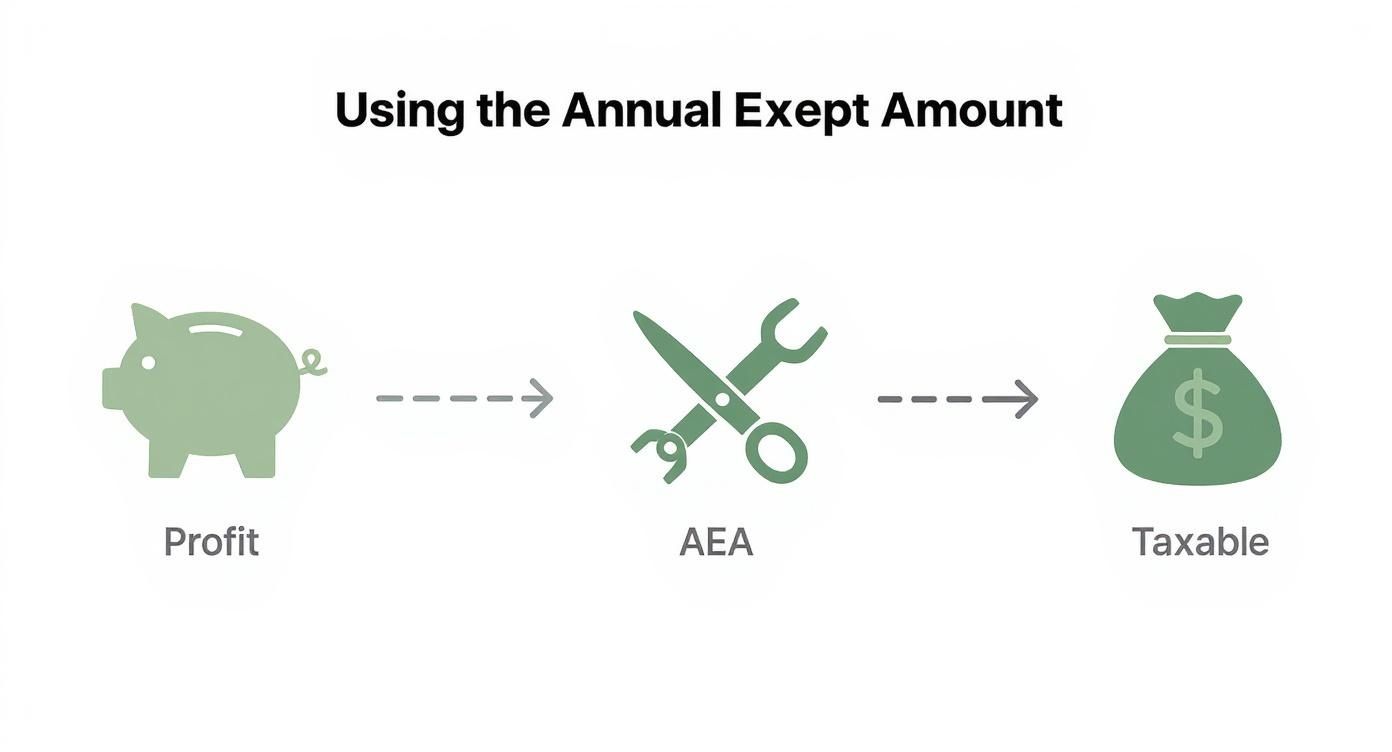
As you can see, the allowance directly cuts down the amount of profit that HMRC can actually tax.
Let's put this into practice with a couple of real-world examples.
Example 1: Selling Shares
You sell some shares for £30,000. You originally bought them for £15,000, and the broker fees for buying and selling totalled £500.
- Calculate the gain: £30,000 (sale) – £15,000 (purchase) – £500 (costs) = £14,500
- Deduct the allowance: £14,500 (gain) – £3,000 (AEA) = £11,500
Your taxable gain is £11,500. The final tax bill will depend on your income tax band (10% or 20%).
Example 2: Selling a Buy-to-Let Property
You sell a rental property for £250,000. You bought it years ago for £150,000. You paid £4,500 in stamp duty and legal fees when you bought it, and another £3,000 in estate agent fees when you sold it.
- Calculate the gain: £250,000 (sale) – £150,000 (purchase) – £7,500 (total costs) = £92,500
- Deduct the allowance: £92,500 (gain) – £3,000 (AEA) = £89,500
Your taxable gain is £89,500. Since this is residential property, the tax rate will be either 18% or 24%, depending on your income.
Feeling overwhelmed? Don’t worry. Calculating CGT can be tricky, especially with property. If you need a hand making sure your calculations are spot on, get in touch with our team at Artema—we’re here to help.
Smart Ways to Reduce Your Capital Gains Tax
Paying tax is part of the deal, but paying more than you legally have to? That’s just leaving money on the table. Think of this section as your playbook for making smart, ethical moves to minimise what you owe HMRC. It's not about finding sneaky loopholes; it’s about using the rules to your advantage.
Let's explore some of the most effective strategies that savvy investors and business owners use every day. These are practical, legitimate ways to keep more of your hard-earned profits in your pocket.
Use Every Allowance And Exemption
You wouldn't turn down a "buy one, get one free" offer at the supermarket, so don’t ignore your tax-free allowances! These are the simplest, most powerful tools for shrinking your CGT bill.
- Your Annual Exempt Amount (AEA): We’ve mentioned the £3,000 tax-free allowance. The golden rule here is simple: use it or lose it each tax year. Spreading your gains across different years can make a huge difference.
- Bed and Spouse: You can transfer assets to your spouse or civil partner without triggering a capital gain. This is incredibly useful as it lets you use both of your annual allowances, effectively doubling your tax-free buffer to a combined £6,000.
- ISAs and Pensions: These are your tax-free fortresses. Any gains made on investments held inside an ISA or a pension are completely sheltered from CGT. It’s a no-brainer to maximise these accounts first.
Think of tax planning like packing a suitcase. You wouldn't just throw everything in and hope for the best. You fold neatly, use all the pockets, and plan what goes where. Using your allowances and tax-efficient accounts is the financial equivalent of packing smart.
Explore Special Tax Reliefs
Beyond your standard allowances, the government offers some very generous reliefs designed to encourage certain types of investment and business activity. These can dramatically slash, or even completely wipe out, your CGT liability.
One of the most valuable reliefs out there is Business Asset Disposal Relief (BADR), which you might remember as Entrepreneurs' Relief. If you sell all or part of your business, this relief lets you pay CGT at a reduced rate of just 10% on qualifying gains, up to a lifetime limit. It’s an absolute game-changer for business owners. If you think this might apply to you, it's worth understanding the specifics of how ordinary shares qualify for CGT relief.
For property investors, the options in the UK can sometimes feel more limited. It’s interesting, though, to look at how other countries approach this. In the US, for example, property investors have a powerful tool for deferring taxes and compounding wealth by understanding the 1031 Exchange. While this specific mechanism doesn't apply here, it highlights the importance of exploring every relief available to you, no matter your asset class.
Figuring out which strategies are right for you really depends on your personal circumstances. What works for someone with a share portfolio won't necessarily be the best move for a landlord or a business owner looking to sell up.
This is where getting proper advice becomes invaluable. If you're wondering how these strategies could be applied to your own financial situation, reach out to us at Artema. We can help you build a plan that makes sure you’re not giving HMRC a bigger tip than you need to.
Reporting and Paying CGT Without Missing Deadlines
You’ve calculated your profit and figured out the tax – congratulations, the hardest part is over! Now, it’s time to tell HMRC.
This final step is crucial, and the taxman isn't a fan of missed deadlines, so let's make sure you stay on his good side.
The rules for reporting depend entirely on what you’ve sold. Not all assets are treated equally, and getting this wrong can lead to unnecessary penalties. Think of it as having two separate clocks ticking down.
For most assets, like shares or artwork, the process is quite relaxed. You simply report the gain on your annual Self Assessment tax return. The deadline for this is usually the 31st of January following the end of the tax year in which you made the gain.
The Property Deadline You Cannot Ignore
However, if you've sold a UK residential property, you need to act much faster.
HMRC has a special 60-day window from the date of completion to both report the gain and pay the tax you owe. Forgetting this can be a costly mistake. Our guide on handling capital gains when selling a property provides more detail on this specific process.
The key takeaway is simple: selling a second home requires immediate action, while selling other assets gives you more breathing room. Always know which clock you're racing against to avoid any last-minute panic.
The rules can also vary for different investment types. For example, if you're an active trader, it's vital to understand how covered call premiums and assignments are taxed, as these often have specific reporting requirements.
Feeling a bit tangled in deadlines? Contact Artema today, and we’ll help you get everything filed correctly and on time, without the stress.
Your Capital Gains Tax Questions Answered
We’ve covered a lot of ground, but there are always a few questions that pop up time and again. Don’t worry, you’re not the only one wondering! Here are some quick answers to a few common head-scratchers.
What Happens If I Make a Capital Loss?
Selling an asset for less than you paid for it results in a capital loss. You can't deduct this loss from your income tax, but it’s not useless. It's more of a silver lining.
You can use it to offset any capital gains you’ve made in the same tax year, which can reduce your overall CGT bill. If you have any loss left over, you can carry it forward to reduce your gains in future years.
Do I Pay CGT on Inherited Assets?
No, not at the point of inheritance. When you inherit an asset, you effectively acquire it at its market value on the date the person passed away.
You’ll only have to think about CGT if you decide to sell that asset later on and it’s increased in value since you inherited it.
Is My Main Home Always Tax-Free?
For the most part, yes! Your main home is usually exempt from Capital Gains Tax thanks to something called Private Residence Relief.
However, you might find yourself with a tax bill if you’ve ever let it out to tenants or used part of it exclusively for your business.
Getting to grips with the rules around what the capital gain tax rate is can feel like a bit of a minefield. If you want to be sure you're getting it right and making the most of your assets, the expert team at Artema Ltd is here to help you plan effectively.