
Ever feel like your business is a leaky bucket? Money flows in, gushes out, and you're left wondering if there's enough cash left to keep the lights on. It’s a common feeling, but luckily, it's one you can get a handle on.
So, what is working capital management? In simple terms, it's the art of juggling your daily cash, customer IOUs, and supplier bills to keep your business running smoothly. Think of it as financial plate-spinning, but way less stressful once you know the trick.
The Secret Ingredient for Financial Health
Imagine your business is a local bakery. You've got cash in the till, flour in the stockroom, and invoices you've sent out to a café for their weekly cake order. These are all your current assets – the good stuff.
At the same time, you have bills to pay: your supplier needs paying for the flour, your landlord wants the rent, and your staff are expecting their wages. These are your current liabilities – the stuff you owe.
Working capital management is simply making sure the money from your cake sales lands in your bank account before the money for flour and rent needs to go out. It’s about keeping enough cash—or working capital—on hand to cover your day-to-day operations without breaking a sweat. This isn’t about long-term investments or five-year plans; it's about the financial heartbeat of your business, right now.
To give you a clearer picture, here’s a simple breakdown using our bakery example.
Working Capital At a Glance
| Component | What It Is In Simple Terms | Real-World Example for a UK Cafe |
|---|---|---|
| Current Assets | Things you own that can quickly turn into cash (within a year). | Cash in the till, money owed by a corporate client for a large catering order, and your stock of coffee beans and milk. |
| Current Liabilities | Bills and debts you need to pay off soon (within a year). | Your monthly rent, the invoice from your bakery supplier for pastries, and upcoming payroll for your baristas. |
| Working Capital | The money left over after you pay your immediate bills. It's your financial cushion! | The cash you have on hand after setting aside enough to cover rent, supplier invoices, and wages for the month. |
This simple formula—Assets minus Liabilities—shows you the cash you have available to fuel your business's daily activities.
Why This Juggling Act Matters
Mastering this flow is absolutely critical, especially for UK businesses navigating an ever-changing economic climate. As the Bank of England often points out, smart cash management is what helps businesses stay resilient, even when the wider economy feels a bit wobbly.
Without a good handle on it, a business can be profitable on paper but still run out of cash. Imagine our baker sells thousands of pounds worth of wedding cakes, but the clients don't pay for 90 days. They might not have enough ready money to buy flour for next week's orders, and a profitable business suddenly finds itself in a cash crunch. Yikes.
Working capital management isn't just an accounting task; it’s a survival strategy. It’s the difference between confidently paying your bills and desperately hoping a big customer pays their invoice today.
This is where good financial habits become your superpower. Having a clear, real-time view of your incomings and outgoings is the first step. For instance, this is exactly how bookkeeping helps your business save time and money; it gives you that up-to-the-minute picture of your financial position, making it so much easier to stay on top of your cash flow.
Meet the Three Pillars of Working Capital
To really get to grips with working capital management, you need to understand the power trio that runs the show. Think of them as the three main characters in your business's financial story: Accounts Receivable, Accounts Payable, and Inventory. Getting to know them is the key to mastering your cash flow.
Let's imagine we're running "Cosy Knits Co.," a small online shop in the UK selling handmade scarves. Every single day, these three pillars are in a constant dance, and managing them well is what keeps Cosy Knits in business.
This simple infographic shows how your assets and liabilities come together to create your working capital—the engine that powers your daily operations.
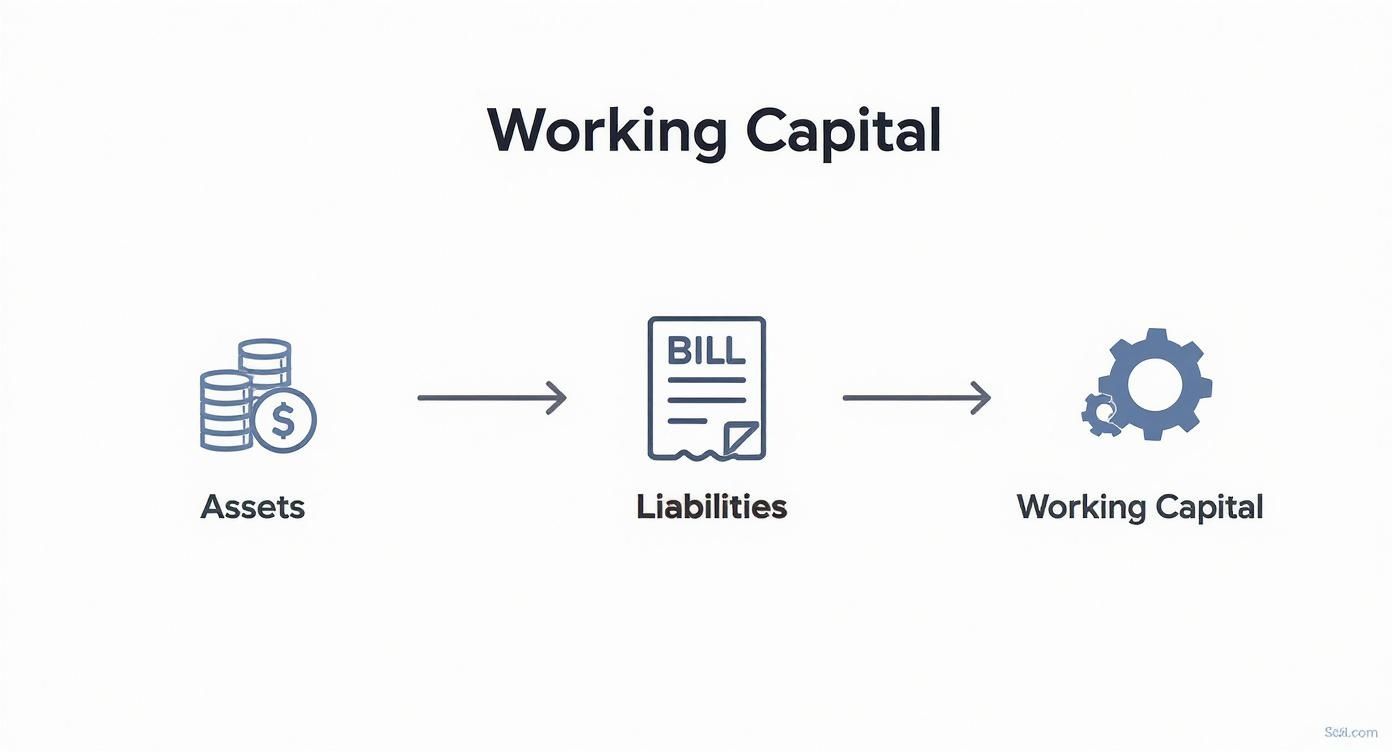
As you can see, working capital is what's left when you subtract what you owe from what you have readily available. This is the financial flexibility you need to run your business and grab new opportunities.
Pillar 1: Accounts Receivable (The Money You're Owed)
Accounts Receivable is just the fancy term for the invoices you've sent out that haven't been paid yet. It's the money your customers owe you. For Cosy Knits Co., this is the payment they're waiting on from a boutique that bought 50 scarves on credit.
The goal here is simple: get that money in your bank account as fast as possible. The longer cash is sitting in your customer's account, the less you have to cover your own costs. Chasing invoices isn't nagging; it’s a vital part of keeping your business healthy!
A recent study found that UK small businesses are chasing an average of five outstanding invoices at any given time, tying up crucial cash. This makes speedy collection a top priority for healthy working capital.
Getting that cash in the door faster is like giving your business an instant, interest-free loan. You can then use that money to buy more yarn or pay your marketing agency.
Pillar 2: Accounts Payable (The Bills You Owe)
Next up, we have Accounts Payable. This covers all the bills your business needs to pay. For Cosy Knits, this includes the invoice from their wool supplier and the bill for their website hosting.
It might feel responsible to pay bills the second they land on your desk, but that's not always the smartest move. Managing your payables strategically means paying them on time to keep suppliers happy, but not too early. If a bill is due in 30 days, holding onto that cash for 29 days means it’s still working for you.
This is a balancing act. You need to maintain great relationships with your suppliers (who wants an angry wool farmer?) while maximising the cash you have on hand. For a deeper dive into organising these figures, exploring professional management accounts can provide a much clearer picture of your financial obligations and timelines.
Pillar 3: Inventory (The Cash on Your Shelves)
Finally, there’s Inventory. For our scarf shop, this is every ball of yarn and every finished scarf sitting in the stockroom. Each one of those items represents cash that’s been spent but hasn't yet been turned back into profit.
Having too much inventory is a big risk. It’s your capital just sitting there on a shelf, collecting dust and possibly going out of fashion. But having too little is just as bad—you can't sell what you don't have, which leads to lost sales and unhappy customers.
The sweet spot is holding just enough stock to meet demand without hoarding mountains of yarn. Effective working capital management is all about turning that inventory back into cash as efficiently as you possibly can.
Why Mastering Working Capital Is a Game Changer
So, you’ve met the main players in your business's daily financial drama. But why should you care about managing them? Honestly, this isn't just more tedious admin; it’s the difference between a business that's constantly scrambling and one that's confidently scaling.
Getting a handle on your working capital isn’t just good practice—it’s a genuine game-changer.
Proper working capital management gives your business a massive boost in several key areas. Think of it as upgrading your company’s financial operating system. Suddenly, everything just runs smoother, faster, and with far fewer crashes.
Boost Your Profitability
First off, smart management directly improves your bottom line. When you know exactly what stock you have and how quickly it sells, you stop tying up cash in products that just sit there gathering dust. This means lower storage costs and less money wasted on unpopular items.
And when your cash flow is healthy, you have more power. You can:
- Negotiate better deals: Pay suppliers early in exchange for a discount.
- Buy in bulk: Seize opportunities to buy materials at a lower price when you have cash on hand.
- Avoid costly loans: Steer clear of expensive overdraft fees or last-minute loans to cover unexpected bills.
These small wins quickly add up, making your business more profitable without having to sell a single extra product.
Grab Opportunities and Dodge Disasters
Imagine your biggest competitor suddenly goes out of business, and their prime retail location becomes available. Or a supplier offers you an incredible one-off deal on essential stock. A business with poor working capital can only watch these opportunities pass by. A business with healthy cash flow can pounce.
Good working capital management is about more than just survival; it's about giving yourself the financial freedom to be ambitious. It transforms your business from a reactive one to a proactive one.
This financial agility also acts as a crucial safety net. When the boiler breaks or a key client pays late, you won’t have sleepless nights wondering how you’ll make payroll. You’ll have the cash reserves to handle the hiccup and carry on.
The Cautionary Tale of a Cash-Poor Startup
Consider the story of a fast-growing tech startup. They were celebrated in the press, landing huge contracts and hiring talented staff. On paper, they were a roaring success.
The problem? They offered generous 90-day payment terms to their big clients while needing to pay their developers every 30 days.
Soon, they were profitable but completely out of cash. They couldn't cover their own bills and, despite massive potential, had to shut down. This is a classic working capital nightmare—a brilliant business failing not from a lack of profit, but a lack of available cash. It’s a powerful reminder that revenue is vanity, profit is sanity, but cash is king.
Ready to take control of your cash flow? Our team can help you build a solid financial foundation so you can focus on growth. Get in touch with Artema today!
Actionable Techniques to Improve Your Cash Flow
Right, enough theory. Knowing what working capital management is feels good, but actually improving it feels even better. Think of this section as your toolkit, packed with practical, straightforward techniques you can start using today to get your cash flow humming.
We're going to break this down into the three pillars we met earlier: getting paid (receivables), managing stock (inventory), and paying your bills (payables). Let's dive in.
Get Paid Faster From Your Customers
Chasing money is no one's favourite pastime, but it’s absolutely essential. The goal here is simple: shrink the time between doing the work and seeing the cash land in your bank account.
-
Send Crystal-Clear Invoices: Make your invoices impossible to misunderstand. Clearly state the amount due, the due date, and precisely what the payment is for. The less thinking a customer has to do, the faster you'll get paid.
-
Offer a Cheeky Discount: Consider offering a small discount, say 2%, for customers who pay within 10 days instead of the usual 30. It’s a win-win; they save a little, and you get your cash weeks earlier.
-
Automate Your Reminders: Set up friendly, automated email reminders that go out a few days before an invoice is due, on the due date, and a few days after if it’s late. It takes the awkwardness out of chasing and ensures nothing gets missed.
Beyond optimising receivables and payables, businesses should also focus on implementing chargeback prevention strategies. Each successful chargeback is a direct hit to your available cash, making prevention a powerful, yet often overlooked, tool in your financial arsenal.
Take Control of Your Inventory
Every item sitting on your shelf is cash you can't use. Smart inventory management is about striking that perfect balance between having enough to sell and not having too much gathering dust.
A great approach is the Just-in-Time (JIT) method. This means ordering stock only as you need it, which cuts down on storage costs and minimises the risk of being left with unsold goods. It does require a close relationship with reliable suppliers, but it can dramatically free up your working capital.
Don't let your stockroom become a museum for your money. Aim for it to be more like a busy train station, with goods arriving just in time to be shipped out to happy customers.
For a comprehensive look at improving your cash flow from the ground up, you might be interested in our guide on the 5 steps to create a cash flow for your business, which expands on many of these core ideas.
Manage Your Bills Wisely
Finally, let's talk about the money going out. While it’s tempting to pay bills the moment they arrive just to get them off your desk, it’s often smarter to hold onto your cash for as long as ethically possible.
Use the full credit period your suppliers offer. If an invoice is due in 30 days, use that time to let your cash work for you. Schedule the payment for day 29. This isn't about paying late; it's about using the agreed-upon terms to your advantage.
Don't be afraid to negotiate, either. If you're a loyal, reliable customer, ask your key suppliers for better terms. An extension from 30 to 45 days can make a huge difference to your cash flow, giving you an extra two weeks of breathing room. Most suppliers will be happy to help a good customer.
Common Working Capital Mistakes to Avoid
We all learn from our mistakes, but when it comes to cash flow, some blunders are best avoided altogether. Think of this section as your friendly early-warning system, designed to sidestep the classic working capital traps that can snare even the smartest small businesses.
Let's shine a light on these common pitfalls and, more importantly, how to dodge them.
Managing your day-to-day finances effectively is always crucial, but the pressure is even higher in the current climate. The UK's economic landscape, with its high inflation and rising costs like the National Living Wage, makes sharp working capital management more important than ever. Companies are feeling the squeeze, which is why sidestepping these errors is a must. You can read more about how economic factors influence business cash flow in the UK on kpmg.com.
The "Stockroom Museum" Problem
One of the most common mistakes is tying up too much cash in stock. It feels safe to have shelves groaning with products, but every unsold item is your money gathering dust.
It's like turning your stockroom into a very expensive museum of things you hope to sell one day. This locks up funds that could be used for marketing, paying staff, or jumping on a new opportunity.
The Dodge: Get to know your sales data. Identify your bestsellers and your slow-movers. You could use a "just-in-time" approach for some items, ordering them only when needed, and consider a flash sale to turn that dusty stock back into lovely, useful cash.
Being Too Relaxed About Payments
You've done the work, you've sent the invoice. Job done, right? Not quite.
Being too casual about when customers pay is a recipe for a cash flow crunch. A polite but passive approach often means your invoice ends up at the bottom of your client's to-do list, leaving you waiting for money that is rightfully yours.
Remember, your business is not a bank. Extending informal, long-term credit to customers drains your own working capital and puts your financial health at risk.
The Dodge: Be proactive and professional. Set up automated reminders before, on, and after the due date. Make it incredibly easy for customers to pay you online. And don't be afraid to pick up the phone—a friendly chat is often all it takes to get an invoice settled.
Forgetting to Look Ahead
Running a business day-to-day is hectic, and it’s easy to get tunnel vision. A major mistake is failing to forecast your future cash needs. This is especially dangerous before a big holiday season or a planned expansion.
Without a forecast, you could find yourself with a huge order to fulfil but no cash to buy the raw materials.
The Dodge: Create a simple cash flow forecast. It doesn't need to be a complex masterpiece. Just map out your expected income and outgoings for the next three to six months. This simple exercise will highlight potential shortfalls well in advance, giving you plenty of time to act.
Avoiding these common mistakes is a huge step towards financial resilience. If you're ready to build a proactive strategy for your business's cash flow, our team at Artema is here to help you navigate the path to success.
Your Top Working Capital Questions Answered
We’ve dug into the what, why, and how of managing your working capital. But I know there are probably a few specific questions still buzzing around. Let's run through some of the most common ones to clear things up.
What Is a Good Working Capital Ratio?
You’ll hear accountants and bank managers talk about the working capital ratio, and a healthy target is usually somewhere between 1.5 and 2.0. Put simply, this means you have between £1.50 and £2.00 in current assets (like cash and stock) for every £1 you owe in short-term liabilities (like supplier bills). It's a comfortable safety net.
If your ratio drops below 1.0, that’s a bit of a red flag. It suggests you might struggle to pay your bills on time. But here's an interesting twist: a really high ratio isn't necessarily a good thing either. It could mean you've got too much cash just sitting in the bank, not being put to work growing the business. The perfect ratio really depends on your industry and business model.
How Can I Improve My Working Capital Quickly?
Need to give your cash flow a quick boost? No need to panic. There are a few simple moves you can make that have a surprisingly big impact.
- Chase your invoices: Be polite but firm about following up on overdue customer payments. Sometimes a friendly phone call is all it takes to get things moving.
- Shift slow-moving stock: Got products gathering dust on the shelves? A flash sale can turn them back into cash. It’s better to get that money back in the business, even at a small discount.
- Talk to your suppliers: Give your main suppliers a ring and see if they’d be willing to extend your payment terms by a week or two. You’d be surprised how often a simple ask can give you the breathing room you need.
These small, targeted actions can inject some much-needed cash back into your operations when you need it most.
Remember, the goal isn't just about having cash; it's about how quickly that cash moves through your business. A fast cash conversion cycle is the hallmark of a really healthy, efficient company.
Can Negative Working Capital Ever Be a Good Thing?
It sounds completely counterintuitive, but in some very specific cases, yes! Take a huge supermarket chain, for example. You pay for your groceries instantly at the checkout, but the supermarket might have 30 or even 60 days to pay its suppliers for those goods.
In this scenario, they are effectively using their suppliers' money to fund their day-to-day operations. This only really works for businesses with lightning-fast stock turnover and enormous buying power. For most small and medium-sized UK businesses, negative working capital is a serious warning sign of financial distress, not a sign of operational genius.
Feeling more confident about what working capital management means for your business? Keeping a firm grip on your finances is the key to unlocking growth and giving you peace of mind. At Artema Ltd, we specialise in helping business owners like you get a clear view of their numbers so they can make smarter, more informed decisions.
Ready to stop guessing and start managing with confidence? Visit us at Artema to see how our expert accounting services can help your business thrive.